Tax Debt & Family
Divorce and IRS Debt: Who Pays After the Split? (2026)
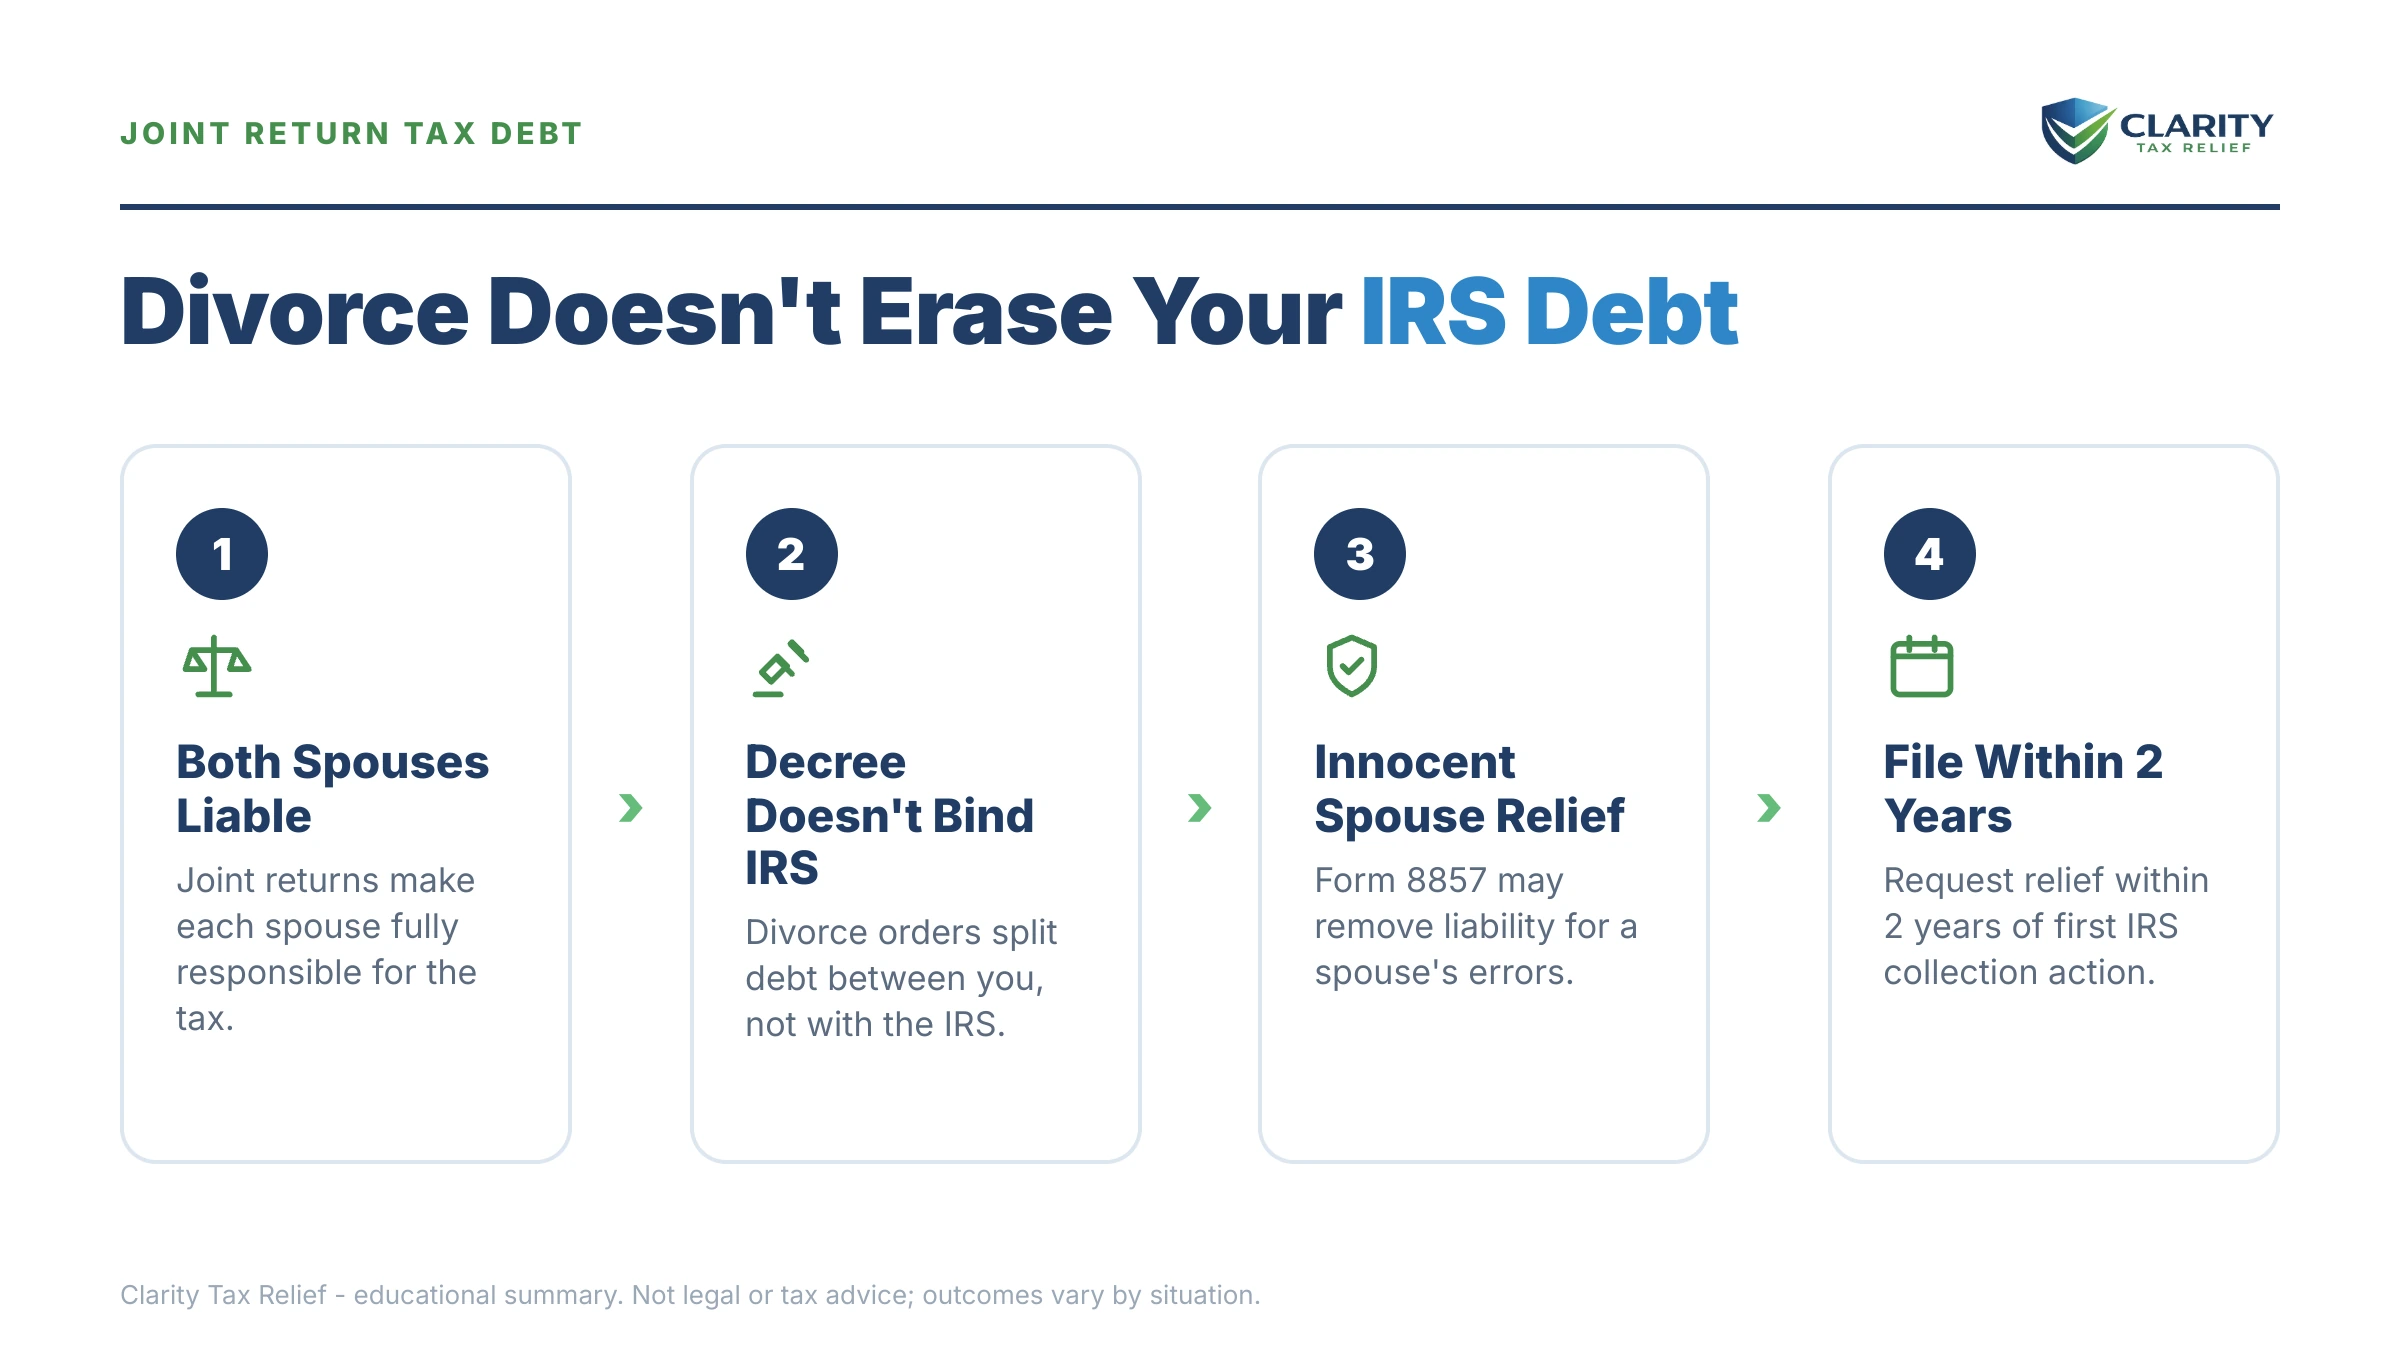
The short answer: after divorce, the IRS can collect 100% of a joint-return tax debt from either ex-spouse. Your divorce decree does not bind the IRS. Debt from a separately filed return belongs only to the person who signed it. Innocent spouse, separation of liability, and equitable relief can shift joint debt, but only if you request them.
What this guide covers: who the IRS can collect a joint tax debt from after a divorce, why your decree does not stop that collection, the three IRS relief programs that can move the debt off you, the deadlines that control each one, and the order to take action in when a levy notice has already arrived.
You did everything the lawyers told you to. The decree says your ex pays the back taxes. And the letter in your hand, addressed to you at your apartment, says the IRS intends to levy your paycheck for a balance you thought was settled in court.
Nobody explains this part during a divorce. On the question of "divorce, who pays IRS debt," the IRS follows the tax return. If you signed a joint return, you signed up for the whole bill. The fix lives in a specific set of IRS relief programs rather than in family court, and the strongest of those programs have a hard deadline.
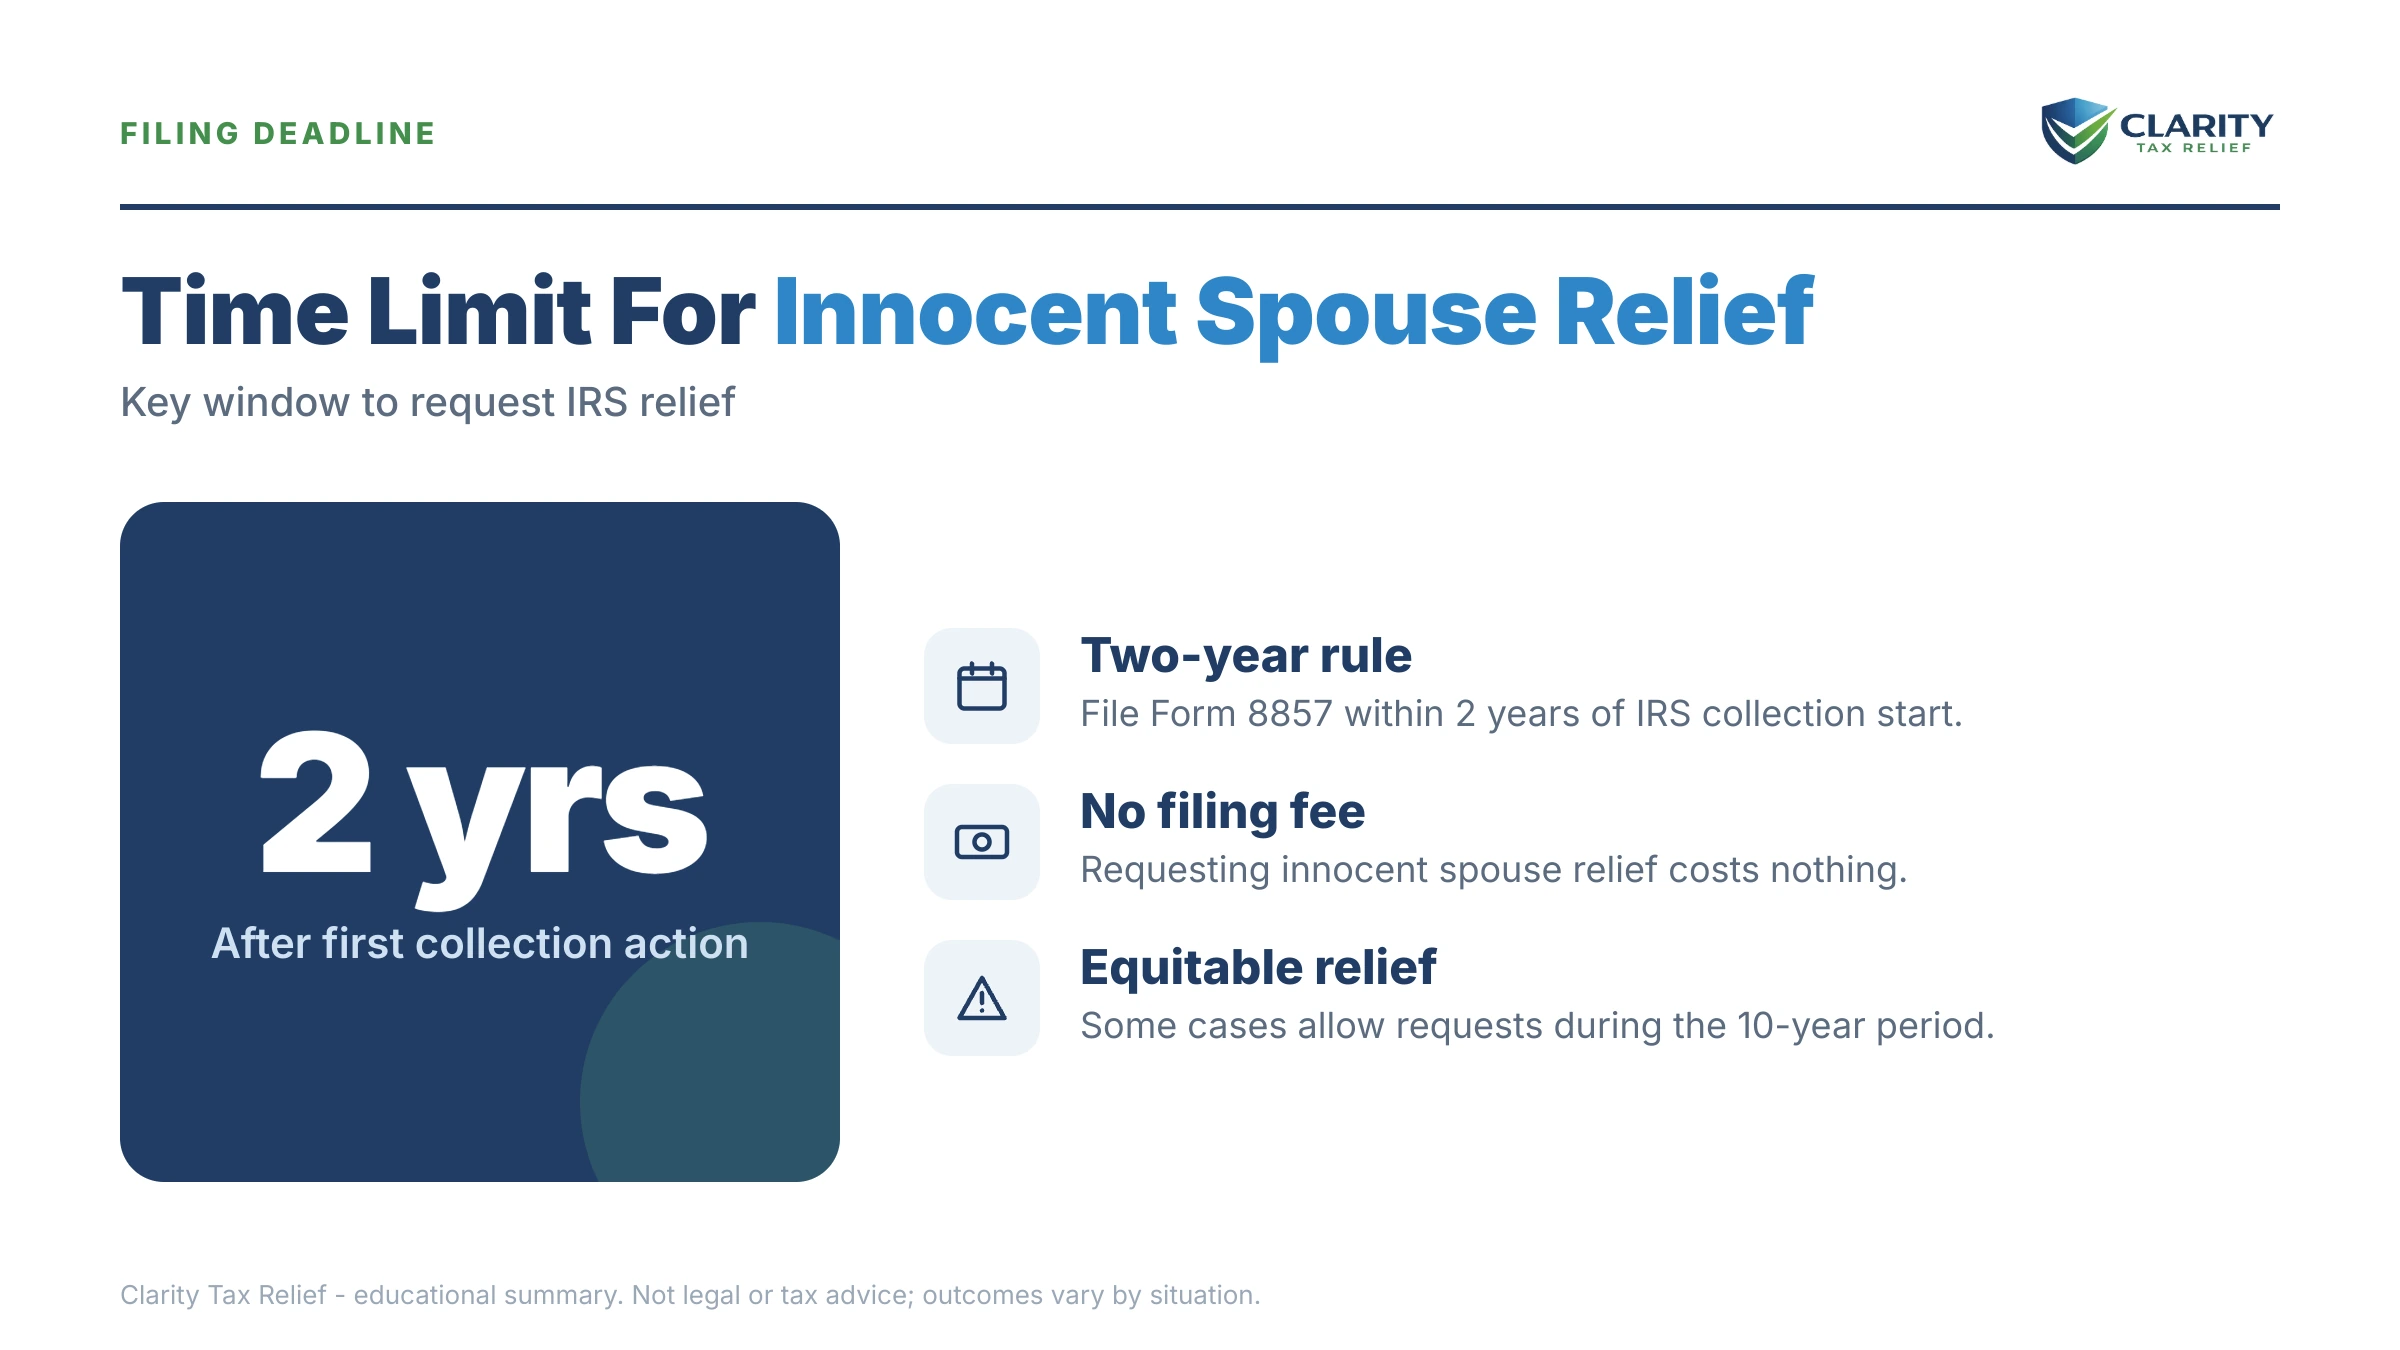
⏱ Your deadline: you generally have 2 years from the IRS's first collection activity against you, often a seized refund or a levy notice, to request innocent spouse relief or separation of liability on Form 8857. Equitable relief stays open longer. The two strongest relief types end with that two-year window.
Who pays IRS debt after divorce when the decree says your ex does?
Why can the IRS collect from either ex-spouse?
Both ex-spouses owe 100% of any tax debt from a jointly filed return. The IRS calls this joint and several liability, and divorce does not end it. The IRS can collect the entire balance from you, the entire balance from your ex, or pieces from both, in whatever order is easiest for the government.
Sort your debt into three buckets, because each has a different answer:
- Joint-return years. Any year you filed "married filing jointly," both of you owe everything: tax, penalties, and interest. This is where all the relief programs below live.
- Separate-return years. If your ex filed "married filing separately" or the debt was assessed only against them (a business penalty, a CP2000 on a return you never signed), it is their debt alone. The IRS cannot levy your wages for it.
- Post-divorce years. Anything either of you runs up after the divorce is final belongs solely to the person who owes it.
So why does the decree feel worthless? Because the IRS was never a party to your divorce. A judge in family court can order your ex to pay, and can hold them in contempt if they refuse, but cannot order a federal agency to stop collecting from you. That gap is exactly why the IRS ignores divorce decree IRS debt assignments, and why the real fix runs through Form 8857 instead of your attorney's demand letter.
One more wrinkle. In practice, the IRS collects from whoever is easiest to find. If you have a W-2 job and a bank account in your own name while your ex is self-employed and hard to trace, the automated system will find you first, even if the debt is 100% your ex's doing.
If you live in one of the nine community property states, including California, Texas, and Arizona, there is an extra layer. State law can attribute half of your ex's income during the marriage to you, even on separate returns. Those cases run under Section 66, and community property tax relief has its own rules worth reading if that is your state.
“When you file a joint tax return with your spouse, regardless of how you file, you are both responsible for the tax and any interest or penalty due.”
— Innocent spouse relief (IRS.gov)
What happens if you ignore a joint tax debt after divorce?
A joint tax debt escalates against both ex-spouses on the same automated track. The IRS levies whichever of you is easier to collect from. Ignoring it because "the decree says it's theirs" is the single most expensive mistake divorced taxpayers make.
Watch for a hidden trap first: IRS notices may still be going to the old marital address. If your ex kept the house, the CP14 and every reminder after it may be landing in their mailbox while the enforcement clock runs against you. File Form 8822 to update your address the day you finish reading this.
Here is the sequence when a joint balance goes unaddressed:
- Refund offsets. Every federal refund either of you is owed gets seized and applied to the joint balance, year after year, until it is paid. For many divorced taxpayers, a vanished refund is the first sign the debt exists. If that is how you found out, see ex-spouse's tax debt took my refund.
- CP14, then CP501/CP503 reminders. Bills, sent to the last address the IRS has for each spouse. The balance grows monthly with interest and the failure-to-pay penalty.
- CP504, the intent to levy your state refund. The IRS can now take your state tax refund. A federal tax lien against each of you becomes a live possibility.
- LT11 / Letter 1058, the final notice. This starts a 30-day clock and your Collection Due Process rights. After it passes, the IRS can levy wages and bank accounts.
- Levy. A wage levy is continuous. It takes a slice of every paycheck until released. A bank levy freezes funds with a 21-day hold before the money leaves.
As a renter, you have no house for a lien to sit on, so enforcement against you comes straight at your paycheck and bank account, the two things you live on. You can estimate how much of your pay a levy could reach with our IRS Wage Garnishment Calculator, and if one is already in motion, read how to stop IRS wage garnishment while you work the relief path below.
Red flags that mean the clock is already running against you:
- A federal refund you expected never arrived, with no explanation.
- Your ex kept the marital home and you have not filed Form 8822.
- An LT11 or Letter 1058 is in hand and the 30-day window has started.
- Your bank has frozen funds, which means the 21-day hold is counting down.
- The joint-return year with the problem is more than a year old and you have not yet located the IRS's first collection activity against you.
The IRS is chasing you for your ex's share?
If a final levy notice has arrived, the 30-day window to request a hearing is running right now, and innocent spouse relief has its own two-year clock. Get your notice and decree reviewed free by an experienced tax professional before either window closes.
What are your options when an ex's tax debt lands on you?
Which of the three relief paths covers your situation?
The IRS has three distinct relief programs under Section 6015 that can move a joint debt off your shoulders, plus payment options for any share that is fairly yours. Which one fits turns on a distinction most people have never heard of. Is the balance an understatement (tax the IRS added later because income was hidden or deductions were bogus) or an underpayment (an accurate return the two of you never paid)?
| Option | What it covers | Key eligibility |
|---|---|---|
| Innocent spouse relief — §6015(b) | Extra tax from your ex's errors (understatements only) | Joint return; you didn't know and had no reason to know about the error; holding you liable would be unfair |
| Separation of liability — §6015(c) | Splits an understatement by whose income or deduction caused it | Divorced, legally separated, or living apart 12+ months; elect within 2 years of first collection activity |
| Equitable relief — §6015(f) | Understatements and unpaid balances | Fairness factors: knowledge, who benefited, what the decree says, hardship, abuse or financial control |
| Injured spouse — Form 8379 | Your share of a joint refund taken for a spouse's separate debt | Refund offset to a debt that was never yours; filed per affected year |
| Payment plan | Any share of the debt that's genuinely yours | Under $10,000 fits the guaranteed installment agreement; under $50,000 can go up to 72 months online |
| CNC or Offer in Compromise | Debt you truly cannot pay | Means-tested on your income, expenses, and assets — post-divorce, only your finances count |
Separation of liability is the divorced taxpayer's purpose-built tool. Being divorced, legally separated, or living apart for 12 months or more is an eligibility requirement. It works by allocation: the IRS splits the understatement according to whose income or deduction caused it. If the entire problem came from your ex's unreported side income, your allocated share can be zero. The full mechanics are in our guide to separation of liability. Note its two limits. It covers understatements only, and it must be elected within the two-year window.
Classic innocent spouse relief can remove your liability entirely rather than splitting it, but the bar is higher. You must show you did not know and had no reason to know about the error when you signed. The IRS looks at lifestyle. If the hidden income paid for vacations you took, "I didn't know" gets hard to sustain.
Equitable relief is the catch-all, and the only path when the return was accurate but the bill went unpaid. This is where your decree finally matters to the IRS. A decree assigning the debt to your ex is a fairness factor in your favor, alongside who kept the money, your current hardship, and any history of financial control or abuse in the marriage.
All three are requested on one form. Our Form 8857 walkthrough covers it line by line. One feature matters most: filing it generally suspends IRS collection against you while the request is decided, which can be the fastest lever to stop a pending levy.
Keep injured spouse Form 8379 separate in your mind. That form recovers your slice of a refund taken for a debt that was never yours (a current spouse's old child support or student loans, for example). Liability on a joint balance itself is handled by the Section 6015 paths above.
Finally, for whatever share is fairly yours, the ordinary resolution menu applies: payment plans, hardship status, and settlement. The full playbook is in how to settle tax debt yourself, and if you are weighing a settlement while splitting liability with an ex, OIC divorced spouse covers that specific intersection.
How does a $7,400 joint debt play out after divorce?
Say you owe $7,400, hypothetically. Your last joint return got a CP2000 because your ex never reported $21,000 of freelance income. The marriage ended before the bill arrived. You rent, earn $52,000 at a W-2 job, and an LT11 final levy notice just showed up at your apartment. Here is the math on your choices:
- Separation of liability: the entire $21,000 understatement traces to your ex's income, so your allocated share of the $7,400 is $0. You file Form 8857 within the two-year window, collection against you generally pauses, and the IRS pursues your ex for the full amount.
- If it were an unpaid balance instead, say you both reported the income correctly but never sent the $7,400, separation of liability would not apply. Your path would be equitable relief, where the decree ordering your ex to pay and the fact that the freelance money never touched your account both weigh in your favor.
- The payment-plan backstop: if relief fails or takes time, $7,400 on a 72-month online plan runs about $103/month before interest and the 0.5%-per-month failure-to-pay penalty, which keep accruing. Because the balance is under $10,000, you also fit the installment agreement for balances under $10,000. A plan in place stops levies immediately, even while your 8857 is pending.
- The 30-day move: that LT11 gives you 30 days to request a Collection Due Process hearing on Form 12153, and innocent spouse relief is a legitimate issue to raise in that hearing. Filing it stops the levy while the hearing runs.
The order matters. Hearing request or payment plan first to freeze enforcement, relief claim second to move the debt, family court third to make your ex reimburse anything you paid along the way.
How should you respond, step by step?
Before the steps, know your clocks. Each one controls a different right:
| Clock | Window | What you lose if it passes |
|---|---|---|
| Form 8857 — §6015(b) and (c) | Generally 2 years from the IRS's first collection activity against you | Innocent spouse relief and separation of liability — the two strongest paths |
| Equitable relief — §6015(f) | Open while the IRS can still collect (generally 10 years from assessment) | All §6015 relief once the collection statute expires |
| LT11 / Letter 1058 | 30 days from the notice date | Your Collection Due Process hearing (Form 12153) before levy |
| Bank levy hold | 21 days after the bank freezes funds | The money leaves your account for the IRS |
| Collection statute (CSED) | 10 years from assessment, pausable by appeals, an OIC, or bankruptcy | Nothing. This clock runs in your favor |
Responding to a post-divorce joint tax debt, step by step:
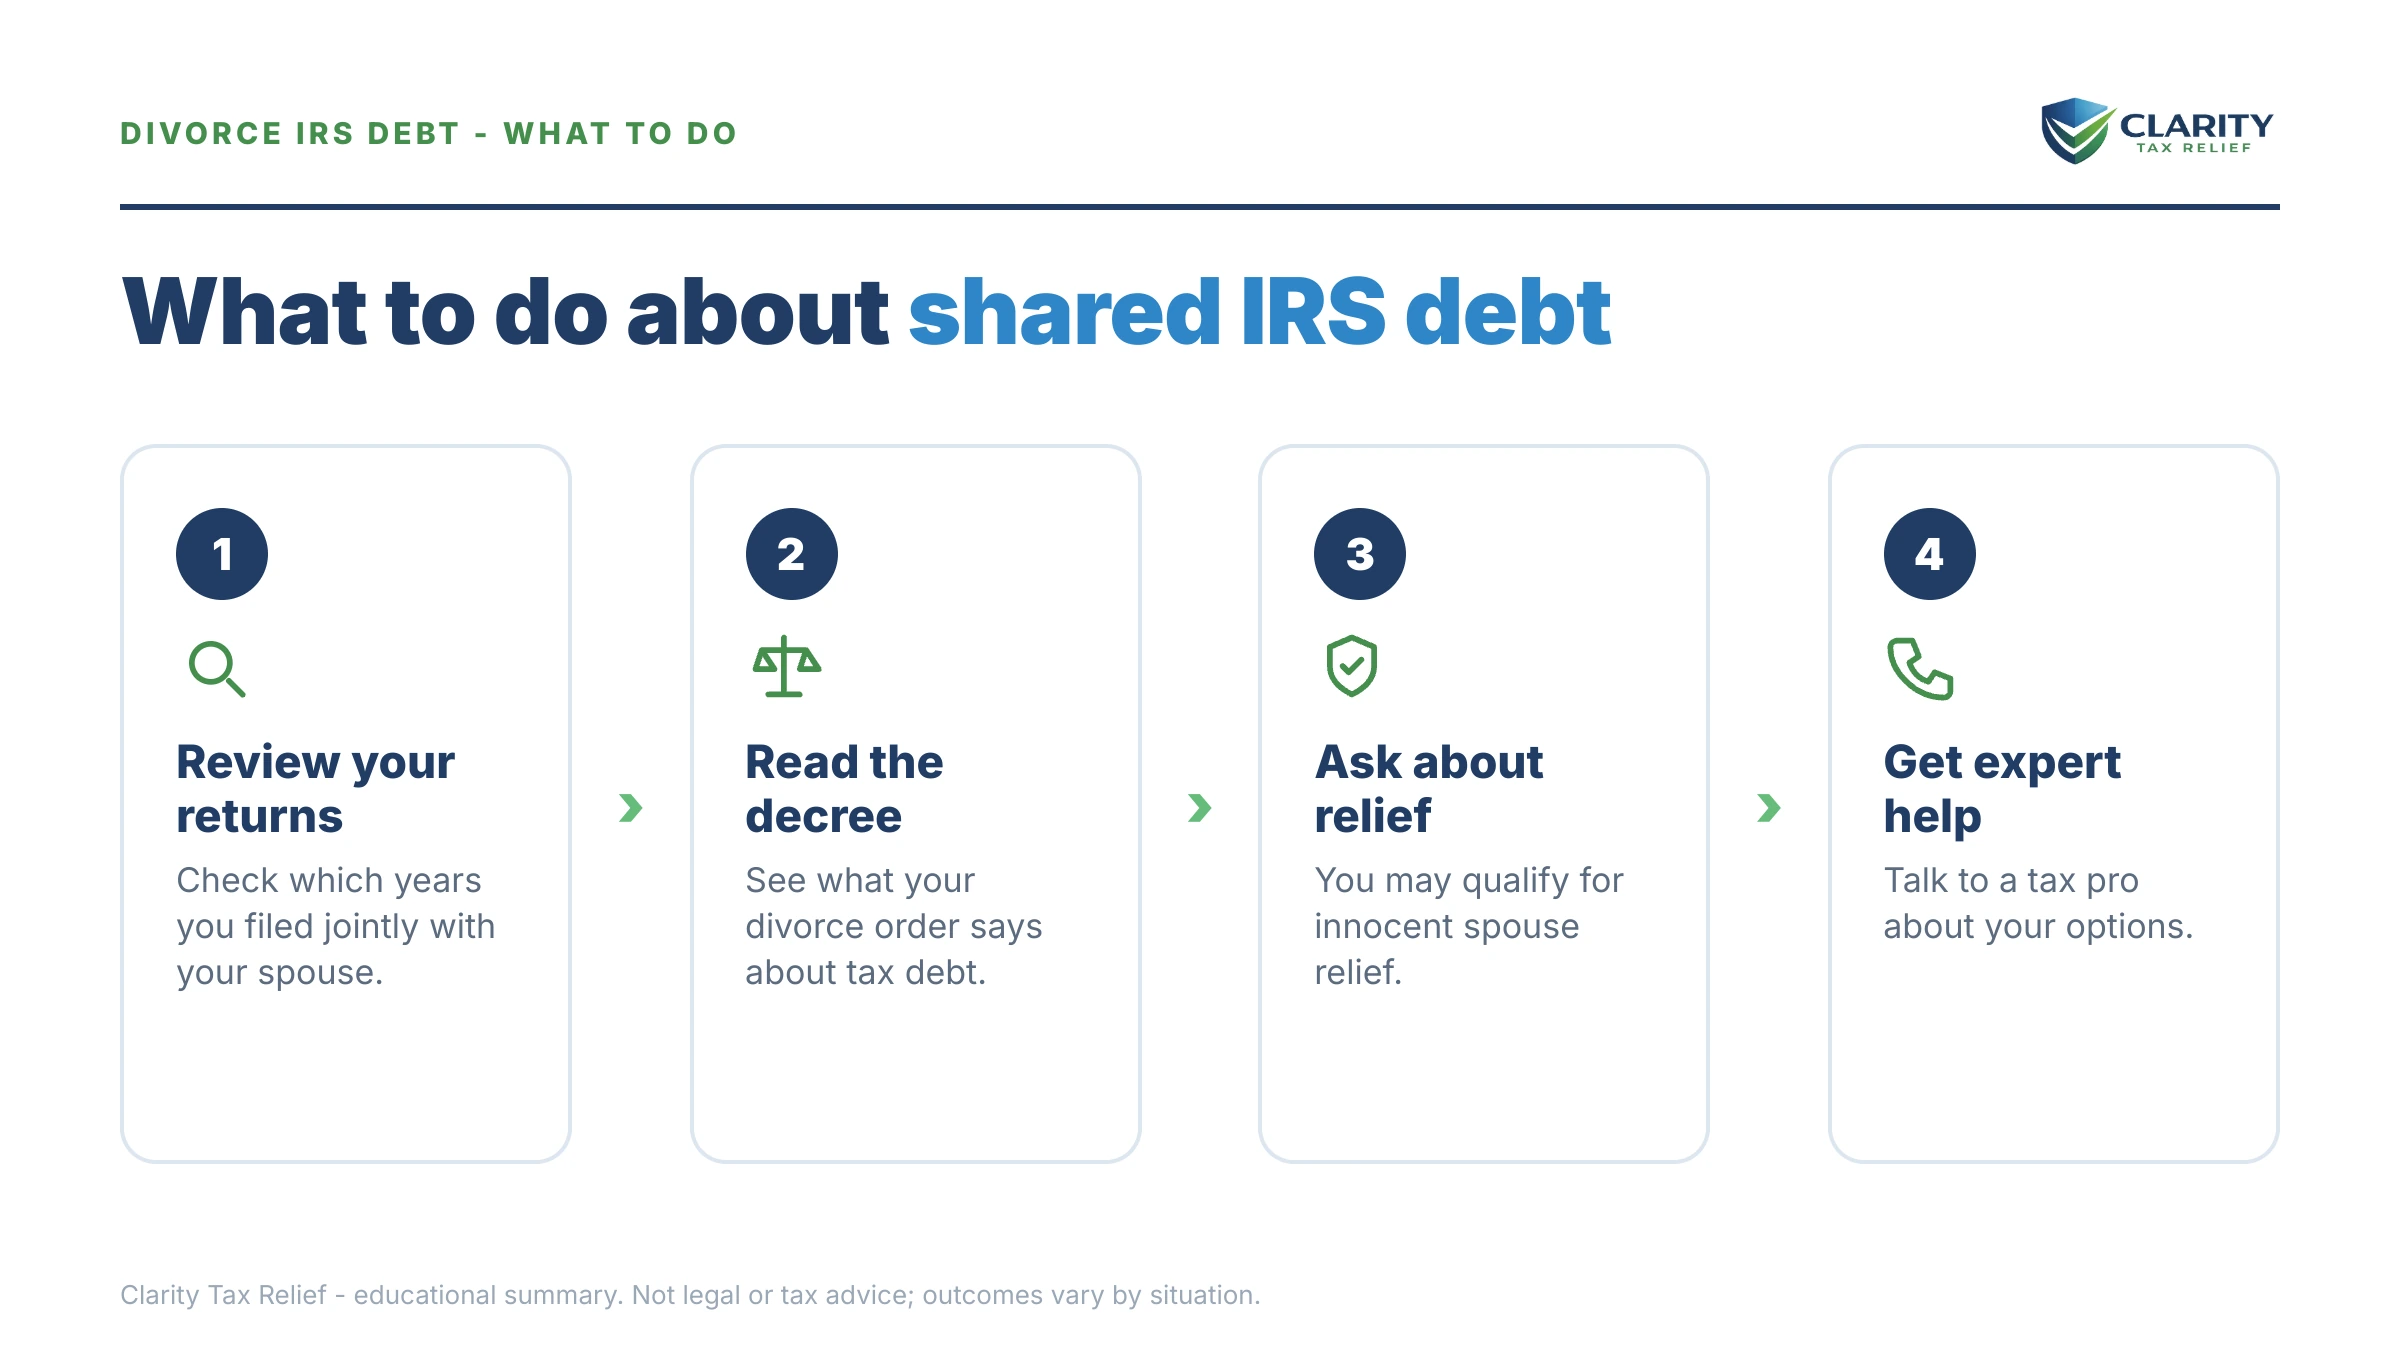
- Identify the source of the debt. Pull your IRS account transcripts and confirm two things: was the return for that year filed jointly, and is the balance an understatement (tax the IRS added later) or an unpaid balance you both reported? Those two answers decide which relief path applies.
- Find your two-year clock. Locate the IRS's first collection activity against you, often a refund offset or a levy notice. Innocent spouse relief and separation of liability must generally be requested within two years of that date.
- File Form 8857 if the debt belongs to your ex. One form covers all three relief types under Section 6015, and the IRS considers every path you might qualify for. Filing generally pauses collection against you while your request is reviewed.
- Protect your paycheck in the meantime. If you are holding an LT11 or Letter 1058, request a Collection Due Process hearing with Form 12153 within 30 days. You can raise innocent spouse relief as an issue in that hearing. A payment plan is a valid backstop that stops levies while relief is decided.
- Enforce the decree in family court separately. If your decree orders your ex to pay and they refuse, ask your family law attorney about a contempt or enforcement action. That runs on a separate track from the IRS. Pursue both at once.
When can you handle this yourself, and when does help change the outcome?
Plenty of post-divorce tax debts can be resolved without hiring anyone. You can likely handle it yourself if the joint balance is small and you agree it is fairly half yours, if you can pay it within 180 days, if the debt is clearly from your ex's separate return (confirm it on your transcript, then correct the IRS with documentation), or if you just need a straightforward payment plan set up online. Free options exist too. Low Income Taxpayer Clinics regularly take innocent spouse cases, and our guide to free help with IRS tax debt maps every no-cost route.
Experienced help changes outcomes in four specific situations:
- A levy is already in motion against your wages or bank account.
- Your 8857 case turns on proving what you knew, which means assembling bank records, lifestyle evidence, and sometimes documentation of financial abuse.
- You are in a community property state where Section 66 and Section 6015 interact.
- Your ex is contesting your claim, since the IRS must let them argue against you.
Innocent spouse cases are won or lost on the evidence file, and building it right the first time matters. A denial can be appealed, but that is a longer, harder road.
What do the terms on your IRS notices mean?
- Joint and several liability: each spouse on a joint return owes 100% of the debt. The IRS can collect the whole amount from either person.
- Understatement vs. underpayment: an understatement is tax the IRS added after the fact (hidden income, bad deductions). An underpayment is an accurate return you did not pay. Different relief rules apply to each.
- First collection activity: the event, often a refund offset or levy notice, that starts your two-year window to request §6015(b) or (c) relief.
- CDP (Collection Due Process): your right, after a final levy notice, to a hearing before the IRS takes your wages or bank account. Requested on Form 12153 within 30 days.
- CSED: the Collection Statute Expiration Date, generally 10 years after assessment. It is the IRS's legal deadline to collect, though appeals, offers, and bankruptcy pause it.
- Injured vs. innocent spouse: injured spouse (Form 8379) recovers your refund taken for a debt that is not yours. Innocent spouse (Form 8857) removes your liability for a joint debt itself.
Bottom line
A divorce decree settles matters between you and your ex. It does not bind the IRS, which can collect 100% of a joint-return balance from either of you. The way to move the debt is through Form 8857 and the three Section 6015 relief paths, and the two strongest of those generally close 2 years after the IRS first takes collection action against you.
Work the clocks in order. Freeze enforcement first with a Form 12153 hearing request or a payment plan, file for relief second, and take your ex back to family court for reimbursement third. File Form 8822 today if notices may still be going to the old address.
Divorce and IRS debt: your questions, answered
Is my ex responsible for our tax debt after divorce?
Legally, you are both responsible if the debt comes from a jointly filed return — the IRS can collect the full amount from either of you. A divorce decree assigning the debt to your ex binds your ex in family court, not the IRS. To shift the liability with the IRS itself, you need innocent spouse relief, separation of liability, or equitable relief under IRC Section 6015.
Can the IRS garnish my wages for my ex-husband's tax debt?
Yes, if the debt is from a joint return — joint and several liability means your wages, bank account, and future refunds are all fair game for 100% of the balance. If the debt is from a return your ex filed separately, the IRS cannot levy your wages for it. Filing Form 8857 generally pauses collection against you while the IRS reviews your claim.
Does a divorce decree protect me from IRS debt?
No — the IRS is not a party to your divorce and is not bound by the decree. If your ex ignores a decree ordering them to pay, your remedy is a contempt or enforcement action in family court, while the IRS keeps collecting from you. The decree can still help you: it is one of the fairness factors the IRS weighs in an equitable relief claim.
How long do I have to request innocent spouse relief after divorce?
Generally two years from the IRS's first collection activity against you for classic innocent spouse relief and separation of liability. Equitable relief stays open longer — as long as the IRS can still legally collect the debt, which is generally 10 years from assessment. Don't wait: the two relief types with the strongest track record are the ones with the two-year window.
What if the IRS took my refund for my ex's separate tax debt?
That calls for injured spouse relief, not innocent spouse relief. You file Form 8379 to recover your share of a refund the IRS applied to a debt that was never yours. It typically applies when you filed jointly with a current spouse whose old debts swallowed the refund. If you are already divorced and filing single, your refund can only be offset for debts you actually owe.
Who pays IRS debt after divorce in a community property state?
Community property rules can make you liable for tax on half of your ex's income earned during the marriage, even on separately filed returns. The nine community property states include California, Texas, and Arizona. IRC Section 66 offers its own relief when your spouse controlled the income and you didn't know about it, separate from the Section 6015 rules.
Can innocent spouse relief cover a balance we just never paid?
Usually only through equitable relief. Classic innocent spouse relief and separation of liability apply to understatements — tax the IRS added later because income was hidden or deductions were false. If the return was accurate but the bill simply went unpaid, equitable relief under Section 6015(f) is the path. The IRS weighs who had the money and who the decree ordered to pay.
What happens if my ex files for innocent spouse relief against me?
The IRS is required to notify you and let you participate. You can submit evidence showing your ex knew about the income or benefited from the unpaid tax. If relief is granted, the full remaining balance stays with you. Take the notice seriously and respond by its deadline; silence makes it easier for the IRS to allocate the debt entirely to your side.
The IRS's own overviews are worth bookmarking as you go: the official innocent spouse relief page, the Form 8857 page, and — if your case stalls or a levy is causing hardship — the Taxpayer Advocate Service.
Your next 24 hours
- Find the tax year and amount on the most recent IRS notice, and check whether the return for that year was filed jointly. That one fact determines everything else.
- Gather four documents: the IRS notice, your divorce decree, that year's tax return, and proof of your own income for that year.
- Get a free case review at the 2-minute form or (888) 825-7779. If a final levy notice has arrived, the 30-day hearing window is already running. Your two-year Form 8857 clock may have started before you knew the debt existed.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.