
IRS Forms
IRS Form 982: How the Insolvency Exclusion Removes Tax on Canceled 1099-C Debt (2026)
The short answer: IRS Form 982 attaches to your return to exclude canceled 1099-C debt from income. The insolvency exclusion covers up to the amount your debts exceeded your assets' fair market value right before the cancellation. Check box 1b and enter the amount on line 2. Clarity Tax Relief builds the insolvency worksheet as of the moment before the cancellation, the way the form requires.
This guide covers why canceled debt is taxed, how the IRS Form 982 insolvency math works with a worked example, what happens if a 1099-C goes unanswered, each line of the form, which kinds of debt the exclusion fits, and the deadlines for claiming it. Form revisions, limits and the Publication 4681 rules below were checked against irs.gov on November 4, 2026.
You settled a debt, or a creditor gave up on it, and months later a 1099-C arrived saying the forgiven balance is now taxable income. It feels like being billed for drowning. But Congress built an exit for exactly this situation: if you were broke on paper when the debt was canceled, you may not owe tax on it at all.
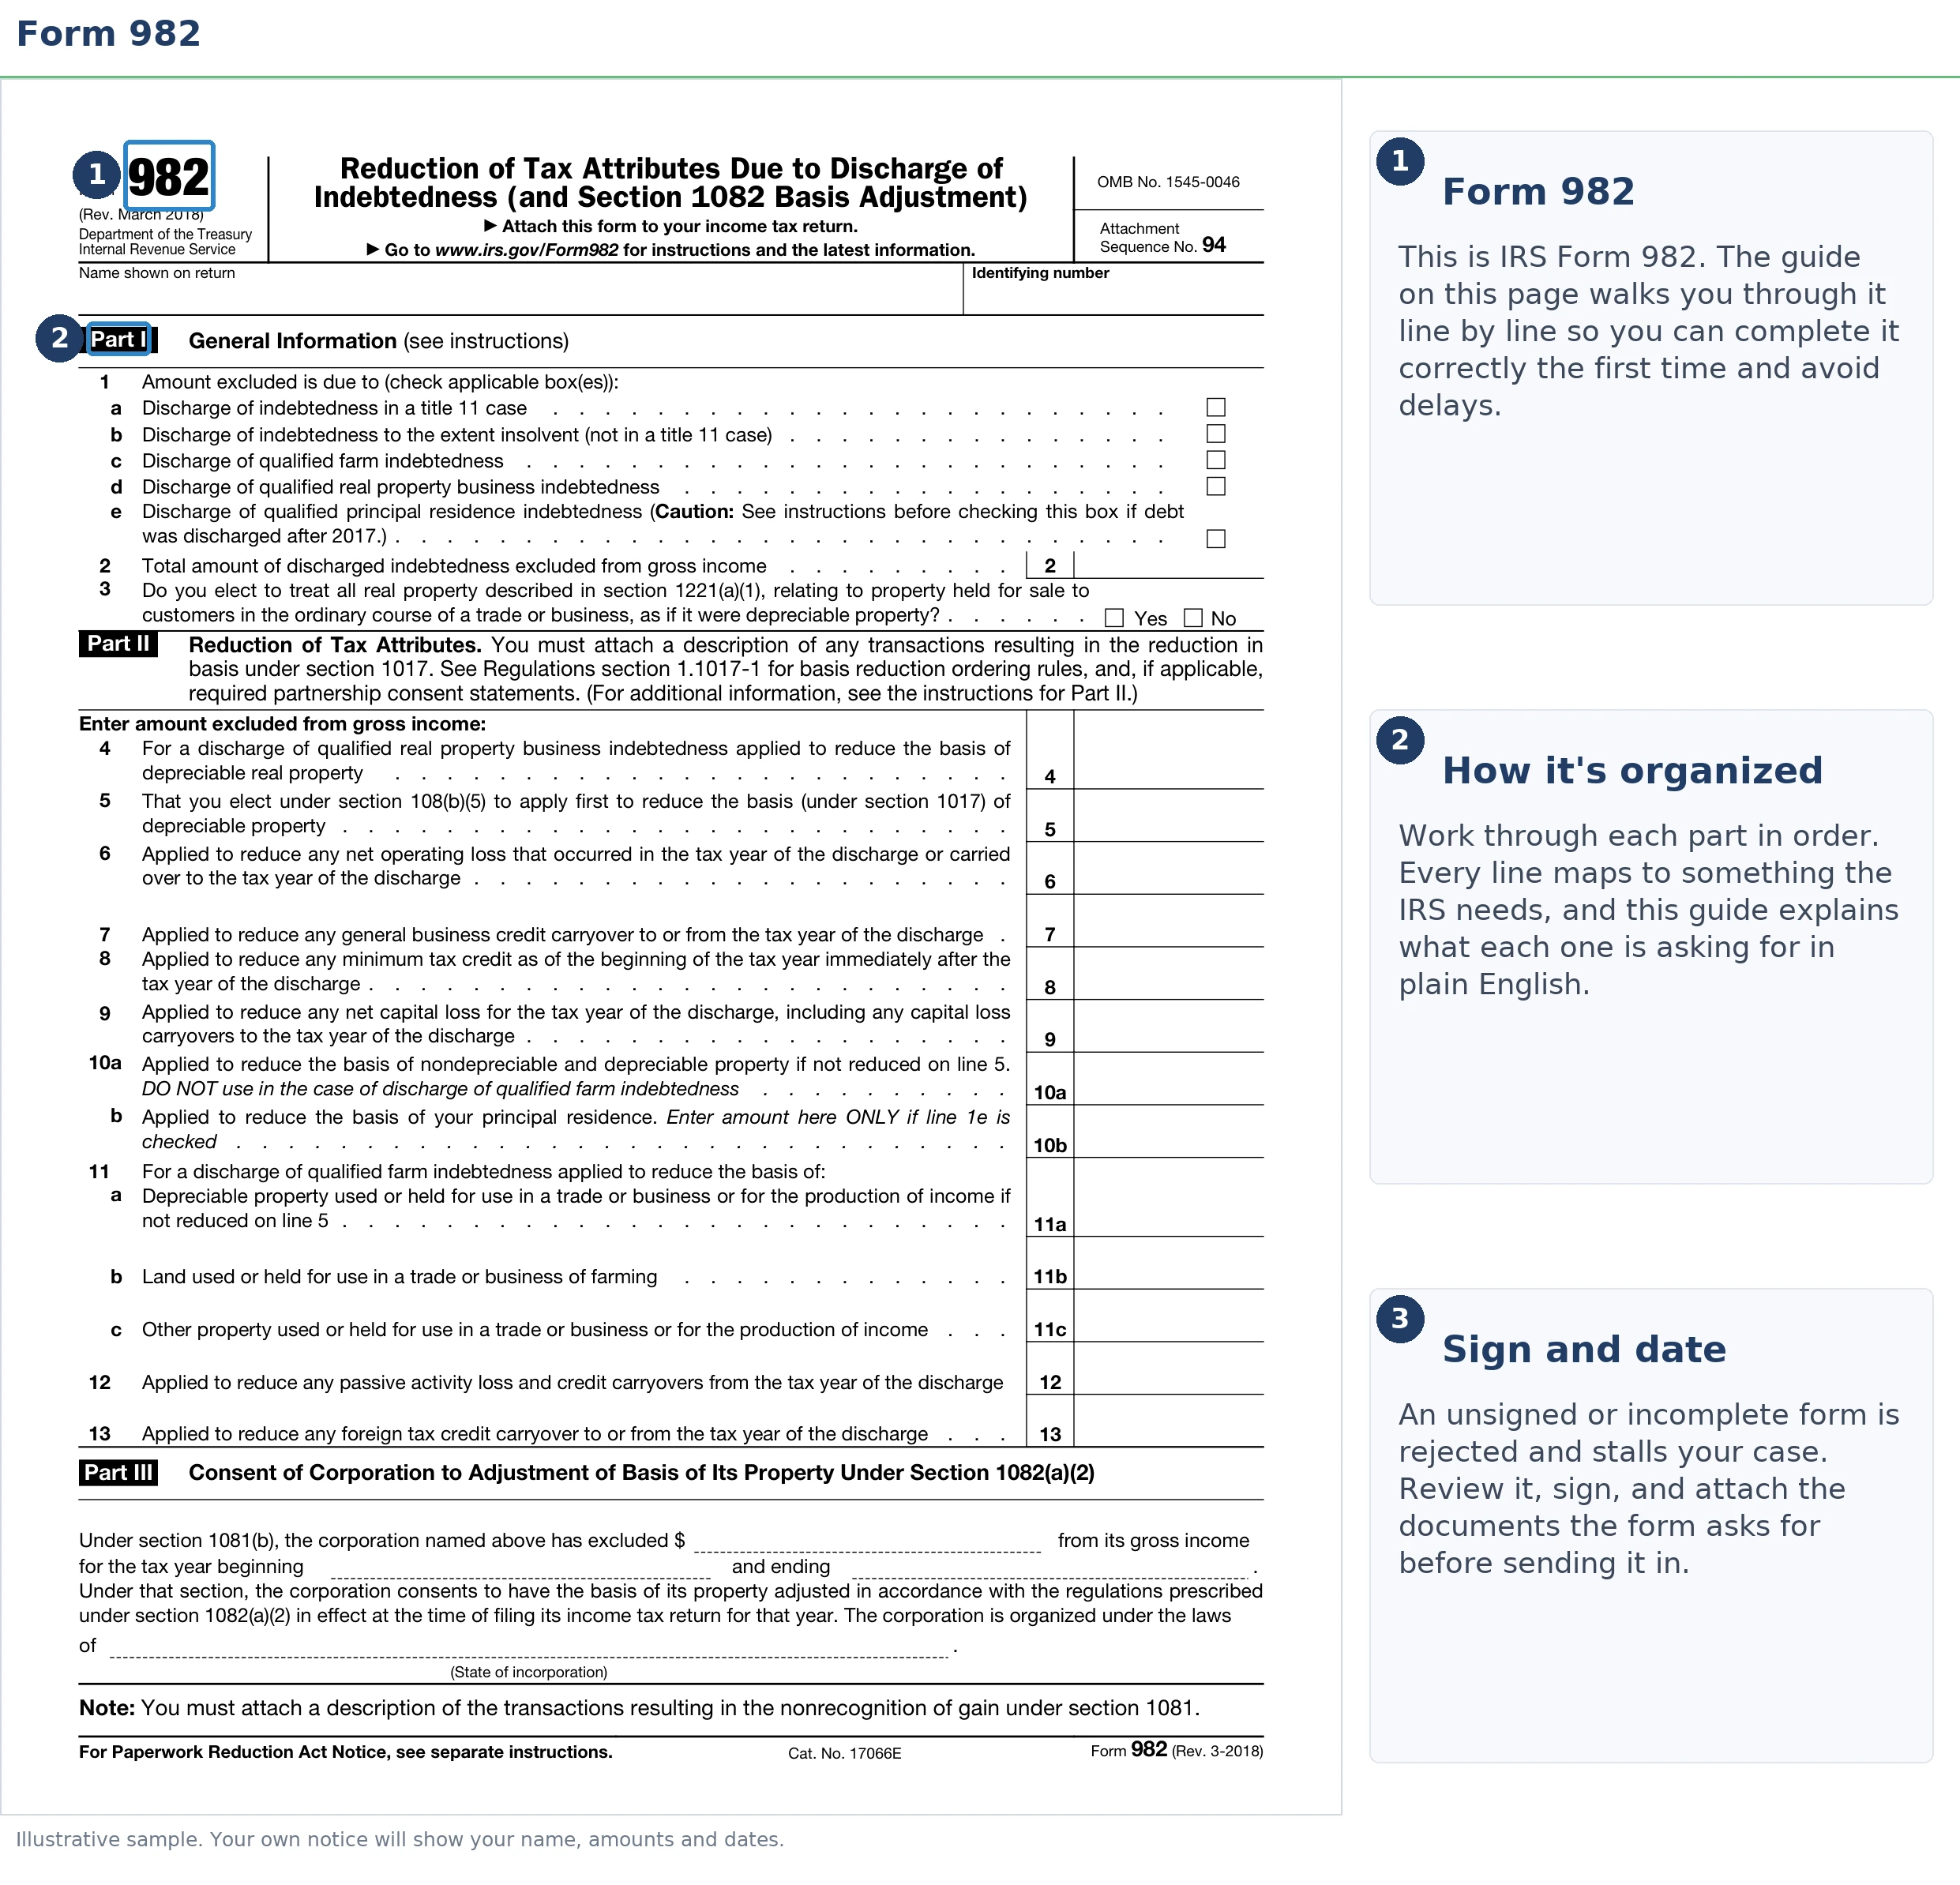
The entire claim comes down to three entries on a one-page form plus a worksheet you keep in your records. The image below shows exactly what Form 982 looks like and where the insolvency exclusion lives on it, so you can see how little of the form actually applies to you.
What is IRS Form 982?
Form 982 is the IRS form you attach to your return to exclude canceled debt from income under Internal Revenue Code section 108. Its full name is Reduction of Tax Attributes Due to Discharge of Indebtedness (and Section 1082 Basis Adjustment). Part I says which exclusion you qualify for and how much you are excluding. Part II records the price of that exclusion: the "tax attributes" (loss carryovers, credits, property basis) you give up in exchange. The current form is the March 2018 revision, and its instructions were last revised in December 2021, both confirmed on IRS.gov as of November 4, 2026, with no recent developments posted.
Five exclusions live on the form: bankruptcy (box 1a), insolvency (box 1b), qualified farm indebtedness (box 1c), qualified real property business indebtedness (box 1d), and qualified principal residence indebtedness (box 1e). Insolvency is the one most individuals use, and the rest of this guide is built around it.
⏱ Your deadline: Form 982 must be attached to your federal return for the year shown in box 1 of the 1099-C, typically due April 15 of the following year. Already filed without it? You generally have 3 years from the date you filed to claim the exclusion on Form 1040-X and recover tax you overpaid.
Why does canceled debt count as income?
Clarity Tax Relief starts every 1099-C conversation with this rule. When a creditor cancels $600 or more of your debt, tax law treats the forgiven amount as income to you: money you borrowed, spent, and never repaid. Canceled debt is taxable by default. It stops being taxable only when one of the section 108 exclusions applies and you claim it on Form 982. The creditor reports it to the IRS on Form 1099-C, and the same copy that reaches your mailbox reaches the IRS matching computer.
Box 1 shows the cancellation date, which fixes the tax year. Box 2 shows the canceled amount, the number the IRS expects to see on your return. Box 3, canceled interest, is generally part of that total.
That's the general rule. The full income-shock picture, including when a 1099-C is issued in error, lives in our guide to 1099-C canceled debt taxes. This page covers the escape hatch: IRC §108's insolvency exclusion, claimed on Form 982, "Reduction of Tax Attributes Due to Discharge of Indebtedness." If you're still not sure why the IRS is writing to you at all, start with why did I get a letter from the IRS.
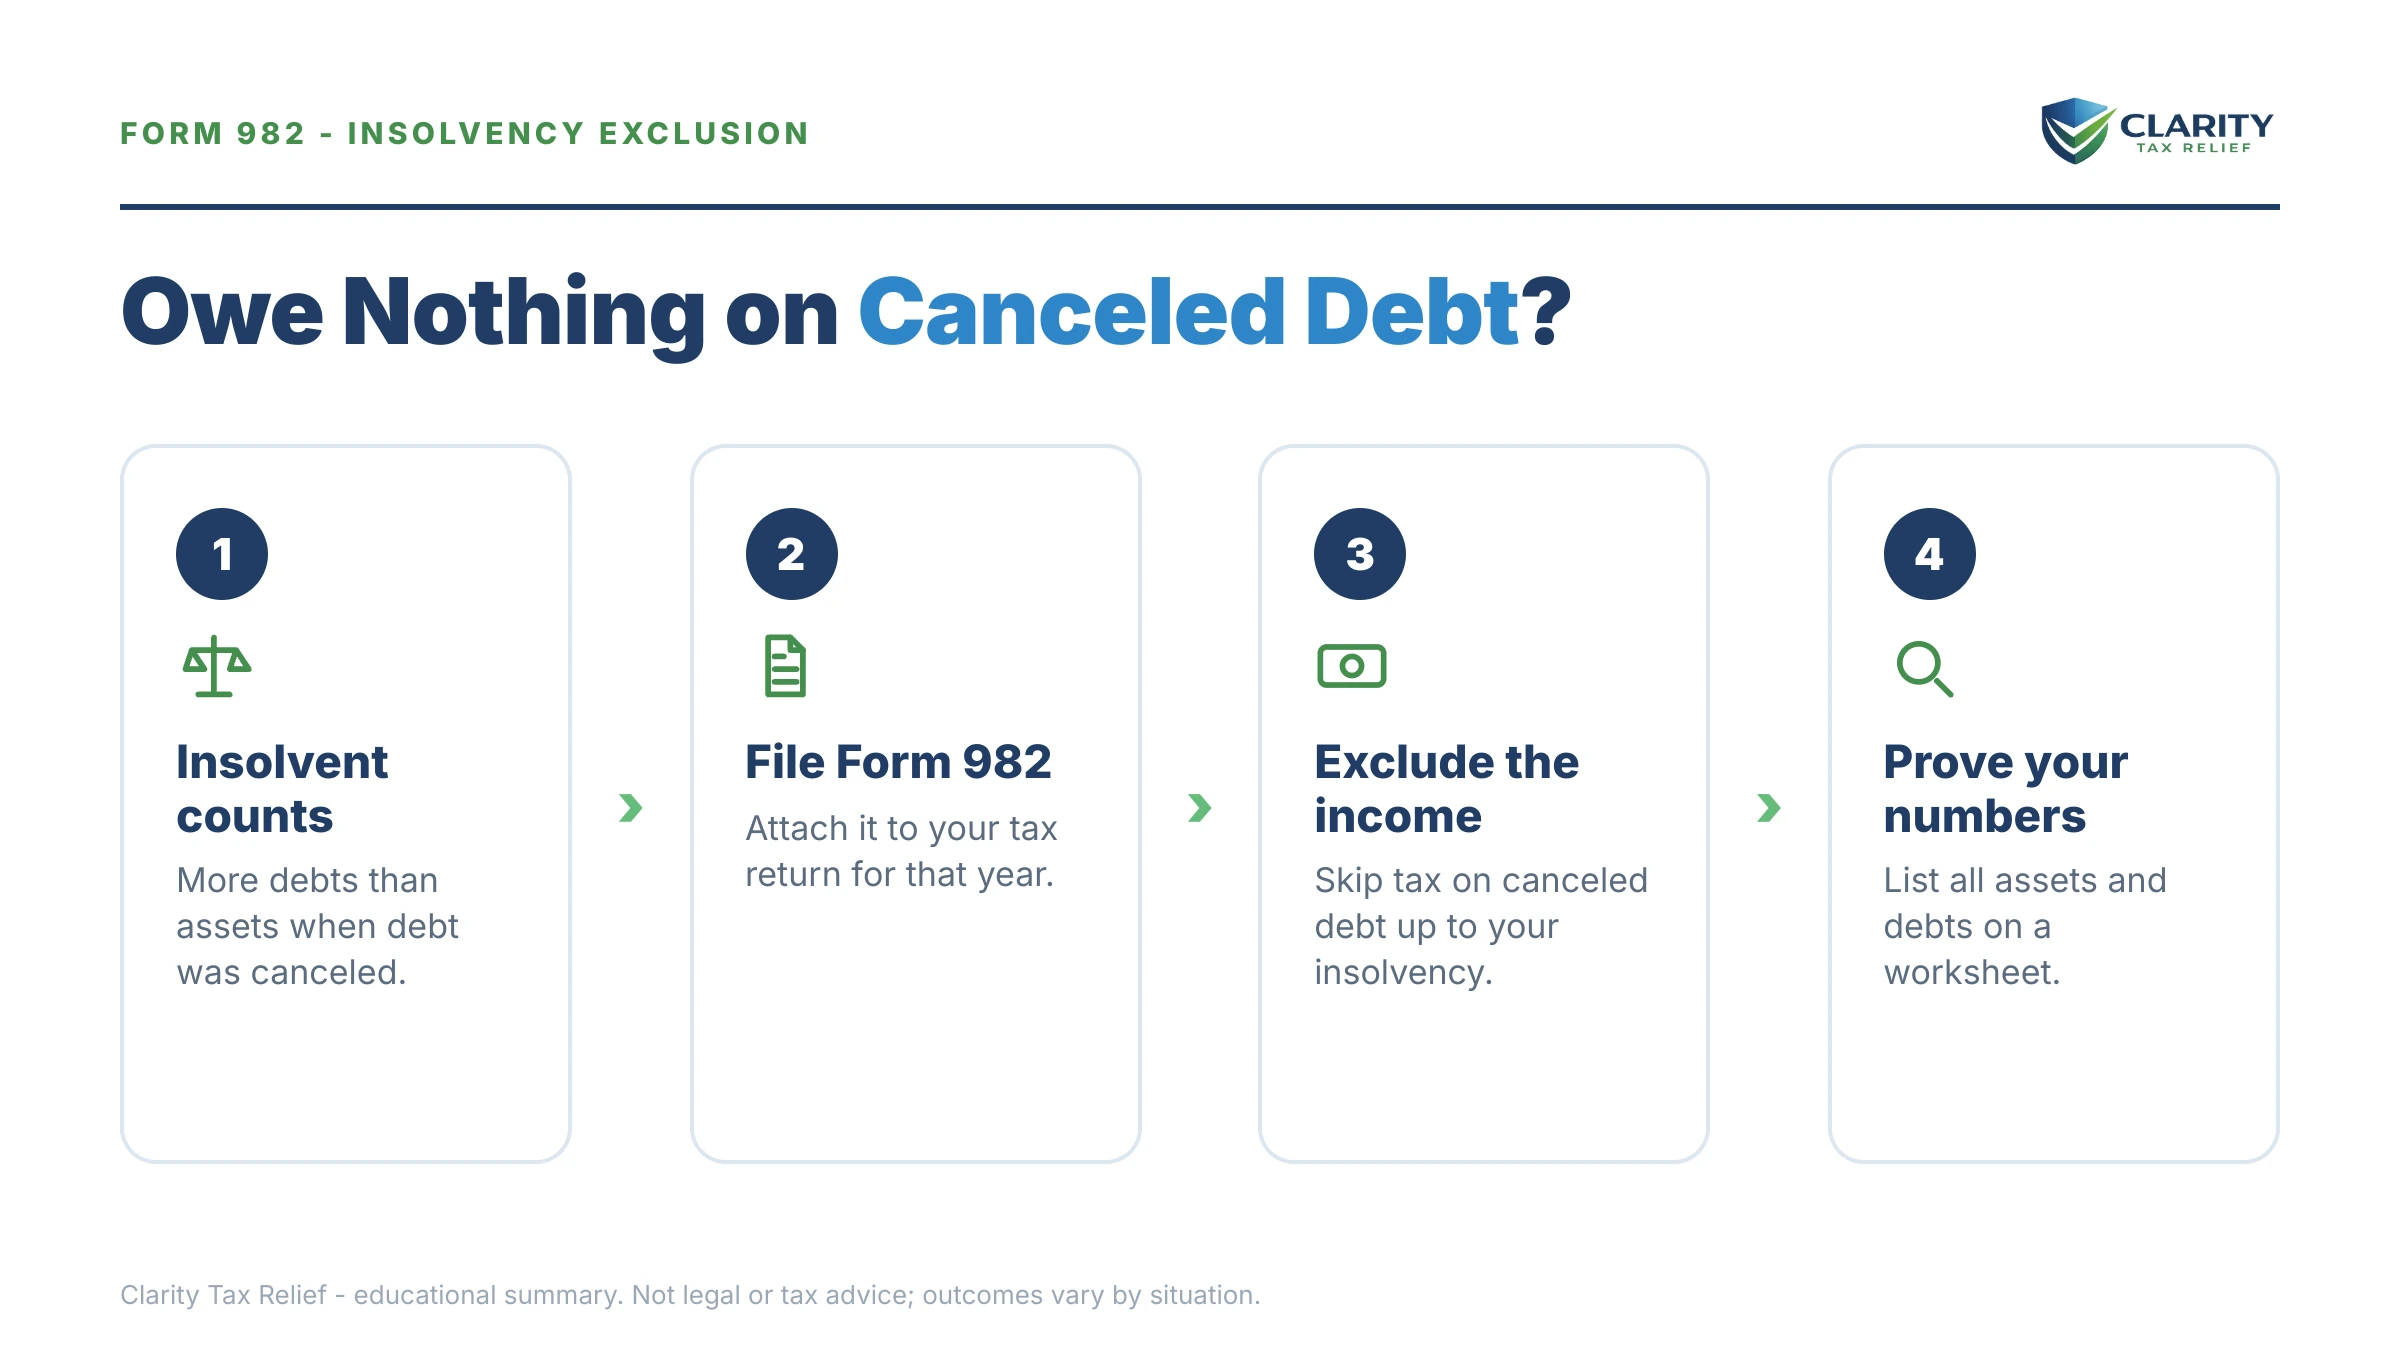
How does the Form 982 insolvency exclusion work?
You were insolvent, for Form 982 purposes, if your total liabilities exceeded the fair market value of your total assets immediately before the cancellation. Not the day you file. Not the day the 1099-C arrives. The day before the date printed in box 1.
“Insolvency is measured immediately before the cancellation, never on the day you file. Your liabilities have to exceed the fair market value of your assets at that moment,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
The exclusion is capped at your insolvency amount. If your debts topped your assets by $28,700, you can exclude up to $28,700 of canceled debt, even if the creditor forgave more. Anything above the cap is still taxable.
Two details trip up more filers than everything else combined:
- The debt being canceled counts as a liability. You measure the moment before discharge, so the balance about to be forgiven sits on your liability side of the ledger.
- Retirement accounts count as assets. 401(k)s, IRAs, and pension interests go in at full value, even though creditors can't reach them. Leaving them off is the most common way an insolvency claim collapses under IRS review.
| Assets (fair market value, day before cancellation) | Liabilities (balance owed, day before cancellation) |
|---|---|
| Cash, checking, and savings balances | The debt about to be canceled (yes, include it) |
| Vehicles and real estate at current market value, not purchase price | Credit cards, personal loans, and medical debt |
| 401(k), IRA, and pension interests, even though creditors can't reach them | Mortgages, home equity loans, and auto loans |
| Household goods, electronics, jewelry, and clothing | Student loans |
| Brokerage accounts, crypto, and business interests | Past-due bills, taxes owed, and court judgments |
A worked example: $92,700 in debts, $31,000 canceled
Say you're a W-2 employee, filing single, and a credit card issuer cancels $31,000 you stopped paying after a rough two years. The day before the cancellation, your balance sheet looked like this:
- Total liabilities: $92,700. The $31,000 card about to be canceled, a $38,500 car-and-personal-loan balance, $14,200 in other cards, and $9,000 in medical debt.
- Total assets: $64,000. A car worth $9,500, $1,200 in checking, $5,300 in household goods and electronics, and a $48,000 401(k) you must count even though no creditor could touch it.
| Worksheet line (day before the box 1 date) | Amount | Where it lands |
|---|---|---|
| Credit card about to be canceled | $31,000 | Part I, liabilities |
| Car loan and personal loan | $38,500 | Part I, liabilities |
| Other credit cards | $14,200 | Part I, liabilities |
| Medical bills | $9,000 | Part I, liabilities |
| Total liabilities | $92,700 | Worksheet Part I total |
| Vehicle, fair market value | $9,500 | Part II, assets |
| Checking account | $1,200 | Part II, assets |
| Household goods and electronics | $5,300 | Part II, assets |
| 401(k) balance | $48,000 | Part II, assets (counted in full) |
| Total assets | $64,000 | Worksheet Part II total |
| Insolvency (liabilities minus assets) | $28,700 | Your exclusion cap |
| Debt canceled (1099-C box 2) | $31,000 | Compared against the cap |
| Amount excluded | $28,700 | Form 982, box 1b checked, line 2 |
| Still taxable | $2,300 | Reported as other income on Form 1040 |
Insolvency = $92,700 − $64,000 = $28,700. You can exclude $28,700 of the $31,000. The remaining $2,300 is taxable income. In the 22% bracket, that is roughly $506 of tax instead of the roughly $6,820 you'd owe on the full $31,000. Form 982, box 1b, line 2 reading "$28,700," and a worksheet in your file is what stands between those two numbers.
The IRS runs a smaller version of the same math in Publication 4681 (the current edition is for 2025 returns): a $5,000 credit card debt is canceled, liabilities were $15,000 and assets were worth $7,000, so the taxpayer was insolvent by $8,000 and excludes the whole $5,000. Same arithmetic, different scale.
Notice what the 401(k) did to the math: without it, you'd be insolvent by $76,700 and the entire $31,000 would vanish from income. With it, the exclusion is partial. That's why you run the worksheet honestly the first time. An overstated exclusion unravels years later, with penalties attached.
What happens if you ignore a 1099-C?
The IRS already has its copy of your 1099-C, so leaving it off your return doesn't hide it. It just delays the bill and adds penalties. The underreporter sequence runs on autopilot:
- Computer matching. The Automated Underreporter program compares the creditor's 1099-C against your filed return, usually a year or more after you file, while interest quietly accrues from the original due date.
- CP2000 notice. The IRS proposes tax on the full box 2 amount, plus interest and often the 20% accuracy-related penalty. You typically get about 30 days to respond, and you can still claim insolvency at this stage by sending the worksheet and Form 982.
- CP3219A, the Notice of Deficiency. Ignore the CP2000 and the 90-day letter follows, starting your statutory 90-day window to petition Tax Court.
- Assessment and collection. Let the 90 days pass and the tax is assessed on debt you may never have owed tax on. The balance-due notice stream begins, ending in liens and levies if unpaid.
The bitter irony: many people who ignore a 1099-C were fully insolvent and would have owed nothing. The exclusion doesn't apply itself. It has to be claimed, and each stage of that sequence makes claiming it harder as bank statements age and asset values get fuzzy.
Holding a 1099-C and not sure the insolvency math works?
Send us the 1099-C and your rough numbers. An experienced tax professional will run the insolvency worksheet with you and tell you exactly how much you can exclude. Free, confidential, before you file or respond to any notice.
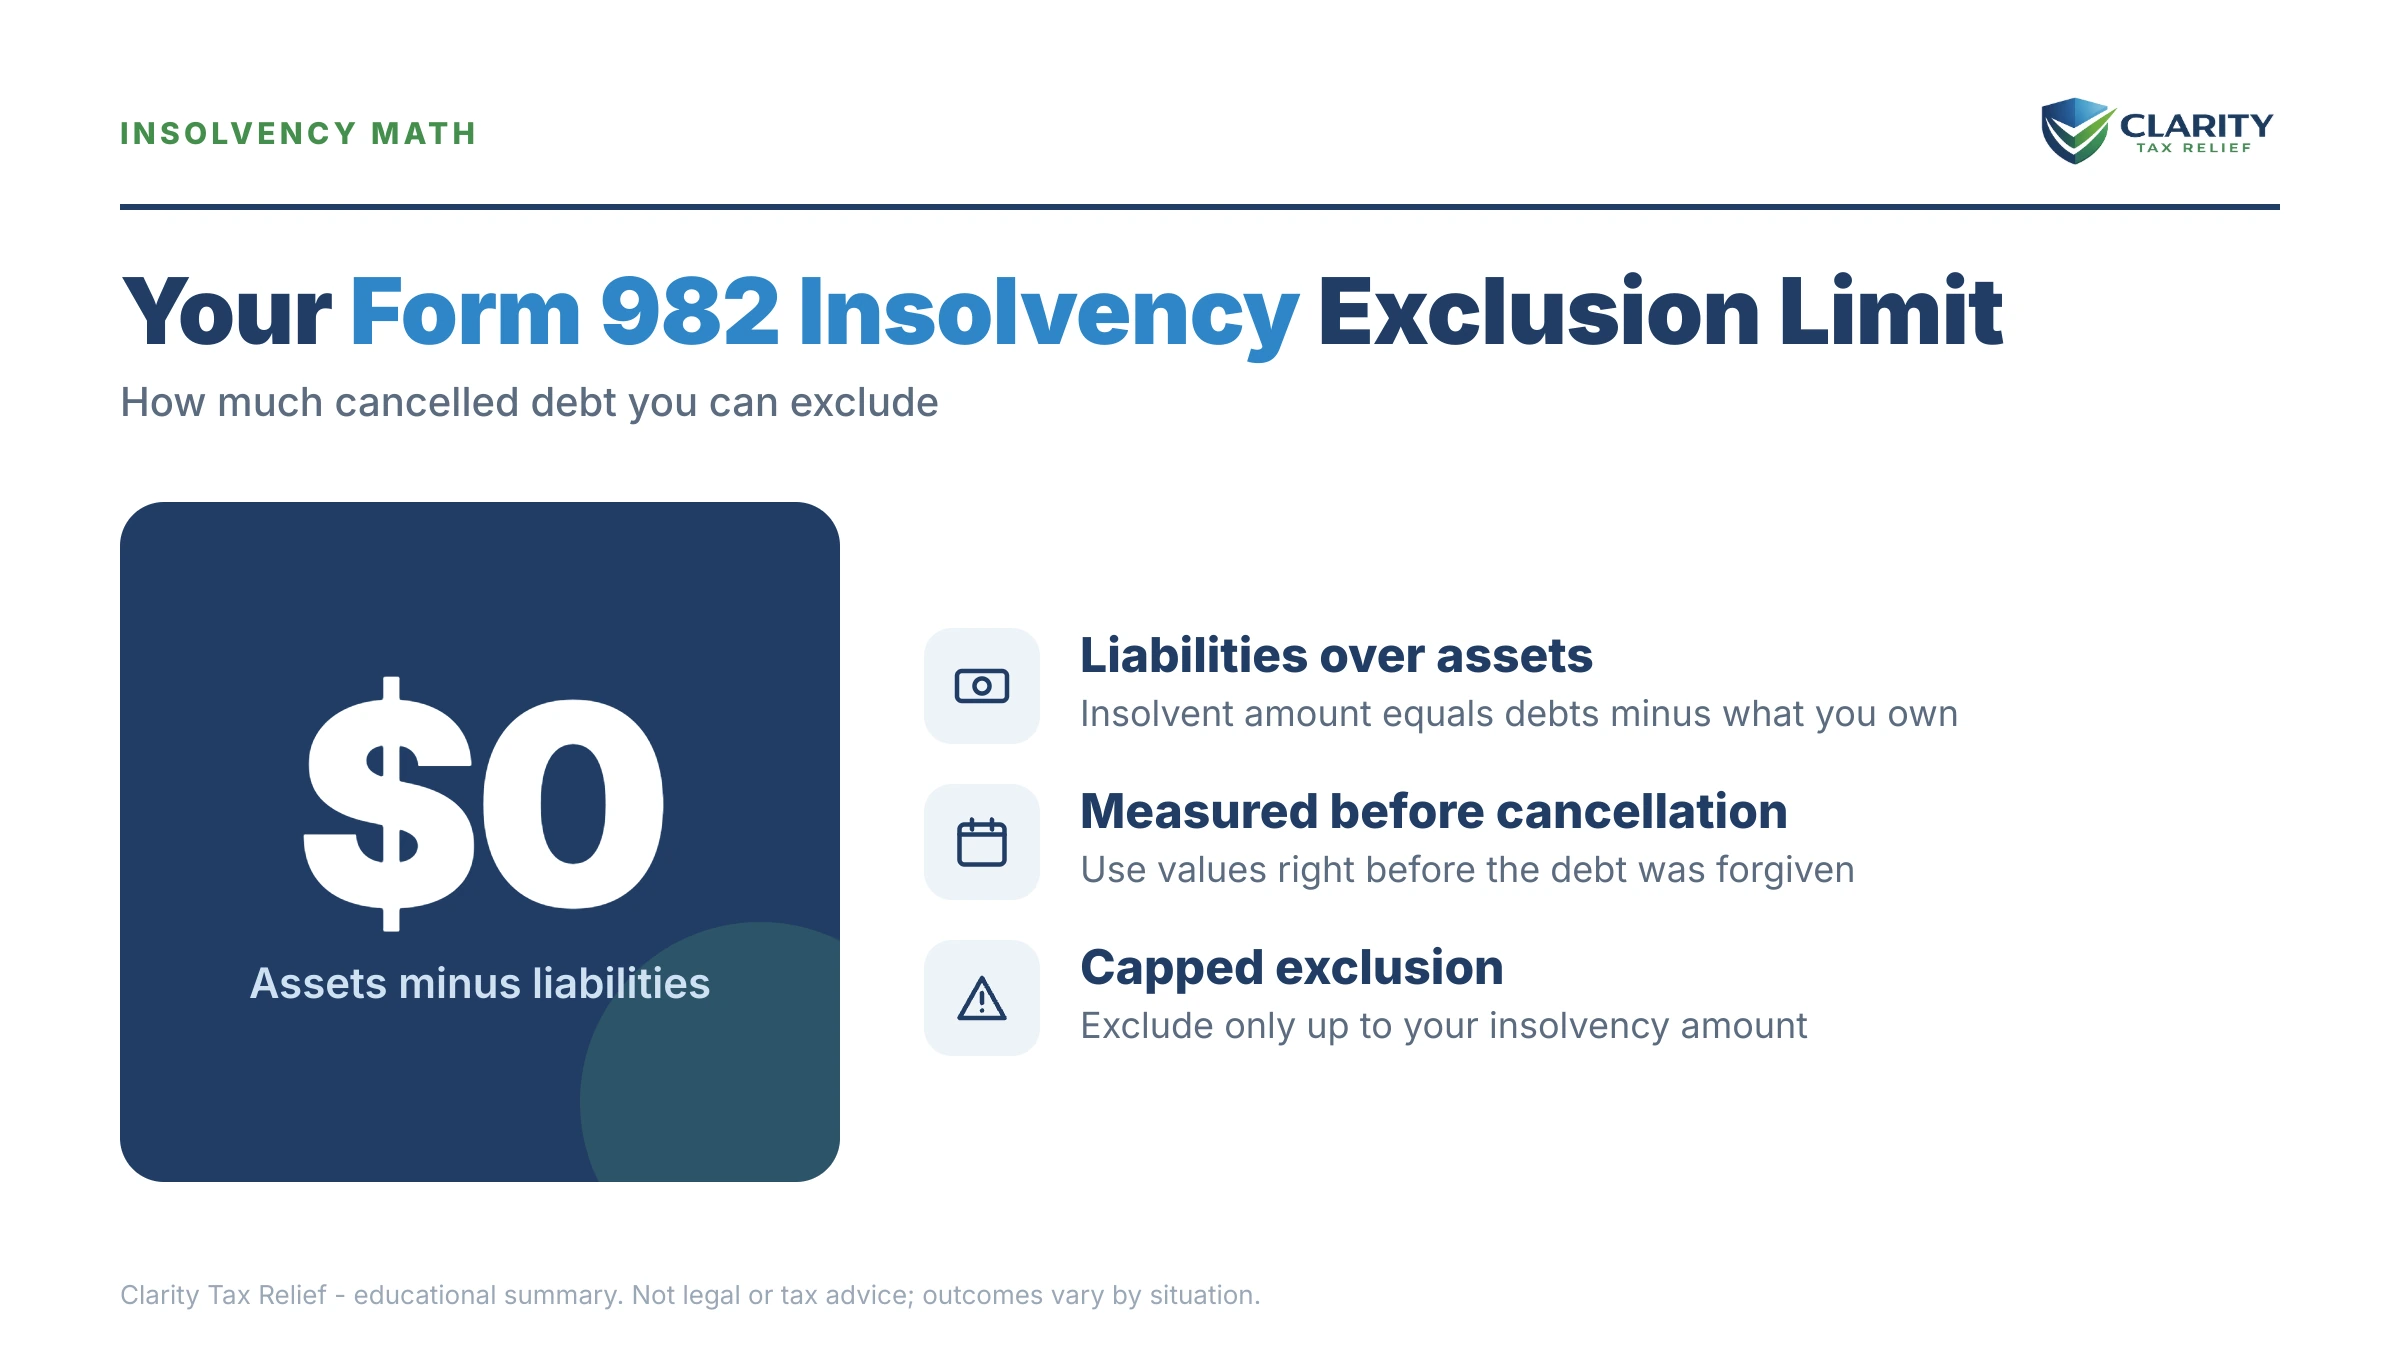
Is insolvency the right Form 982 option for you?
Clarity Tax Relief checks the other exclusions before reaching for insolvency. Insolvency is the most-used exclusion on Form 982, but it isn't the only one, and it isn't always the right one. Match your situation before you fill in a box:
| Your situation | The path | How much is excluded |
|---|---|---|
| Debts exceeded assets right before the cancellation | Insolvency exclusion, Form 982 box 1b | Up to your insolvency amount |
| Debt was discharged in a Title 11 bankruptcy case | Bankruptcy exclusion, Form 982 box 1a | 100% of the discharged debt, no insolvency math needed |
| Canceled mortgage debt on your main home | Qualified principal residence exclusion, box 1e | Up to $750,000 ($375,000 married filing separately), but only for debt discharged before 2026 or under a written arrangement entered into before January 1, 2026 |
| The 1099-C is wrong (amount, year, or not your debt) | Corrected form from the creditor; identity theft goes on Form 14039 | None needed; income that isn't yours shouldn't be reported at all |
| Solvent, and no exclusion applies | Report the income; use a payment plan if you can't pay the resulting tax | $0 excluded, but the tax can be paid over time |
Three ordering rules matter here. First, bankruptcy beats insolvency. If the debt went through a Title 11 discharge, box 1a applies and you skip the worksheet entirely. Second, the home-mortgage exclusion has an end date and the insolvency exclusion does not. Per the Form 982 instructions and Publication 4681 as of November 2026, qualified principal residence indebtedness cannot be excluded for discharges completed, or discharge agreements entered into, after December 31, 2025, unless the arrangement was in writing before January 1, 2026. A mortgage canceled in 2026 therefore usually falls back on insolvency, box 1b, with the full worksheet. The insolvency exclusion itself is permanent law with no expiration date. Third, a wrong 1099-C is never a Form 982 problem. If you got a 1099 you weren't expecting for a debt you don't recognize, dispute the form instead of excluding it.
And if the math says part of the canceled debt is taxable and you can't pay the result, that's a solvable collection problem. The same options covered in CP2000: agree but can't pay apply, from 180-day short-term plans to monthly installment agreements. Run the numbers on our IRS payment plan calculator to see what a monthly arrangement on the leftover tax would look like. If the balance is already assessed and a CP14 notice has arrived, that guide covers the first bill.
Does IRS Form 982 insolvency apply to credit cards, student loans and mortgages?
The insolvency exclusion applies to any kind of canceled debt, but three common types each have a wrinkle worth knowing before you reach for box 1b.
- Credit cards, personal loans and medical debt. These are the classic insolvency cases. There is no special exclusion for them, so the worksheet decides everything. A settlement for less than the balance produces a 1099-C for the forgiven part once it reaches $600, and the creditor sends the IRS the same copy.
- Student loans. Publication 4681 lists several exclusions that need no insolvency math at all: discharges for working in certain professions, loan repayment assistance programs, death and total-and-permanent-disability discharges, and most student loans discharged in 2021 through 2025. A student loan discharged outside those rules falls back on insolvency like any other debt.
- Mortgages on your main home. The separate qualified principal residence exclusion on box 1e, capped at $750,000 ($375,000 married filing separately), covers only discharges before January 1, 2026 or discharges under an arrangement entered into and evidenced in writing before that date. A home loan canceled in 2026 usually has to use insolvency instead, with the full worksheet.
Whatever the debt type, the exclusion is claimed the same way: box 1b checked, the excluded amount on line 2, and the worksheet kept in your records.
How to fill out Form 982 for insolvency, step by step
Filing the insolvency exclusion correctly takes six moves. The ones the IRS never sees (your worksheet and records) matter as much as the ones it does. The form image on this page shows where each entry lands.
- Verify the 1099-C. Confirm box 1 (the cancellation date, which sets your tax year) and box 2 (the canceled amount), and confirm the debt is really yours and really canceled. A wrong form gets disputed with the creditor rather than excluded.
- Build your insolvency worksheet. Using the worksheet in Publication 4681, list every liability and every asset at fair market value as of the day before the cancellation, including retirement accounts. Liabilities minus assets is your insolvency amount.
- Complete Form 982. Check box 1b in Part I and enter your excluded amount on line 2: the smaller of the canceled debt or your insolvency amount.
- Reduce tax attributes in Part II. Most W-2 filers have no loss carryovers, credits, or business property basis to reduce, so Part II is often blank. If you do have attributes, follow the ordering rules in Publication 4681.
- Attach Form 982 to your return and file. File the form with your return for the box 1 year. Keep the worksheet, account statements, and valuation records, because the IRS can ask for proof long after you file.
- Amend if you already filed without it. File Form 1040-X with Form 982 attached, generally within 3 years of filing the original return, to claim the exclusion and recover tax you overpaid.
If you're amending, expect a wait. Amended returns move slowly, and our guide to where's my amended return explains the realistic timeline.
What does each line of Form 982 do?
An insolvency claim touches a small corner of the form: box 1b, line 2, and usually nothing else. The table below covers every line so you can see which ones apply to you and which belong to farm, business, and real estate situations. It follows the December 2021 instructions for the March 2018 form.
| Line | What it is | Who uses it |
|---|---|---|
| Part I, box 1a | Discharge in a Title 11 bankruptcy case, granted by the court while you were under its jurisdiction | Anyone whose debt was discharged in bankruptcy; the whole discharged amount is excluded |
| Part I, box 1b | Discharge while insolvent: liabilities exceeded the fair market value of your assets immediately before the discharge | Most individuals with a 1099-C; exclusion capped at the insolvency amount |
| Part I, box 1c | Qualified farm indebtedness, where 50% or more of aggregate gross receipts for the 3 prior tax years came from farming | Farmers whose debt came from a qualified lender |
| Part I, box 1d | Qualified real property business indebtedness: debt incurred in connection with, and secured by, real property used in a trade or business; an election to reduce that property's basis | Business and rental real estate owners; the election must be on a timely filed return |
| Part I, box 1e | Qualified principal residence indebtedness, capped at $750,000 ($375,000 married filing separately); only for debt discharged before 2026 or under a written arrangement entered into before January 1, 2026; cannot be checked for a Title 11 discharge | Homeowners with a canceled mortgage on their main home that meets the date rule |
| Part I, line 2 | Total amount excluded from gross income under section 108 | Everyone who checks a box in Part I; for insolvency, the smaller of the canceled debt or the insolvency amount |
| Part I, line 3 | Election to treat real property held primarily for sale to customers as depreciable property | Developers and dealers; not available for qualified real property business indebtedness |
| Part II, line 4 | Basis of depreciable real property reduced for the box 1d exclusion | Box 1d filers |
| Part II, line 5 | Election under section 108(b)(5) to reduce the basis of depreciable property first, with a statement describing the transactions | Filers with depreciable property who prefer to keep loss carryovers and credits |
| Part II, line 6 | Net operating loss and NOL carryovers, reduced dollar for dollar | Filers with an NOL; most W-2 filers skip it |
| Part II, line 7 | General business credit carryover, reduced 33 1/3 cents per dollar excluded | Business filers with credit carryovers |
| Part II, line 8 | Minimum tax credit carryover, reduced 33 1/3 cents per dollar excluded | Filers with a prior-year AMT credit |
| Part II, line 9 | Net capital loss and carryovers, reduced dollar for dollar | Filers carrying a capital loss forward |
| Part II, line 10a | Basis of nondepreciable and depreciable property, reduced dollar for dollar, limited to the excess of your total basis over your total liabilities immediately after the discharge | Insolvency filers who own property and have no earlier attributes to reduce |
| Part II, line 10b | Basis of your main home, reduced by the smaller of the box 1e exclusion or the home's basis | Box 1e filers who kept the home |
| Part II, lines 11a to 11c | Passive activity loss and credit carryovers; losses dollar for dollar, credits 33 1/3 cents per dollar | Rental and passive-business filers |
| Part II, line 12 | Foreign tax credit carryover, reduced 33 1/3 cents per dollar excluded | Filers with foreign tax credits carried forward |
| Part III, line 13 | Section 1082 basis adjustment for certain corporate reorganizations | Corporations only; individuals leave it blank |
How tax attribute reduction works in Part II
Excluding canceled debt is not free. Section 108(b) makes you reduce certain tax benefits, in a fixed order, by the amount you excluded: net operating losses first, then the general business credit, the minimum tax credit, net capital losses, property basis, passive activity losses and credits, and finally foreign tax credits. Losses and basis go down dollar for dollar, while credits go down 33 1/3 cents for each dollar excluded. The reduction happens after you figure your tax for the cancellation year, so it costs you in future years rather than this one.
For a typical wage earner with a canceled credit card, the practical effect is small. No NOL, no credits, no capital loss carryover, and the line 10a basis reduction is limited to the amount by which your total basis exceeds your total liabilities right after the discharge. If you are still underwater after the cancellation, that excess is zero and nothing gets reduced. Business situations use more of the form: the line 1d election, the line 3 election, and the section 108(b)(5) election to reduce depreciable basis first all interact with the ordering rules, and the instructions for Form 982 walk them line by line.
Can you file Form 982 electronically?
Yes, in the sense that matters. Form 982 goes in with your return rather than on its own, so if you can e-file the return you can e-file the form along with it. There is no separate submission, no separate deadline and no separate address for it.
What the IRS does not do is say anything about software. The instructions for Form 982 cover who qualifies and which lines to complete, and they never mention e-filing at all. So whether your particular program handles the form is a question for that program rather than for the IRS. Open its canceled-debt or 1099-C section and look for Form 982 by name. If it is not there, the fallback is to file that year's return on paper with the form attached. Slower, but not a problem, and better than skipping the exclusion because the software hid it.
Two things trip people up here. The insolvency worksheet is not part of Form 982 and does not get filed with it. You build it, use its number on line 2, and keep it with your records. And the form itself is still the March 2018 revision, with instructions last revised in December 2021 and no recent developments posted as of November 2026, so an older copy you already have is very likely the current one. Confirm it at IRS.gov before you rely on it.
What are the Form 982 deadlines, and what does each one protect?
The insolvency exclusion never expires as a law, but your chance to claim it for a given year does. Here is every clock on this problem, in order:
| Deadline | What to do | What you lose if it passes |
|---|---|---|
| January 31 after the cancellation year | Watch for the 1099-C; creditors send it by this date | Nothing yet, but the IRS gets its copy whether or not yours arrives |
| Your return due date (typically April 15) | Attach Form 982 to the return for the box 1 year | Nothing permanent, but the matching computer will flag the gap |
| Generally 3 years from the date you filed | Claim a missed exclusion on Form 1040-X | The refund from the exclusion is generally gone for good |
| CP2000 response date (typically about 30 days) | Respond with the worksheet and Form 982 | The proposed tax moves toward assessment unchallenged |
| 90 days after a CP3219A | Petition Tax Court or resolve the balance | The tax is assessed and collection begins |
One more right to keep in mind: if the IRS examines your return and disallows the exclusion, the decision isn't final. Smaller disputes can go to Appeals with Form 12203, where the insolvency worksheet gets a fresh look from someone other than the examiner who rejected it.
What to check before you file Form 982
Clarity Tax Relief runs these checks on every insolvency claim before it goes in. Most insolvency claims that fail come apart on one of these points:
- Your 401(k), IRA and pension interests are on the asset side at full value.
- The debt being canceled is on the liability side.
- Every balance is measured the day before the box 1 date, not the day you file.
- Line 2 shows the smaller of the canceled debt or your insolvency amount.
- The 1099-C is for a debt that is yours and was really canceled. A wrong form gets disputed with the creditor.
- A mortgage canceled in 2026 usually falls back on box 1b unless a written arrangement existed before January 1, 2026.
Can you handle Form 982 yourself?
Plenty of insolvency claims need no professional at all. You can confidently do this yourself when the picture is simple: one 1099-C, a clearly negative balance sheet (debts obviously dwarf assets even with retirement accounts counted), and clean records, meaning statements showing every balance as of the cancellation date. Fill in box 1b and line 2, keep the worksheet, and you are done.
Experienced help changes the outcome in fewer cases:
- The math is close. When insolvency turns on how you value a car, a house, or household goods, valuation judgment and documentation that survives review decide whether you exclude $28,700 or $0.
- Multiple 1099-Cs across dates or years. Each cancellation needs its own insolvency snapshot. The order matters because every discharge changes the next balance sheet.
- A CP2000 or exam is already open. Presenting insolvency to the underreporter unit is a documentation exercise with a deadline. If you'd rather a professional handle the correspondence directly, Form 2848 is how you authorize that.
- Business or rental debt was canceled. Part II attribute reduction gets real when there's depreciable property, loss carryovers, or basis to adjust, because a wrong ordering creates problems in future years.
- You can't pay whatever remains taxable. If the leftover tax needs a hardship or settlement analysis, the IRS will want your finances on Form 433-A, and how it's prepared shapes what you're offered.
If you are weighing whether to hire help, our tax relief cost comparison lays out what firms charge and what a case like this should cost. Clarity's investigation fee is $495 for individuals and $695 for businesses, and the first conversation is free. If the IRS has already assessed tax on the 1099-C, pulling your account transcript and reading it against our IRS transcript codes guide shows exactly where the balance stands before anyone responds.
What do the terms on your 1099-C and Form 982 mean?
- Cancellation-of-debt (COD) income: the forgiven balance the tax code treats as income because you kept money you never repaid.
- Insolvency: total debts greater than the fair market value of total assets, measured immediately before the cancellation. It is arithmetic rather than a court status.
- Fair market value (FMV): what an asset would sell for today, not what you paid for it or what you owe on it.
- Tax attributes: carryovers and basis (losses, credits, property basis) that Part II of Form 982 reduces in exchange for the exclusion. Most wage earners have none.
- Identifiable event (box 6): the creditor's code for why the debt was canceled, such as settlement, expired collection, foreclosure, or a policy decision to stop collecting.
- Qualified principal residence indebtedness: canceled mortgage debt on your main home, excluded at box 1e only for discharges before 2026 or under a written arrangement made before January 1, 2026.
IRS Form 982 questions, answered
What is IRS Form 982 used for?
IRS Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness, is used to figure how much canceled debt you can leave out of income under section 108 of the tax code. Part I says which exclusion applies (bankruptcy, insolvency, qualified farm debt, qualified real property business debt, or qualified principal residence debt) and how much you are excluding. Part II records the tax attributes you give up in exchange. For most individuals holding a 1099-C, the only entries are box 1b and line 2.
Do I attach the insolvency worksheet to Form 982?
No. The insolvency worksheet in Publication 4681 is for your records, and the IRS does not ask for it with the return. You use its bottom line, your insolvency amount, to fill in line 2 of Form 982, then keep the worksheet with the account statements and valuations that back it up. The IRS can ask for that proof years later, so a worksheet you cannot reconstruct is the same as no worksheet.
Can I file Form 982 after I already filed my return?
Yes. File Form 1040-X for the cancellation year with Form 982 attached, generally within 3 years of the date you filed the original return (or 2 years from when you paid the tax, if later). If you reported the 1099-C as income and paid tax you could have excluded, the amendment produces a refund. After the window closes, the refund is generally lost even if the insolvency math was airtight.
Do I have to file bankruptcy to use the Form 982 insolvency exclusion?
No. Insolvency is a math test rather than a legal status. You qualify if your total debts exceeded the fair market value of your total assets immediately before the cancellation, whether or not you ever filed anything in court. If the debt was discharged in a Title 11 bankruptcy case, you use box 1a instead. The entire discharged amount is excluded with no insolvency calculation at all.
Does the insolvency exclusion apply to state income taxes?
Usually, but not automatically. Most states start their tax calculation from federal adjusted gross income, so income you exclude federally with Form 982 never enters the state return. A minority of states decouple from parts of the federal rules, so confirm how your state treats canceled-debt income before assuming the exclusion carries through, especially if the amount is large.
Bottom line
Canceled debt is taxable unless you claim an exclusion, and insolvency is the one most people use. Build the worksheet as of the day before the box 1 date, count your retirement accounts, and exclude no more than your insolvency amount. Then attach Form 982 to the return for that year, or amend within the window if you already filed.
Your next 24 hours
- Find two numbers on your 1099-C: the date in box 1 (it sets the tax year and your measurement date) and the amount in box 2 (the income the IRS expects to see).
- Gather your day-before snapshot: statements or balances for every debt and every asset, including retirement accounts, as of the day before that box 1 date, plus your most recent tax return.
- Get the math checked free. Use the 2-minute form or call (888) 825-7779. If you're filing this year's return, amending inside the 3-year window, or answering a CP2000 that's already ticking, an experienced tax professional can confirm your insolvency number before the IRS taxes debt you may not owe a dime on.
Primary sources: the IRS's official pages for Form 982 and Publication 4681 (which contains the insolvency worksheet), and IRS.gov/payments if part of the canceled debt remains taxable and you need time to pay.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.