
IRS Notices
IRS CP2000 Notice: What It Is, the Deadline and How to Respond (2026)
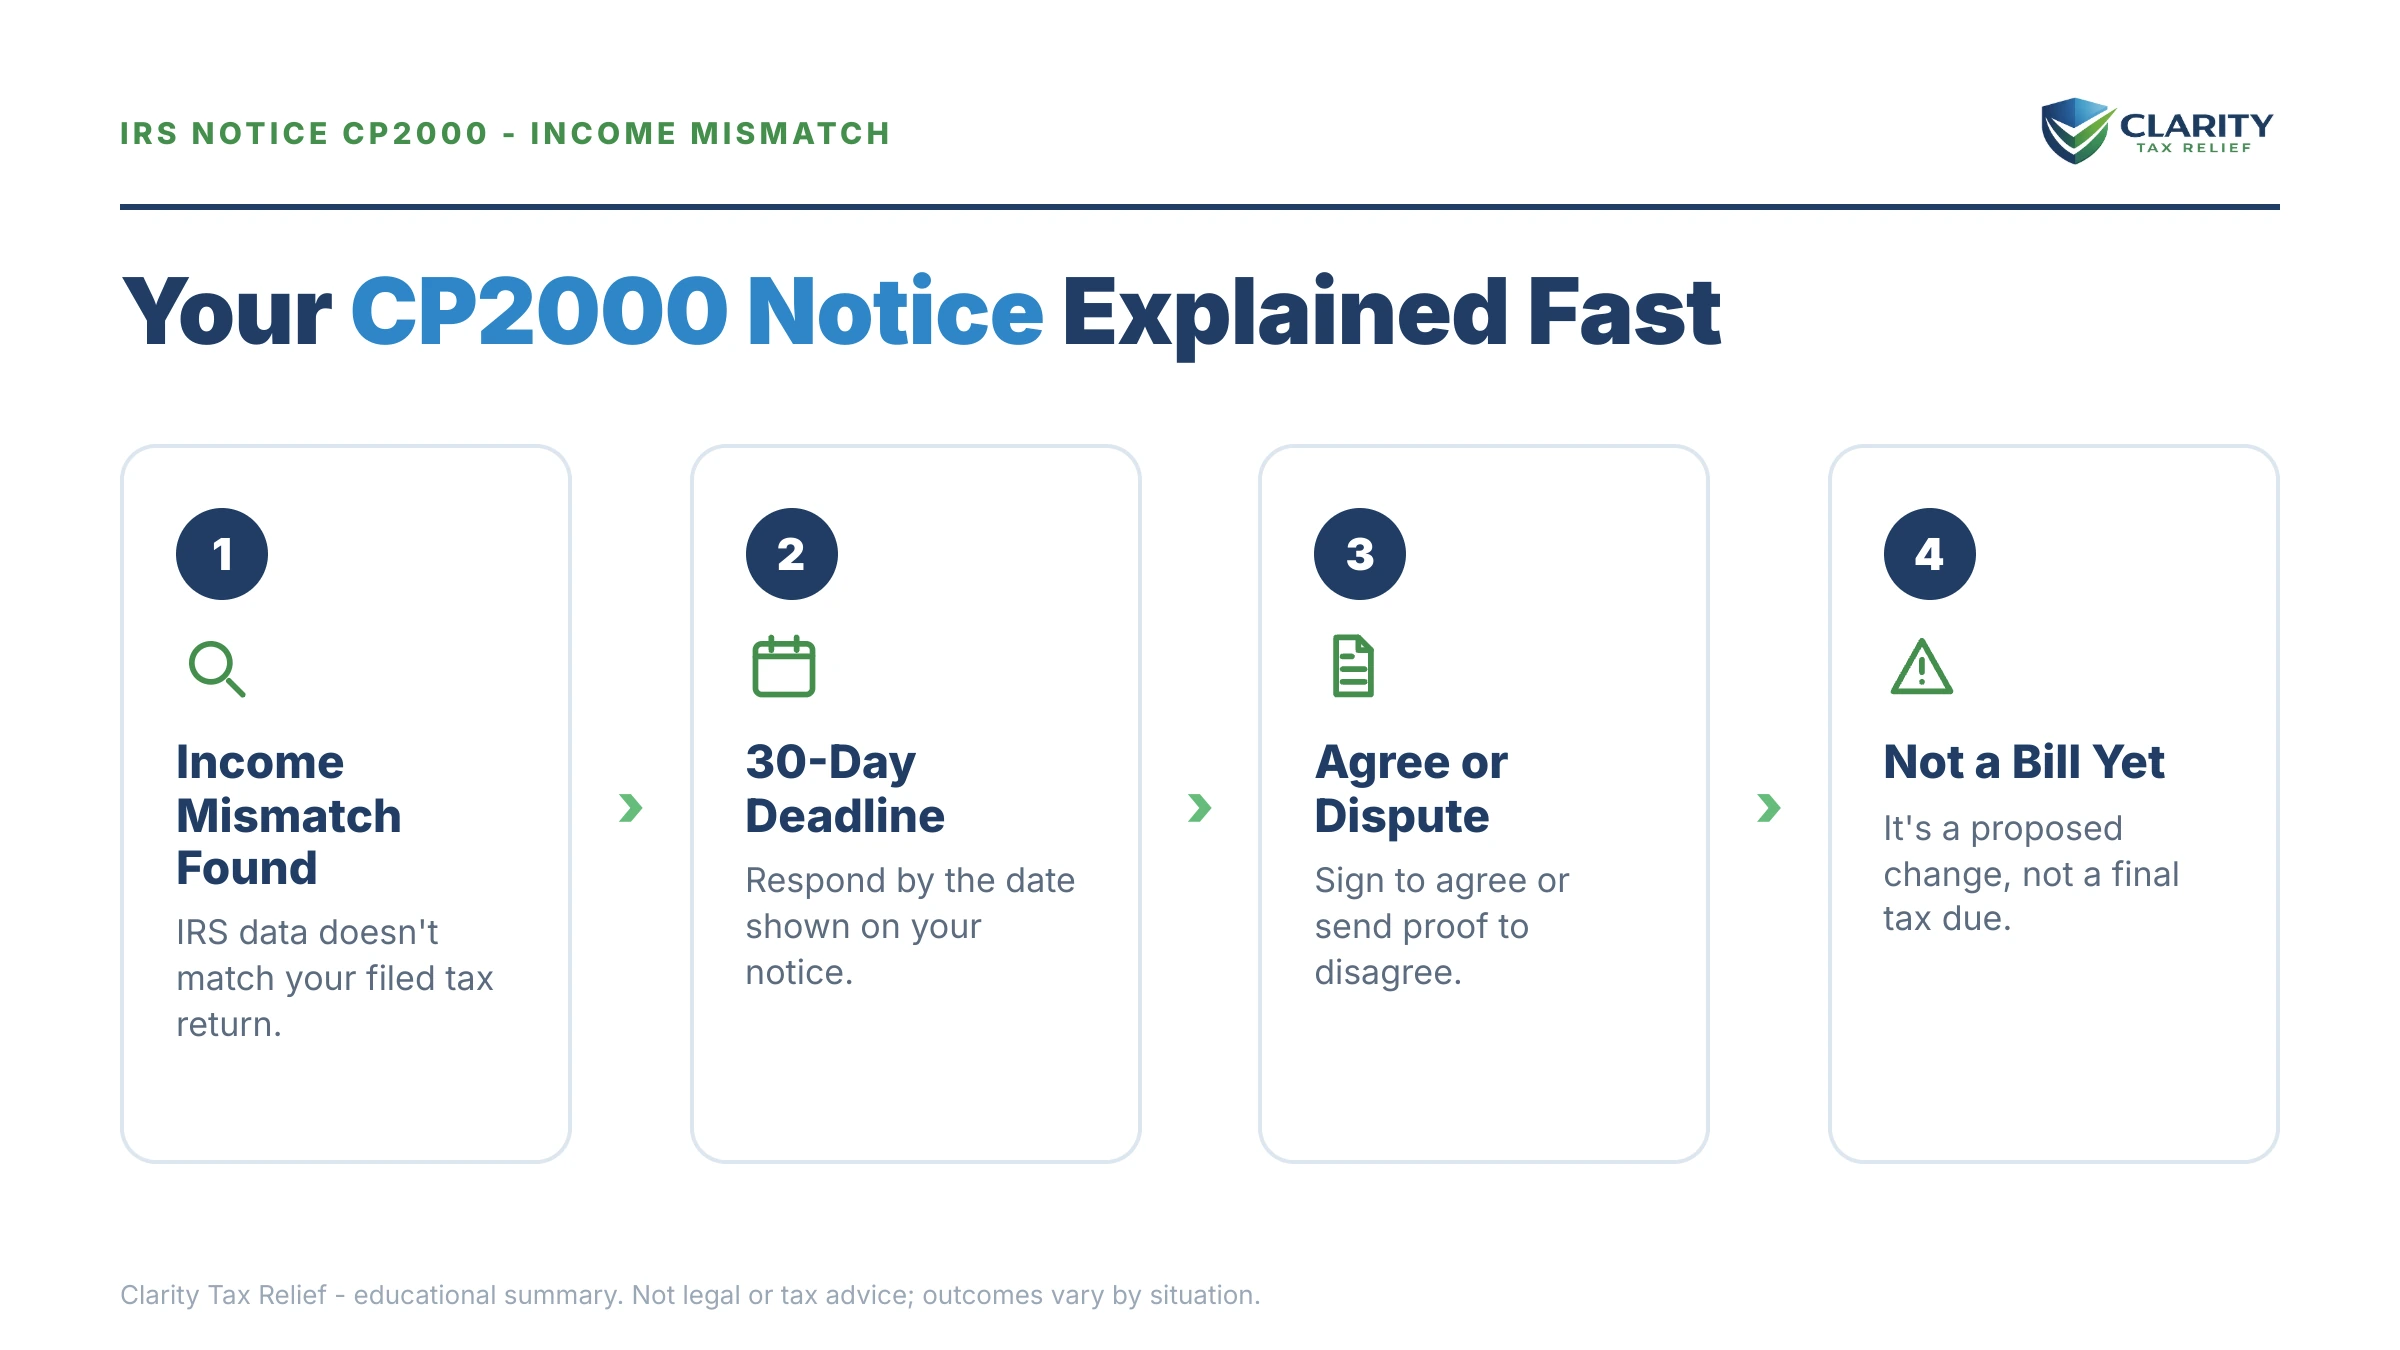
The short answer: a CP2000 notice means the income the IRS received from employers, banks and brokers does not match what you reported on your return. The IRS says the notice "isn't a bill," and it is not an audit. It proposes changes, and you reply by the date printed on it, typically 30 days from the notice date, to agree, partially agree or disagree.
This guide covers what a CP2000 is, which tax year it usually names, why the proposed amount so often runs high, how to answer it step by step, what to do if you agree but cannot pay, and what happens if you let the date pass. Read it top to bottom if the notice just arrived. If you already know what you dispute, skip to the response steps and the document table.
You filed months ago, expected nothing, and now several pages of IRS tables say your return "doesn't match the information reported to us," with a proposed amount due at the bottom. The part the notice buries: that number is a computer's opening position, calculated with no knowledge of your cost basis, rollovers or charitable IRA gifts. It is often wrong in ways you can document.
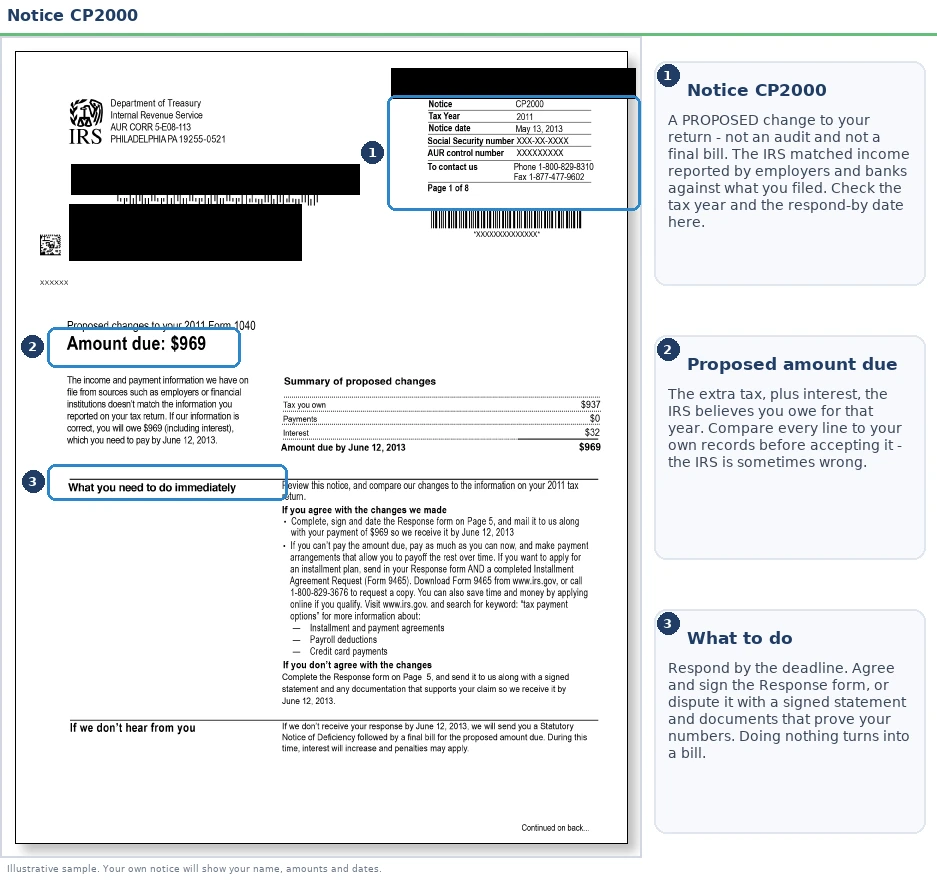
Three numbers on the notice control everything: the notice date, the response deadline and the proposed amount. The image below shows exactly what a CP2000 looks like and where each of those sits, so you can find yours before reading on. If you are not sure why the IRS wrote to you at all, our guide to why you got a letter from the IRS maps every letter type; this page covers the CP2000 only.
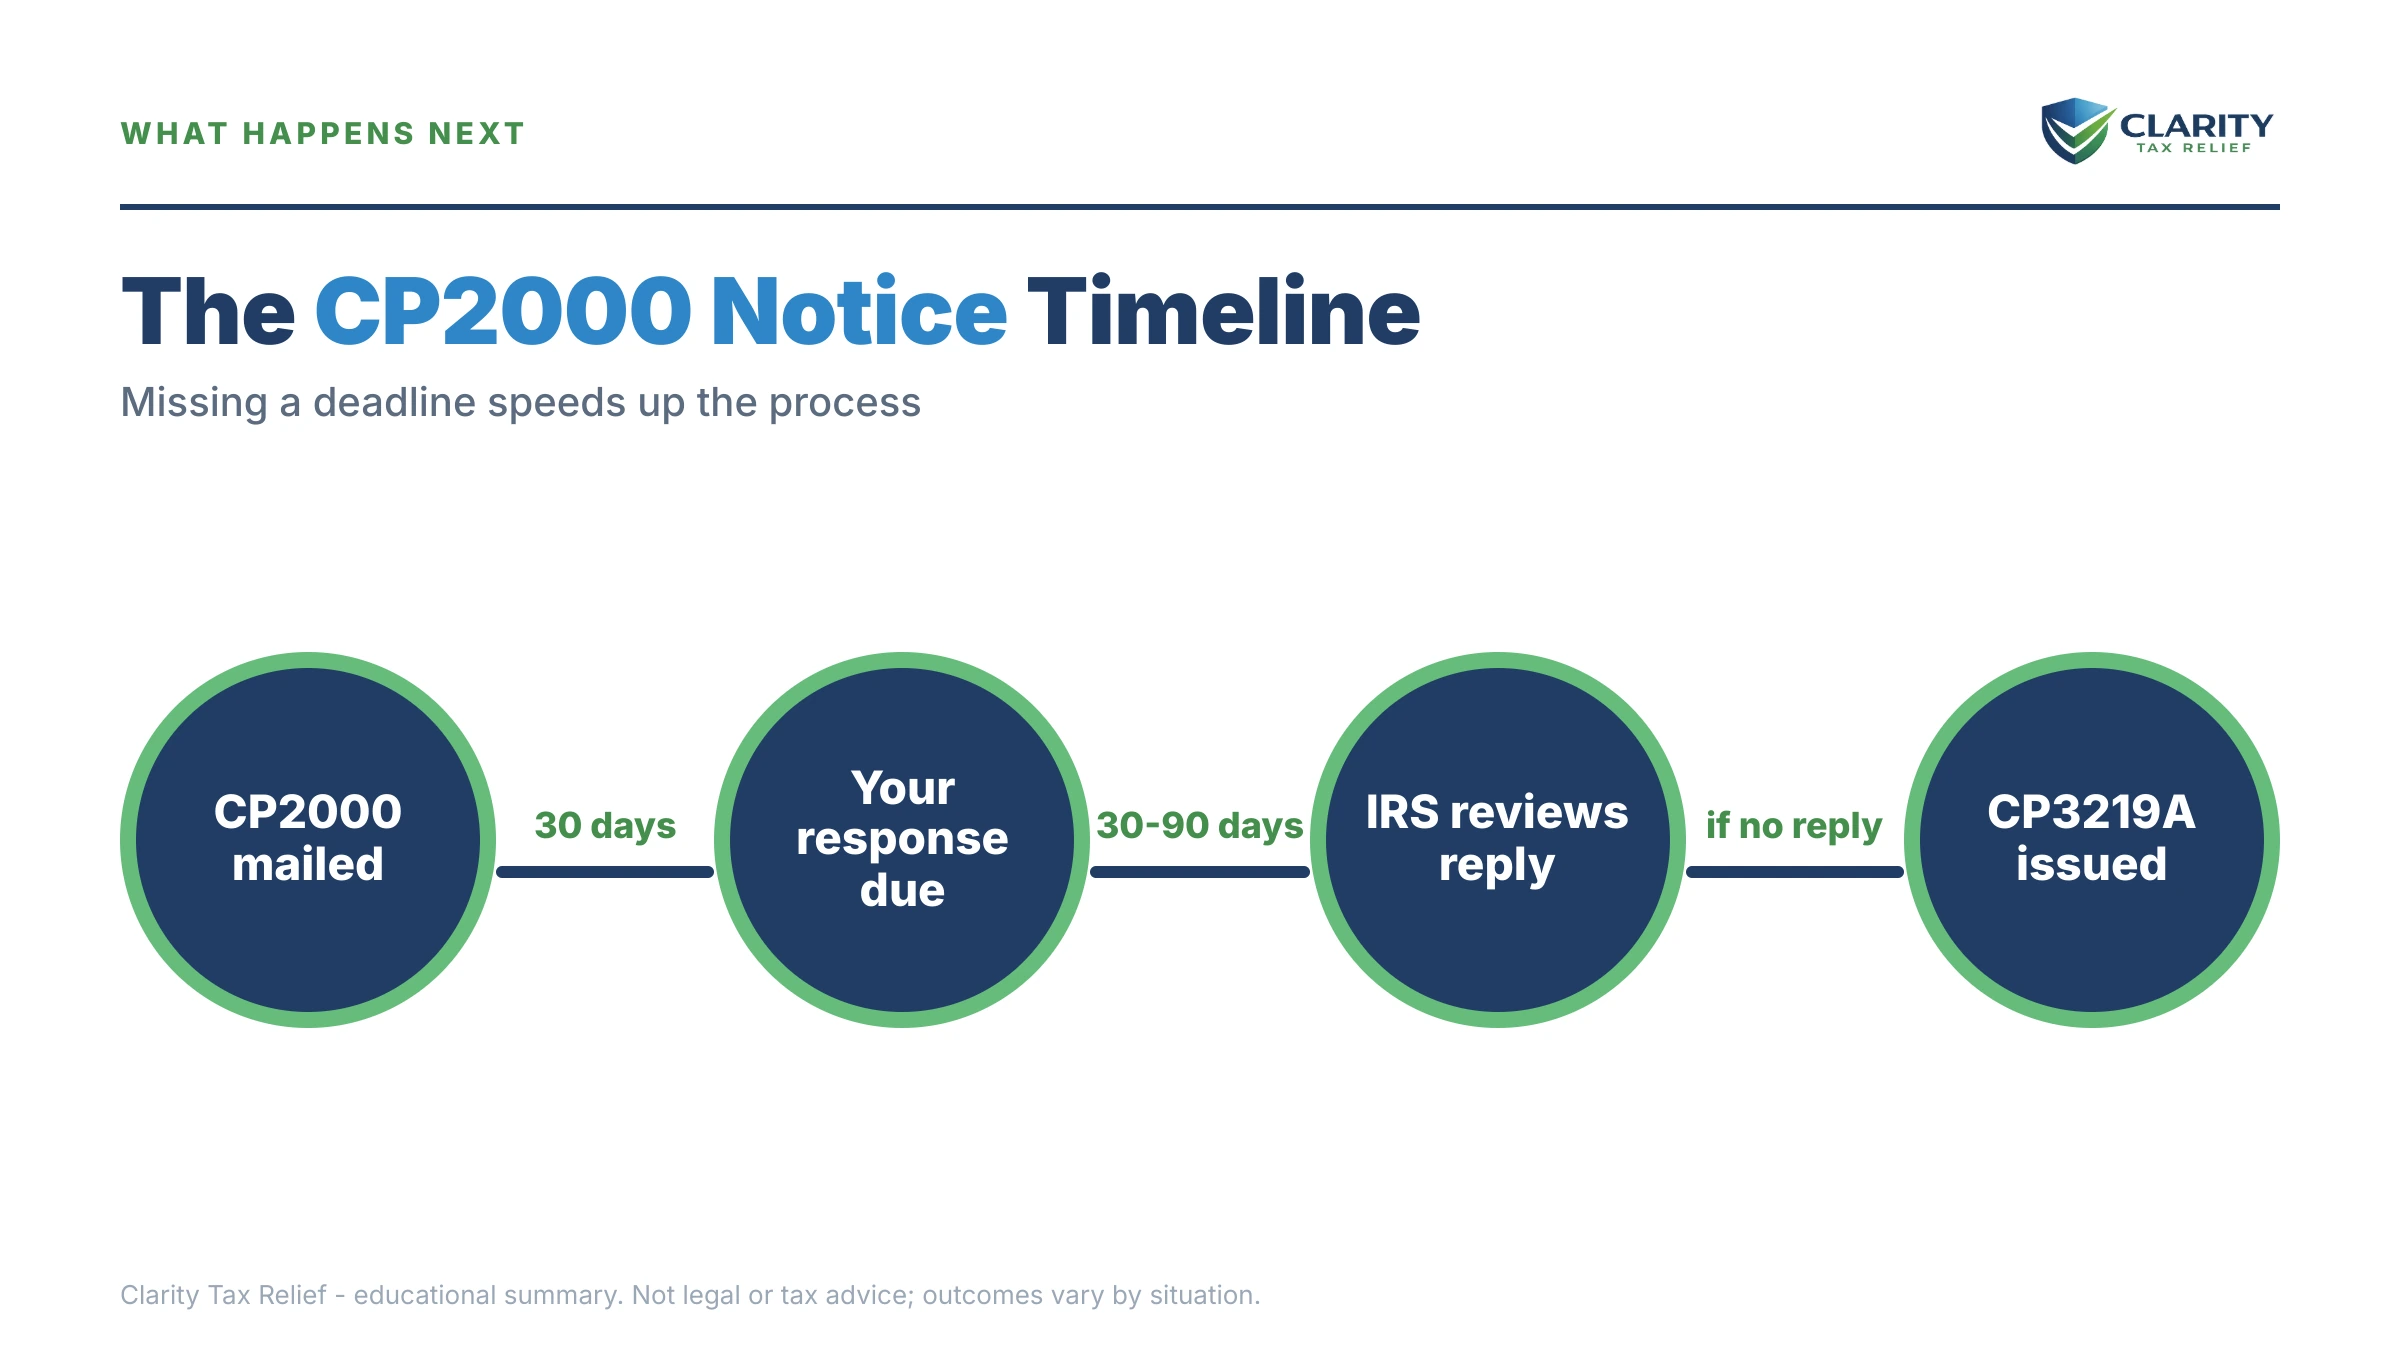
⏱ Your deadline: the response date printed on page 1 of your CP2000, typically 30 days from the notice date. Miss it and the IRS may send a CP3219A Statutory Notice of Deficiency, which opens a 90-day window to petition the Tax Court. Interest on any tax you actually owe keeps running the entire time.
What is a CP2000 notice, and why did the IRS send it?
The IRS puts the reason in one sentence: "The income or payment information we received from third parties, such as employers or financial institutions, doesn't match what you reported on your tax return." The notice comes from the Automated Underreporter (AUR) program. Every payer sends the IRS a copy of the form it sent you. Your employer's W-2, your bank's 1099-INT, your broker's 1099-B, your IRA custodian's 1099-R, the Social Security Administration's SSA-1099. A computer lines those copies up against your return, usually a year or more after you filed, and anything it cannot match becomes a proposed change.
No person decided you did something wrong. There is no examiner and no audit file. There is a mismatch, and mismatches happen to careful filers constantly. The common triggers:
- A 1099 that never made the return: a pension that started mid-year, a custodian that changed hands, a 1099 you weren't expecting.
- A rollover counted as taxable: you moved an IRA between institutions and the computer read the 1099-R as a cash-out.
- A qualified charitable distribution: the 1099-R reports the full amount you sent to charity from your IRA. The exclusion is invisible to the matching program.
- A 1099-B with no cost basis: the broker reported gross sale proceeds. The computer taxed the whole sale as if you paid nothing for the shares.
- The Social Security cascade: every dollar of added income can make more of your SSA-1099 benefits taxable, so the proposal taxes income you did report, at a higher level.
Two things a CP2000 is not. It is not a math-error correction. Those arrive as a CP11 or CP12 and change the return immediately. And it is not the gentler opening inquiry, the CP2501, which flags a mismatch without computing full dollar amounts. A CP2000 sits in between. Specific numbers, still a proposal.
Which tax year does a CP2000 notice in 2026 cover?
The tax year on your CP2000 will almost never be the year you are in. A notice that arrives in late 2026 most often covers tax year 2024, the return you filed in spring 2025, because the IRS has to collect every payer's forms, run the match and generate the proposal, and that takes a year or more. A CP2000 for tax year 2025 (the return filed in 2026) is possible but less common this early. If the notice names a year you did not file for at all, that is a different problem, and our unfiled returns page covers it.
Two numbers people type into Google alongside "CP2000" are the tax year and the proposed amount. Neither tells you much on its own. What matters is the line-item table on the inside pages. Each row names a payer, the amount the payer reported, the amount the IRS found on your return, and the difference. Pull that year's return and the forms for that year specifically. Mixing up 2024 and 2025 paperwork is the single most common reason a response fails to line up with the notice.
Is a CP2000 a bill or an audit?
Neither. The IRS's own page on the notice says, "This notice isn't a bill and your response may be required." Nothing has been assessed yet, and nothing is owed until you agree or the dispute windows close. It is not an audit either. An audit is an examination of your books and records by a person. A CP2000 is a document match run by a computer, and answering it does not open an audit. What it can do is become real tax, with a penalty and interest attached, if it is ignored. That is the only reason to treat the deadline as seriously as the notice suggests.
“This notice isn't a bill and your response may be required.”
Source: Understanding your CP2000 notice (IRS.gov)
Why is the CP2000 proposed amount often too high?
The AUR computer calculates the proposed tax using only the payer's numbers. It knows nothing about your cost basis, your rollover paperwork or your charitable intent, which produces an overstatement in a few predictable situations.
- Securities sales: when a 1099-B shows gross proceeds with no basis, the computer treats the entire sale price as gain. Sell $15,000 of a fund you bought for $13,600 and the real gain is $1,400. The proposal taxes all $15,000.
- Retirement account movements: trustee-to-trustee transfers, 60-day rollovers and QCDs all produce a 1099-R that looks like taxable income to a matching program.
- Stacked penalty and interest: many CP2000s add the 20% accuracy-related penalty plus interest from the return's original due date, both computed on the overstated tax, so shrinking the income correction shrinks them automatically.
The penalty and interest calculator estimates how much of a proposed balance is penalty and interest rather than tax.
Say a retiree's CP2000 proposes $8,900: additional tax of $7,150 on $39,000 of "unreported" income (a $24,000 IRA distribution and $15,000 of fund proceeds), a 20% accuracy penalty of $1,430, and $320 of interest. The brokerage statements show $13,600 paid for the shares, so the real gain is $1,400, and $12,000 of the IRA distribution went straight to a church as a qualified charitable distribution. A partial-agreement response with those two documents attached asks the IRS to recompute on roughly $13,400 of taxable income instead of $39,000. The tax, the penalty and the interest all fall with it. None of this means every CP2000 is wrong. Sometimes the missing 1099 is real and the number is right. It means you verify line by line before you agree to anything.
How do you respond to a CP2000, step by step?
Every CP2000 comes with a response form offering three positions: agree in full, partially agree, or disagree. The IRS's instructions are short. If you agree: "Follow the notice's instructions. You don't need to amend your return." If you disagree or partially agree: "Complete and sign it. State whether you agree or disagree with the notice and include any supporting documentation." The order of work, drawn from those instructions:
- Find the three numbers on page 1. The notice date, the response date and the tax year. Write the response date somewhere you will see it.
- Pull that year's paperwork. Your filed return for the year named on the notice, plus every W-2, 1099 and SSA-1099 for that same year. Not the current year.
- Check each line item. For every row in the table, decide whether the payer's figure is right, whether it was already on your return, and whether the computer is missing basis, a rollover or a QCD.
- Pick a position on the response form. Agree in full, partially agree, or disagree. Partial agreement is the most common correct answer.
- Attach a document for each disputed item. Copies, never originals, each one labeled so it ties to a specific row. A short signed statement itemizing what is right and wrong goes on top.
- Ask about the penalty in the same envelope. If you want the accuracy-related penalty removed, include the signed explanation and supporting documents with your response rather than waiting for a recomputed notice.
- Send it one of three ways. Through the IRS document upload tool linked from the notice, by fax to the number printed on it, or by mail to the address printed on it. The upload tool is the fastest and gives you a confirmation; fax is next; mail is slowest and the one you can prove, so use certified mail. If you filed jointly, both spouses sign.
- Keep copies and follow up. Silence from the IRS is not agreement. If a CP3219A arrives anyway, calendar its date immediately.
If you need to call about the notice instead, budget for it: our study of 188 IRS calls measured how long the lines run.
On amended returns, the IRS rule is narrower than most people assume. If you agree and have nothing else to report, "You don't need to amend your return." If you disagree, you answer on the response form with documents rather than with a 1040-X. The IRS asks for a Form 1040-X in one case only: the notice is correct and you also have other income, credits or expenses to report, and then it tells you to write "CP2000" across the top of the form. Outside that case, an amended return dropped into an open underreporter case creates a second, parallel file and can add months of confusion. Answer the notice on its own form.
| Your position | What you send | Watch out for |
|---|---|---|
| Agree in full | The signed response form, plus payment or a payment-plan request. The IRS assesses the amount and closes the case. | Only sign after checking every line item; an agreed assessment is hard to unwind. |
| Partially agree | The response form marked partially agree, a short signed statement itemizing what is right and wrong, and a document for each disputed item. | Expect a recomputed proposal months later. Ask for the accuracy penalty to be removed separately, with your reasonable-cause facts. |
| Disagree | The response form marked disagree, a point-by-point statement, and proof: basis statements, rollover confirmations, QCD receipts, a corrected 1099. | Silence from the IRS is not agreement; follow up. If a CP3219A arrives anyway, calendar its date immediately. |
What should a CP2000 response letter say, and what do you attach?
There is no official letter format, only required information, and the signed response form from the notice goes on top of the stack. Partial agreement is the most common correct answer, so that is the template below. The full versions for agreement, partial agreement and disagreement, with a worked example for each, are in our CP2000 response letter samples.
[Your name] · [Address] · [Daytime phone] · [Date]
Internal Revenue Service · [Address printed on your CP2000]
Re: Notice CP2000 dated [notice date], Tax Year [year] · AUR Control Number [from page 1] · [Your name], SSN ending [last four]
I received the CP2000 referenced above proposing changes to my [year] Form 1040. I partially agree with the proposed changes, and the signed response form is enclosed.
Item I agree with: the $[amount] of [type of income] from [payer] that was omitted from my return.
Item I disagree with: the proposed tax on $[amount] of gross proceeds reported by [broker] on Form 1099-B. The notice treats the full sale proceeds as taxable income. My cost basis in those shares was $[amount], as shown on the enclosed brokerage statement, so the correct taxable gain is $[amount].
Please recompute the proposed tax, the accuracy-related penalty and interest using the corrected figures and send me an updated notice before any assessment.
Sincerely, [Signature] [Printed name]
Enclosures: signed CP2000 response form; brokerage statement showing cost basis and purchase dates; copy of Notice CP2000, page 1
The letter is only as strong as its enclosures. Send copies, never originals, and label each one so it ties to a specific disputed item.
| What the IRS matched | Why the proposed tax is often too high | What to attach |
|---|---|---|
| Form 1099-B stock or fund sale | Basis was not reported, so the full sale price is taxed as gain | Brokerage statement showing cost basis and purchase dates |
| Form 1099-NEC or 1099-K side income | Gross receipts added with zero expenses, and self-employment tax on all of it | A completed Schedule C with expense records, sent with the response, not as an amended return |
| Form 1099-R retirement distribution | A rollover completed within 60 days is not taxable, but the computer cannot see it | Form 5498 or the receiving account's statement showing the rollover deposit |
| Duplicate or wrong-amount 1099 | The payer filed twice or reported the wrong figure | The corrected 1099 from the payer, plus one line of explanation |
| A 1099 that is not yours | Identity theft or a payer SSN error | A statement from the payer if you can get one; Form 14039 if it is identity theft |
| Income already on your return | Reported on a different line than the computer expected | A copy of the return page with the entry highlighted, keyed to the notice's line item |
What should you check on a CP2000 before you sign anything?
The same handful of problems show up on most CP2000s that turn out to be wrong. Go down this list before you mark agree.
- The tax year on the notice is older than you expected. That is normal. Check it against the paperwork you pull, because mixing years is the most common reason a response fails to line up.
- A 1099-B row with no cost basis. The computer taxed the whole sale price as gain. Your brokerage statement fixes it.
- A 1099-R row for money that was rolled over or sent to charity. The matching program cannot see a rollover or a QCD. Form 5498 or the receiving account's statement shows a rollover; the charity receipt shows a QCD.
- A 1099-NEC or 1099-K row taxed as pure profit. Gross receipts with zero expenses, and self-employment tax on all of it. A completed Schedule C with records, sent with the response, is the answer.
- A duplicate or wrong-amount 1099. Ask the payer for a corrected form and attach it.
- A 1099 that is not yours. That is identity theft or a payer SSN error. Form 14039 if it is identity theft, and a payer statement if you can get one.
- Income you did report, sitting on a different line. A copy of the return page with the entry highlighted, keyed to the notice's row, closes it.
- A penalty and interest computed on the overstated tax. Both shrink when the income correction shrinks, so never accept them as written before the income rows are settled.
- Social Security benefits taxed higher. Added income can make more of your SSA-1099 taxable, so the proposal may be taxing income you did report at a higher level. Fixing the income rows fixes this too.
What if you agree with the CP2000 but can't pay?
Agreeing and paying are two separate decisions. Sign the agreement so the case closes on the right number, then pick the payment path. The IRS's own instruction is "Get help if you can't pay in full. Apply for a payment plan or offer in compromise." The realistic options, in order of how many people they fit: a short-term plan of up to 180 days with no setup fee. A monthly installment agreement, which for balances up to $50,000 can be set up online without a financial statement. Currently Not Collectible status if paying anything would leave you unable to cover basic living expenses, which pauses collection while interest continues.
And a reasonable-cause request to remove the 20% accuracy penalty, which is not covered by first-time abatement and has to be asked for on its own facts. As of October 2026 the IRS lists the short-term plan at 180 days or less for balances under $100,000 with a $0 setup fee, and the online long-term plan for $50,000 or less with a $29 setup fee by direct debit ($69 otherwise, reduced for low-income filers). The full walkthrough with the math on each option is in CP2000: agree but can't pay. To see what a monthly plan on your proposed amount would look like, run the numbers in our IRS payment plan calculator before you sign the agreement.
Can you avoid or contest the accuracy-related penalty on a CP2000?
The penalty on a CP2000 is the accuracy-related penalty under IRC section 6662, which the IRS describes as "20% of the portion of the underpayment of tax that is attributable to negligence or disregard of rules or regulations." It also applies to a substantial understatement, which for an individual the IRS defines as understating tax by the greater of "10% of the tax required to be shown on your tax return or $5,000" (5% for returns claiming the section 199A deduction). That threshold is the first thing to check. Shrink the income correction with documents and the understatement often drops below it, and the penalty goes with it.
If the understatement stays above the line, the penalty is still contestable. The IRS asks for the notice, the penalty you want reconsidered, and "a signed explanation of why you think we should remove it along with supporting documents." Facts that carry weight are the ones you can show on paper: a payer's form that arrived late or wrong, a corrected 1099 issued after you filed, a preparer's error you relied on. If you relied on a payer's incorrect form, say so directly in your response instead of accepting the penalty by default. Put that request in the same envelope as your response. Interest is separate and is not removable on reasonable cause. The IRS underpayment rate for the quarter beginning October 1, 2026 is 7%, and it runs from the return's original due date until the balance is paid.
What happens if you don't respond to a CP2000?
The IRS says it plainly: "If you don't reply or we can't resolve the discrepancy, we may send another notice and a bill." The sequence is automated and runs in order:
- The response date passes. Silence is treated as an unresolved discrepancy, and interest on any tax you owe keeps running.
- A CP3219A arrives. The CP3219A Statutory Notice of Deficiency is, in the IRS's words, not "a bill or audit" but notice "of a proposed change in your tax." It opens a 90-day response period. You can still send documents with the enclosed Form 5564 and the IRS says it will "work with you to resolve your issue during the 90-day response period," or you can petition the Tax Court by the date on the notice. The IRS warns that "the Tax Court can't consider your case if you file the petition late."
- The tax is assessed. "If we don't hear from you and you don't file a petition, we'll assess the proposed changes and send you a bill." The proposal is now a legal debt. Your dispute rights narrow from prove-your-case-by-mail to pay-first.
- Collection begins. A bill, usually a CP14, then the collection notice sequence ending in a final notice of intent to levy. After that the IRS can file a lien, levy bank accounts, and, for retirees, take up to 15% of monthly Social Security benefits through the Federal Payment Levy Program.
| Stage | When | What you can still do |
|---|---|---|
| Code 922 posts to the transcript | Often weeks before any letter | Gather that year's income forms and your filed return. |
| CP2501 or CP2000 arrives | Usually a year or more after you filed | Check every line item; decide agree, partially agree or disagree. |
| Response date on page 1 | Typically 30 days from the notice date | Send the signed response form and documents by upload, fax or certified mail. |
| IRS recomputes or closes the case | Weeks to several months after your response | Answer any follow-up letter; keep copies of everything sent. |
| CP3219A Statutory Notice of Deficiency | If the discrepancy is unresolved after the response date | Respond with Form 5564 and documents, or petition the Tax Court by the date on the notice. The IRS says a late petition cannot be considered. |
| Assessment (code 290) and a bill | After the 90-day period passes with no petition | Pay, set up a plan, or request audit reconsideration with documents you never sent. |
Holding a CP2000 with the clock running?
Get it reviewed free before the response date on page 1 passes. A licensed tax professional will say whether to agree, partially agree or dispute, and exactly which document to send for each item.
Which transcript codes go with a CP2000?
An open underreporter case shows on your IRS account transcript as code 922, often before the CP2000 arrives in the mail. Pull the account transcript for the tax year named on the notice, not the current year. If you check the transcript while the case is open, these are the codes to look for (the full list is in our IRS transcript codes guide):
| Code | What it means | What to do |
|---|---|---|
| 922 | An underreporter (AUR) review of that tax year has been opened. | Watch the mail for a CP2501 or CP2000 and gather that year's income documents now. |
| 971 | A notice was issued, often the CP2000 itself. | Match the 971 date to the notice date on your letter; the response clock runs from there. |
| 570 | A hold on the account, often freezing any refund while the review is open. | Nothing to fix directly; resolving the CP2000 resolves the hold. |
| 290 | Additional tax was assessed: the case closed against you, or you agreed. | If you never responded, ask about audit reconsideration; if you agreed, arrange payment. |
| 291 | The assessment was reduced: your documentation was accepted. | Keep the closing letter with that year's records. |
When can you handle a CP2000 yourself?
Most single-issue CP2000s need no professional help. The notice is right, you missed one 1099, and you can pay the balance or set up an online plan. Or the fix is one clean document, a broker statement showing basis or a custodian letter confirming a rollover. Experienced help changes outcomes in a narrower set of cases. A CP3219A has already arrived and the 90-day clock is running. More than one tax year has an open case. The mismatch involves self-employment income, where the computer adds SE tax on gross receipts. A 1099 in your name is identity theft or someone else's. Or the balance is unpayable on a fixed income and the real question is hardship status versus a plan. If the IRS misses its own timelines while you have met yours and the case stalls for many months, the Taxpayer Advocate Service exists for that.
Terms on your CP2000, decoded
- AUR (Automated Underreporter): the IRS program that matches payer-reported income against tax returns and generates CP2000s. No human examiner is involved.
- Proposed amount due: the tax, penalty and interest the IRS suggests you owe. Not an assessed debt until you agree or the dispute windows close.
- Response form: the page inside your CP2000 where you mark agree, partially agree or disagree. It is the correct way to answer the notice.
- Accuracy-related penalty: a 20% penalty under IRC section 6662 for substantial understatement, removable on a reasonable-cause showing.
- Statutory Notice of Deficiency (CP3219A): the notice that can follow an unresolved CP2000. It opens a 90-day period to respond with Form 5564 or to petition the Tax Court. The full IRS explainer for the CP2000 is at Understanding your CP2000 notice.
The bottom line on answering a CP2000
A CP2000 is a computer's proposal, and the number on it is where the conversation starts. Check every row against that year's forms. Then answer on the response form by the date on page 1, with one document for each item you dispute, and ask about the penalty in the same envelope. Let the date slide and the proposal can turn into an assessed bill, which is a much harder thing to argue with.
Common questions
How long do I have to respond to a CP2000?
Until the response date printed on page 1 of the notice, which is typically 30 days from the notice date. Use the printed date rather than your own count. If you cannot gather documents in time, a mailed response postmarked by the date protects you, and you can send additional information afterward. Missing the date does not end the case, but it moves it toward a CP3219A.
How do I send my CP2000 response?
Three ways, all listed on the notice: the IRS document upload tool (JPG, PNG or PDF files), fax to the number printed on the notice, or mail to the address on page 1. Send the signed response form on top, then a document for each item you dispute. Use the upload tool or certified mail so you have proof of the date.
Should I file an amended return to answer a CP2000?
Usually no. The IRS says that if you agree, "You don't need to amend your return," and if you disagree, you complete and sign the response form and include documentation. The IRS asks for a Form 1040-X only when the notice is correct and you also have other income, credits or expenses to report, with "CP2000" written across the top. Otherwise explain any corrections in your response.
The bottom line on a CP2000
A CP2000 is a computer's proposal, and the number on it is where the conversation starts. Check every line item against that year's forms. Then answer on the response form by the date on page 1, with a document for each item you dispute. Let the date slide and the proposal can turn into an assessed bill, which is a much harder thing to argue with.
Your next 24 hours, step by step
- Find the two dates on page 1 of your CP2000, the notice date and the response deadline, plus the tax year it covers, and write the deadline where you will see it.
- Gather that year's paperwork: your filed return and every 1099-R, 1099-B, 1099-INT, 1099-DIV, W-2 and SSA-1099, especially any statement showing cost basis, a rollover or a QCD.
- Get a free case review before the response date: the 2-minute form at claritytaxrelief.com/#consult or (888) 825-7779. One call tells you whether to agree, partially agree or dispute, while all three doors are still open.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.
Read the transcript
Host: So you filed months ago, you figured you were done, and then several pages of IRS tables show up saying your return doesn't match what was reported to them. And there's a proposed amount at the bottom big enough to swallow months of retirement income.
Tax specialist: Right. And the first thing to say, because the notice does not say it clearly, that is not a bill. It's a proposal.
Host: Not a bill. Not an audit either?
Tax specialist: Not an audit. A CP2000 comes out of a program called the Automated Underreporter, AUR. Every payer sends the IRS a copy of what they sent you. Your bank, your brokerage, your IRA custodian, Social Security. A computer lines those copies up against your return, usually a year or more later, and anything it can't match becomes a proposed change. No examiner. No audit file. Nobody suspects you of anything.
Host: Okay, so it's a machine. But the number on it still feels very real.
Tax specialist: It's real in the sense that it can become a legal debt. It's not real in the sense of being accurate. That computer knows the payer's number and nothing else. It doesn't know your cost basis, it doesn't know you did a rollover, it doesn't know you sent money from your IRA to your church.
Host: Give me the clearest version of that.
Tax specialist: Sold fifteen thousand dollars of a mutual fund. The 1099-B reports gross proceeds, fifteen thousand. If it shows no basis, the computer treats the whole fifteen thousand as gain. But if you paid thirteen thousand six hundred for those shares, your actual gain is fourteen hundred dollars.
Host: Thirteen-six in, fifteen out. So fourteen hundred of gain, and the proposal is taxing all fifteen thousand.
Tax specialist: Correct. Same story with retirement money. A trustee-to-trustee transfer, a sixty-day rollover, a qualified charitable distribution: all three generate a 1099-R that looks like taxable income to a matching program. The exclusion is invisible to it.
Host: Hm. And there's a Social Security piece too, isn't there.
Tax specialist: That's the part people miss. Every dollar of added income can make more of your Social Security benefits taxable. So the proposal ends up taxing income you did report correctly, just at a higher level. It cascades.
Host: Walk me through the example in the article. The eighty-nine hundred.
Tax specialist: Sure. Hypothetical retiree, prior tax year, CP2000 proposes eighty-nine hundred dollars. Two items the notice says are missing: a twenty-four thousand dollar IRA distribution on a 1099-R, and fifteen thousand of mutual fund proceeds on a 1099-B. The computer's math: additional tax on thirty-nine thousand of so-called unreported income plus newly taxable Social Security, seventy-one fifty. Then a twenty percent accuracy penalty on that tax, fourteen hundred thirty. Then interest from the original due date, three hundred twenty. Adds to eighty-nine hundred.
Host: And the actual facts were different.
Tax specialist: The brokerage statements show thirteen thousand six hundred paid for the shares, so fourteen hundred of gain, not fifteen thousand. And twelve thousand of that IRA distribution went straight to the church as a QCD, which is excludable. A partially-agree response with those documents attached asks the IRS to recompute on roughly thirteen thousand four hundred of taxable income instead of thirty-nine thousand.
Host: Wait, and the penalty moves with it?
Tax specialist: That's the mechanical part. The twenty percent penalty is computed on the tax, and the interest runs on the tax. Shrink the income correction and both of those shrink with it automatically. You don't argue them separately, although you can also ask for the accuracy penalty to be removed for reasonable cause, and you should address that directly instead of letting it ride.
Host: Reasonable cause meaning what, in plain terms?
Tax specialist: Facts like. You relied on a payer's incorrect form, or a preparer's error, or records you had no way to know were incomplete. You have to make that showing. Nobody applies it for you, and I'm not going to tell you how the IRS will rule on it.
Host: Fair. Let's do the clock, because that's the anxious part.
Tax specialist: Three numbers control everything and they're all on page one. The notice date, the response deadline, and the proposed amount. The deadline is typically thirty days from the notice date, but use the printed date, not your own counting.
Host: And if that date passes?
Tax specialist: The case moves toward a CP3219A, a Statutory Notice of Deficiency. That opens a strict ninety-day window to petition Tax Court, and that ninety days is statutory. Nobody at the IRS can extend it. If that window also closes, the tax gets assessed, and your position changes from prove-your-case-by-mail to pay-first-argue-later.
Host: Then collection.
Tax specialist: Then a bill, then escalating notices, ending in a final notice of intent to levy. After assessment the IRS can file a lien, levy bank accounts, and take up to fifteen percent of monthly Social Security through the Federal Payment Levy Program. None of that can happen at the proposal stage, but the sequence is automated. It escalates on schedule whether or not a human ever reads your file.
Host: Okay. So what do you actually send?
Tax specialist: The response form that comes inside the notice. Three boxes: agree in full, partially agree, disagree in full. Mark one, attach proof for every item you dispute: broker statements, rollover confirmations, QCD acknowledgments, a corrected 1099. Then mail it certified so you can prove the postmark.
Host: And the thing not to do.
Tax specialist: Do not file Form 1040-X. The IRS says so on the notice itself. An amended return dropped into an open underreporter case creates a second parallel file and can add months of confusion. It's an expensive first move to undo.
Host: Say that one again more simply for me.
Tax specialist: Don't amend your return. Answer the notice on its own form.
Host: Got it. What if someone checks their transcript while they're waiting?
Tax specialist: You may see code 922, that's the underreporter review being opened, sometimes before the notice even arrives. Code 971 means a notice was issued; match that date to your notice date, because the clock runs from there. Code 570 is a hold, often freezing a refund while the review is open. Code 290 is additional tax assessed, and 291 means an assessment was reduced.
Host: 922, 971, 570. And what about someone who agrees with the notice but can't write the check?
Tax specialist: Those are two separate decisions. Sign the agreement, then pick the payment path. There's a short-term plan, up to a hundred eighty days, no setup fee. For balances of ten thousand or less, the IRS's own rules make the Guaranteed Installment Agreement available when you meet its filing and payment conditions. Balances up to fifty thousand can go as long as seventy-two months online with no financial statement. And if a fixed income barely covers living expenses, Currently Not Collectible status can pause collection. The debt stays and interest keeps accruing, but no levy touches benefits while the hardship holds.
Host: And plenty of these people don't need us at all, right?
Tax specialist: Honestly, no. If the notice is right, you missed one 1099, and the fix is one clean document, and you can handle the balance, do it yourself. Where experience actually matters is narrower. A CP3219A already sitting on top of the CP2000 with that ninety-day clock running. Multiple years open. Self-employment income in the mix, because SE tax gets computed wrong. A 1099 that isn't yours, identity theft. Or the balance is unpayable and the real question is hardship versus a plan.
Host: So, next twenty-four hours.
Tax specialist: Find the notice date, the response deadline, and the tax year on page one, and write that deadline somewhere you'll see it. Then pull that year's return and every 1099-R, 1099-B, 1099-INT, 1099-DIV and SSA-1099, especially anything showing basis, a rollover, or a QCD. If you want a second set of eyes before the date passes, the review is free: eight-eight-eight, eight-two-five, seven-seven-seven-nine.
Host: While all three boxes are still open.
Tax specialist: That's the whole point of moving now.