
IRS Forms
Form 14039 Identity Theft Affidavit: What It Is and How to File It (2026)
The short answer: the Form 14039 identity theft affidavit tells the IRS someone used your Social Security number to file a tax return or earn wages. File it when your e-filed return is rejected as a duplicate or a debt appears from a return you never filed, not for a 5071C verification letter.
This guide covers Form 14039, the IRS identity theft affidavit: when to file it, when filing it is the wrong move, what the IRS does with it once it arrives, and how to keep a collection notice from turning into a levy while the identity-theft unit works your case. If a notice says you owe $16,400 on a return you never filed, and the IRS is warning it may levy the bank account your rent comes out of, this is the situation the form exists for. There is a specific order of moves that unwinds it.
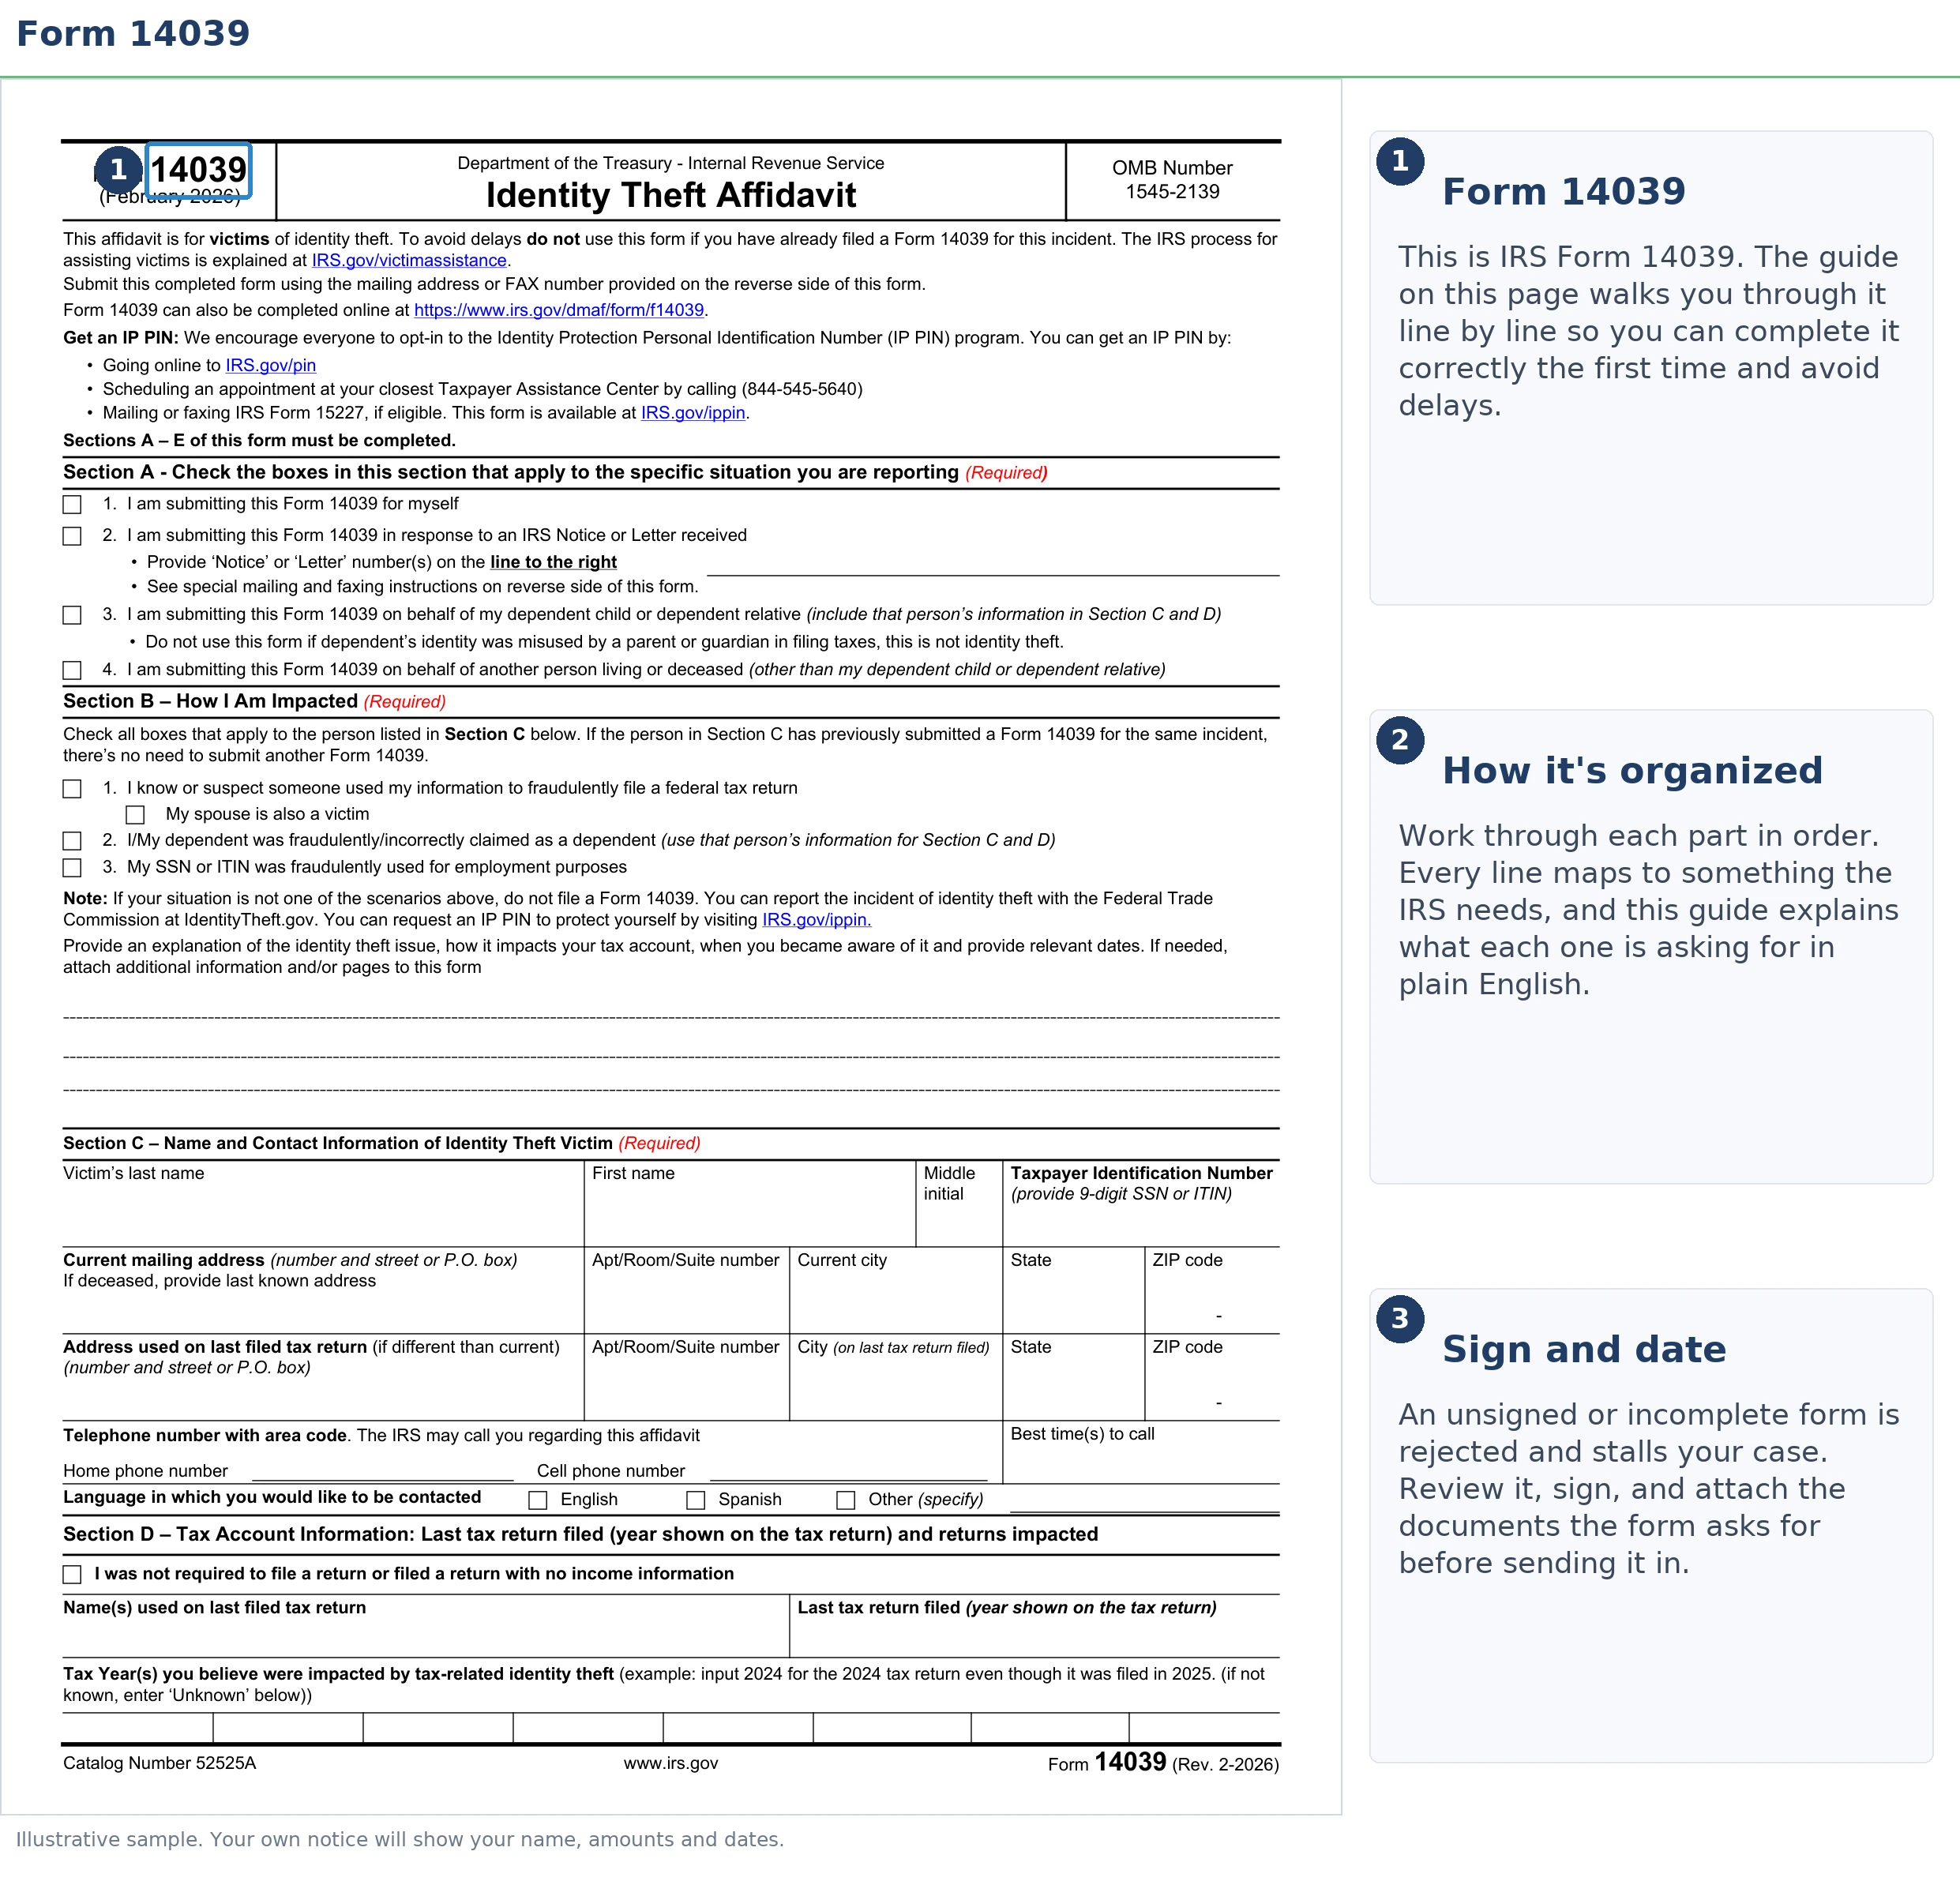
The affidavit is one page. The IRS routes your whole case based on which boxes you check in Section B, and the image below shows what the form looks like and where those checkboxes sit, so you can see what you are filling out before you start.
⏱ The clocks that matter: Form 14039 has no filing deadline of its own, but the collection notices riding alongside a fraudulent debt do. You have 30 days from the date on an LT11 or Letter 1058 to request a Collection Due Process hearing. Miss that window and the IRS can levy while your identity-theft case waits in the queue. Interest and penalties also keep accruing on any assessed balance until it is reversed.
When should you file the Form 14039 identity theft affidavit?
Form 14039 is a sworn statement, signed under penalty of perjury, that your Social Security number was used by someone else on a tax return or for wages. Once it is in the system, the IRS opens a case with its Identity Theft Victim Assistance (IDTVA) unit. That unit is responsible for separating the thief's activity from your real tax history.
The common triggers, roughly in order of how often we see them:
- Your e-filed return bounced with a rejection saying a return already exists under your SSN. Someone beat you to filing, usually chasing a fraudulent refund.
- An IRS notice references a return you never filed, or income, employers, or dependents that are not yours. If you are still decoding what the letter even is, start with why did I get a letter from the IRS, then come back.
- Your wage records show a job you never worked. Someone is using your SSN for employment, and their W-2 income lands on your IRS record. Your wage and income transcript is where this shows up first.
- Collection notices arrived for a phantom debt. The fraud happened years ago and was never caught. The assessment has been quietly aging into levy territory ever since.
- The IRS told you to file it. Some identity letters instruct you to submit the affidavit as part of their process.
Form 14039 is none of these things: a payment dispute, an audit response, or a way to challenge a debt you know is yours. It applies only when the underlying filing or income was never you. For the broader "someone stole my refund" playbook, see someone filed taxes in my name.
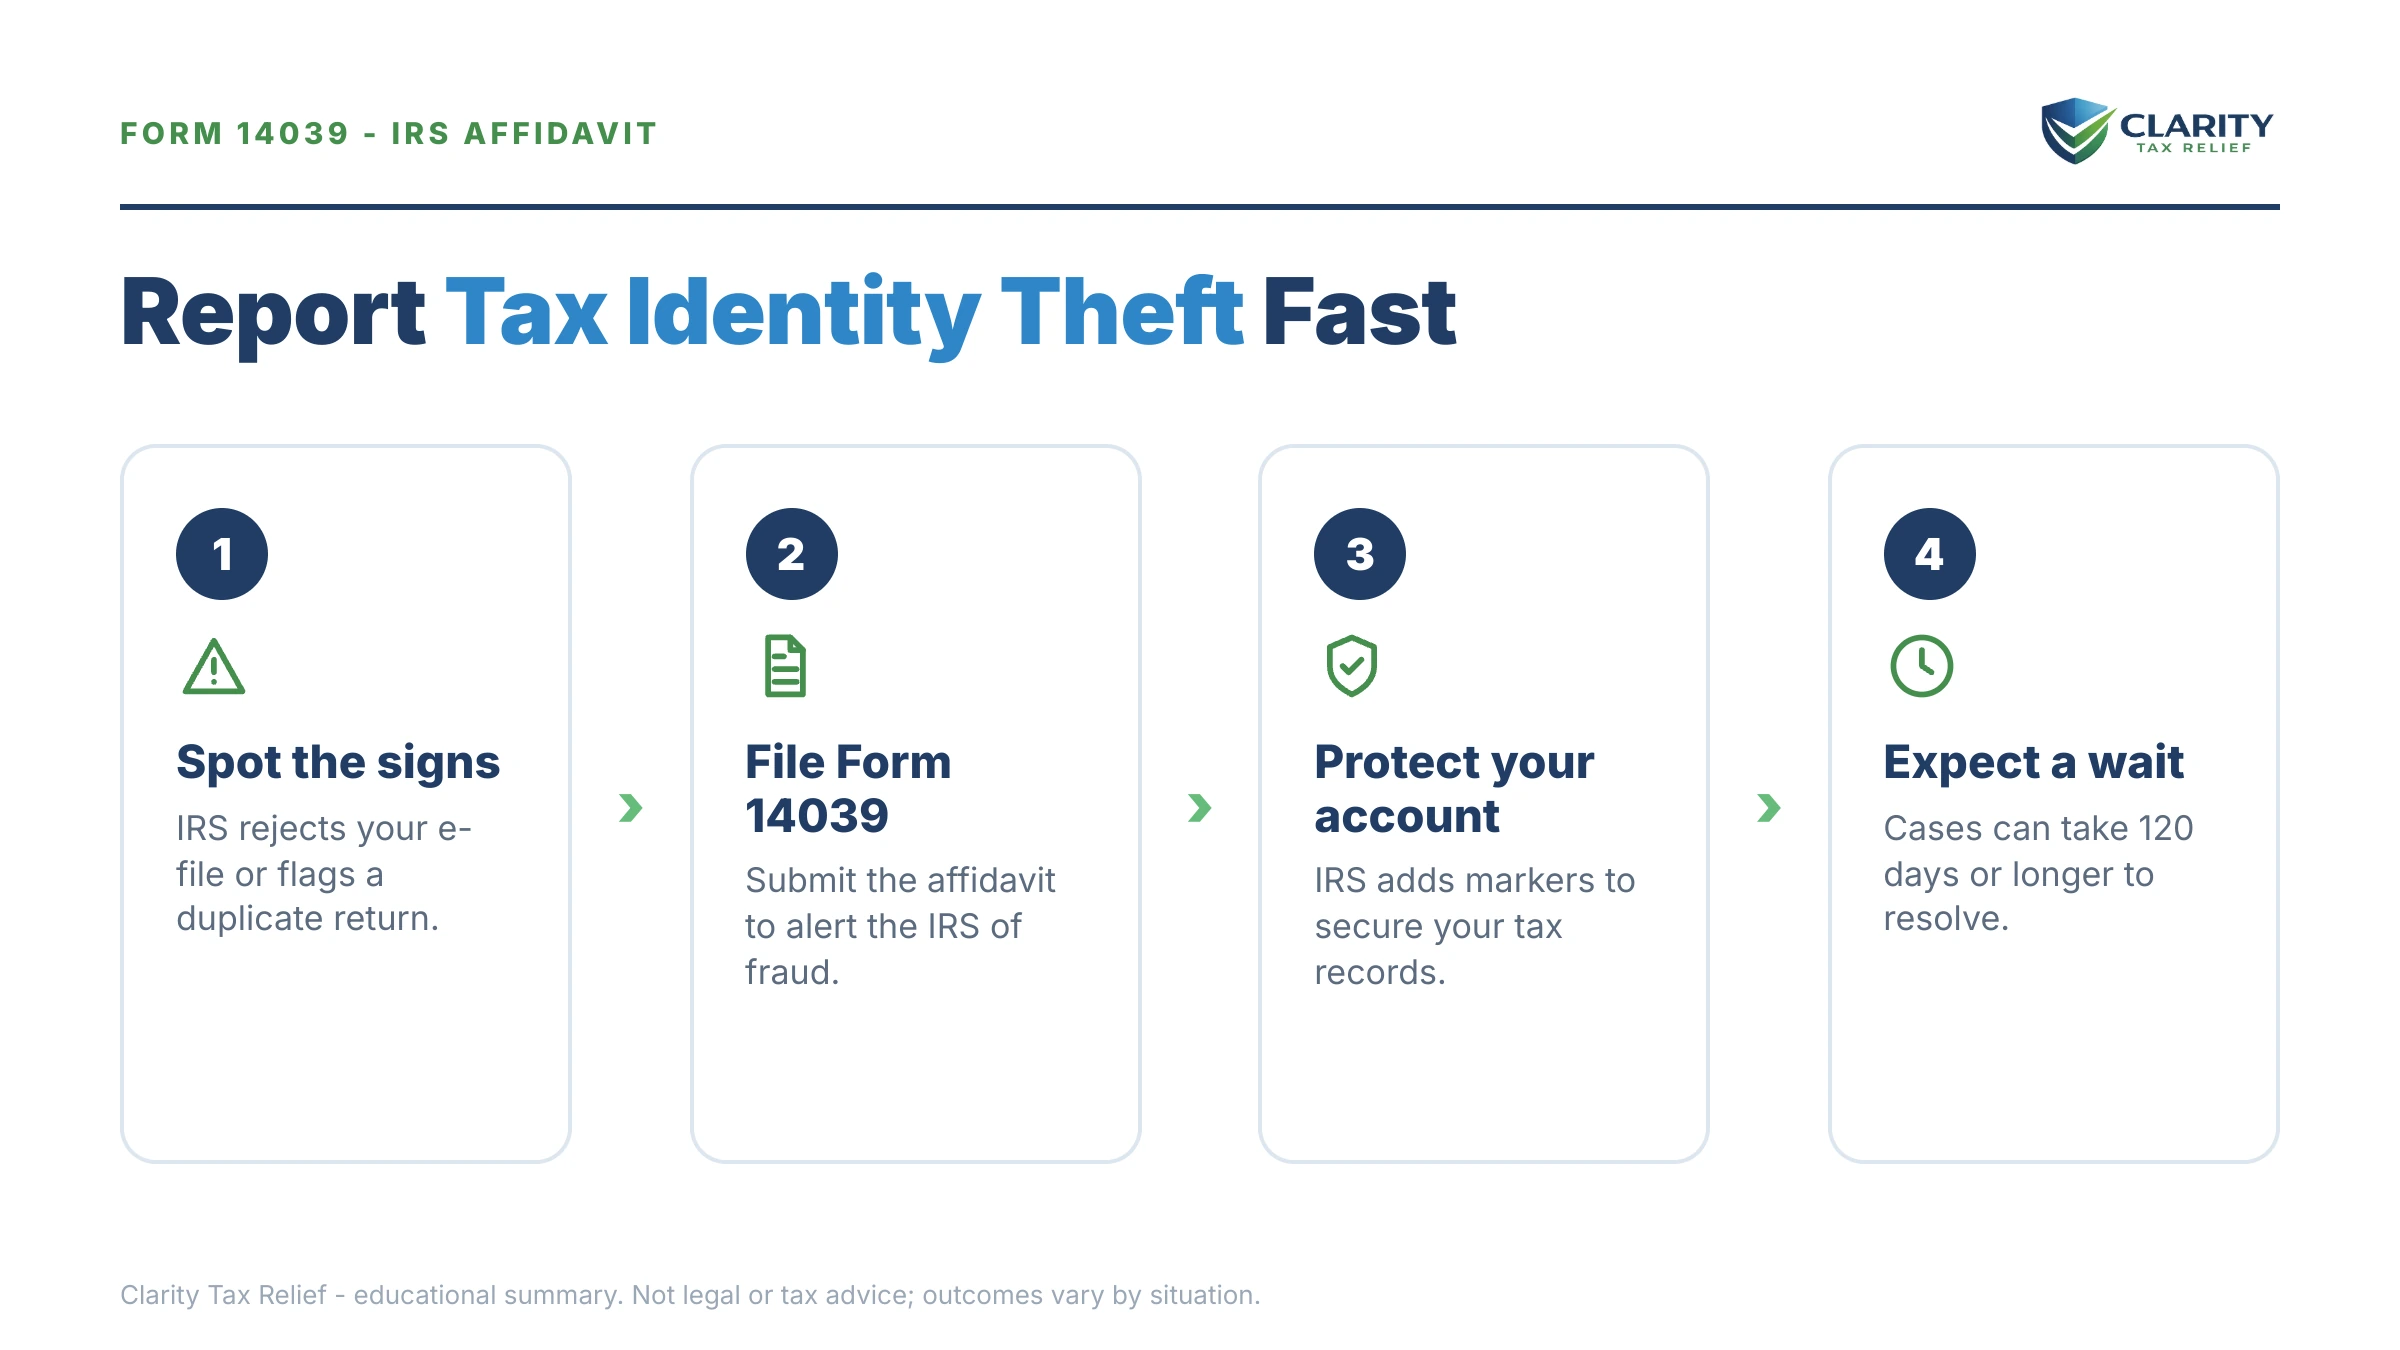
“If the IRS enrolled you into the IP PIN program due to being a confirmed victim of tax-related identity theft, we’ll mail you a CP01A Notice with your new IP PIN each year.”
— Get an identity protection PIN (IRS.gov)
When should you NOT file Form 14039?
The most common Form 14039 mistake is filing it in response to an identity verification letter, which can slow your refund down. Letters like the 5071C letter, the 4883C letter and the in-person 5747C mean the IRS already caught a suspicious return and paused it. The fix for those is the verification process printed in the letter. The affidavit adds nothing there.
File Form 14039 only when you are a confirmed victim or the IRS instructs you to. Here is the sorting logic in one place:
| Your situation | File Form 14039? | What to do |
|---|---|---|
| E-filed return rejected because a return already exists under your SSN | Yes | Paper-file your real return with the affidavit attached |
| 5071C, 4883C, or 5747C verification letter | No | Complete the verification in the letter first |
| Letter 4310C (the IRS spotted possible identity theft itself) | Usually no | Follow the letter; the IRS often opens the case on its own |
| Wage transcript shows an employer you never worked for | Yes | Check the employment-related box in Section B |
| Collection notices for a year you never filed | Yes | File the affidavit AND protect each notice deadline separately |
| Someone misused your business EIN | No; use Form 14039-B | File the business version of the affidavit instead |
One more non-trigger: wanting protection before anything happens. You do not need to be a victim to get an IP PIN (CP01A). Anyone can opt in at IRS.gov, and it blocks e-filed returns under your SSN without the PIN.
What happens if you ignore a fraudulent tax debt?
A fraudulent assessment collects exactly like a real one. The IRS computer does not know the difference until you tell it. This is the trap that catches victims: the identity-theft side of the IRS is human-staffed and slow, while the collection side is automated and never pauses on its own. In 2026, with the IRS workforce down roughly 27% from 2025 cuts, that gap is wider than ever.
- The assessment posts. A fraudulent refund return, or tax computed on wages someone earned under your SSN, becomes a live balance on your account.
- Billing notices begin. CP14, then CP501/CP503 reminders. Failure-to-pay penalties and interest compound monthly the whole way.
- CP504 arrives. The IRS can now seize your state tax refund, and a federal tax lien becomes a live risk.
- LT11 or Letter 1058, the final notice. A 30-day clock starts on your Collection Due Process rights.
- Levy. A bank levy freezes funds for 21 days before they are sent to the IRS; a wage levy is continuous until released. Meanwhile, any real refunds you are owed get frozen or offset year after year until the account is corrected.
Filing Form 14039 starts the correction. It does not stop this sequence by itself. Each collection notice has its own response window and its own right attached, and losing a right does not un-lose it later just because your identity-theft claim turns out to be true:
| What you're holding | Response window | The right at stake |
|---|---|---|
| E-file rejection (duplicate SSN) | Your filing deadline, plus any extension | Timely filing, and your refund claim expires 3 years after the due date |
| CP2000/CP2501 proposing tax on income that isn't yours | The response date printed on the notice | Disputing before the tax is ever assessed, the cheapest stage to win |
| CP3219A (90-day letter) | 90 days from the notice date | A U.S. Tax Court petition, the last chance to fight before paying |
| CP504 | The pay-by date printed on the notice | After it passes, your state refund can be levied |
| LT11 / Letter 1058 | 30 days from the notice date | A Collection Due Process hearing (Form 12153), which generally holds levies while it's pending |
The IRS is collecting a debt someone else created?
Send us the notices. An experienced tax professional will map which deadlines are live, whether Form 14039 is the right filing, and what stops the levy — free and confidential. If a final levy notice is in the stack, the 30-day appeal window is the clock we work against.
What are your options when the debt isn't yours?
Form 14039 corrects the account. Separate tools stop the collection while the correction happens. In most real cases you need two or three of these running at once:
- The affidavit itself. Once IDTVA confirms you are the real taxpayer, the fraudulent return or wage data is removed and the assessment built on it is reversed, including its penalties and interest. This is the only option that makes the debt go away for good, because the debt was never legally yours.
- A Collection Due Process hearing. If you are inside the 30-day window on an LT11 or Letter 1058, a timely Form 12153 CDP hearing request generally holds levy action on those periods while an appeals officer hears you. "This debt came from identity theft" is exactly the kind of issue CDP exists for.
- A collection hold by phone. The IRS Identity Protection Specialized Unit (800-908-4490) and the collection function can place holds on an account with an open identity-theft claim. Holds are neither automatic nor permanent. You have to ask, document, and follow up.
- The Taxpayer Advocate Service. If a levy is about to hit and it would leave you unable to pay rent or basic bills, Form 911 asks TAS to intervene on hardship grounds. Identity-theft victims stuck between a slow case and an active levy are a core TAS scenario.
- Reconsideration of a defaulted assessment. If the debt came from a CP2000 you never saw or a return the IRS filed for you, and the response deadlines already passed, the assessment can still be reopened with proof. It takes longer than responding on time would have.
- Normal payment options, for the real slice only. If part of the balance is yours, a short-term plan (up to 180 days, no setup fee) or a monthly installment agreement handles that piece. Get the fraudulent portion abated first, so you are not financing someone else's tax.
If a wage levy is already in motion while you sort this out, you can estimate what it could take from each paycheck with our IRS Wage Garnishment Calculator. The exempt amount is often far less than a month's rent.
A worked example: the $16,400 phantom debt
Say the IRS is collecting $16,400 for 2023 even though you filed a clean return that year on your $38,000 salary. Here is how a debt like that gets built without you. Someone worked two jobs under your SSN. Their employers reported $54,000 in wages to your record. The IRS mailed a CP2000 to an old address proposing tax on the "unreported" income, and it defaulted. The assessment posted as roughly $10,900 in tax + $2,180 in an accuracy-related penalty + $3,320 in failure-to-pay penalties and interest = $16,400.
The wrong instinct is to treat it like a normal bill. $16,400 spread over a 72-month installment agreement is about $228 a month before accruing interest, six years of payments on wages you never earned. The right sequence: file Form 14039 with the employment-related box checked, submit proof the income cannot be yours (your real W-2, your lease showing you lived nowhere near the phantom employer), and if an LT11 has arrived, file Form 12153 inside the 30 days. When the identity-theft determination comes through, the assessment is abated. The correct outcome is $0 and the $228 a month never starts.
How to file Form 14039, step by step
- Confirm the fraud on your IRS records. Pull your account transcript and wage and income transcript for the year in question, and compare every employer and filing against your real life. Save copies of anything you do not recognize.
- Complete Form 14039. Check the Section B box that matches your situation (a return filed with your SSN, wages earned under your SSN, or both) and describe what happened in plain, dated facts.
- Submit it the right way. If your e-file was rejected as a duplicate, print your real return, attach Form 14039, and mail both together. Otherwise submit it electronically through IRS.gov or IdentityTheft.gov, or mail or fax it per the form instructions.
- Protect every collection deadline separately. Filing the affidavit does not pause collection. If you hold an LT11 or Letter 1058, file Form 12153 within 30 days. If you hold a CP2000 or CP3219A, respond by the date printed on it.
- Lock your account for future years. Opt into the IP PIN program at IRS.gov, place a credit freeze with all three bureaus, and file an FTC report at IdentityTheft.gov.
- Track the case until you get a closing letter. Call the IRS Identity Protection Specialized Unit at 800-908-4490 for status, and keep filing your real returns on time while the case is open.
What happens after you file Form 14039?
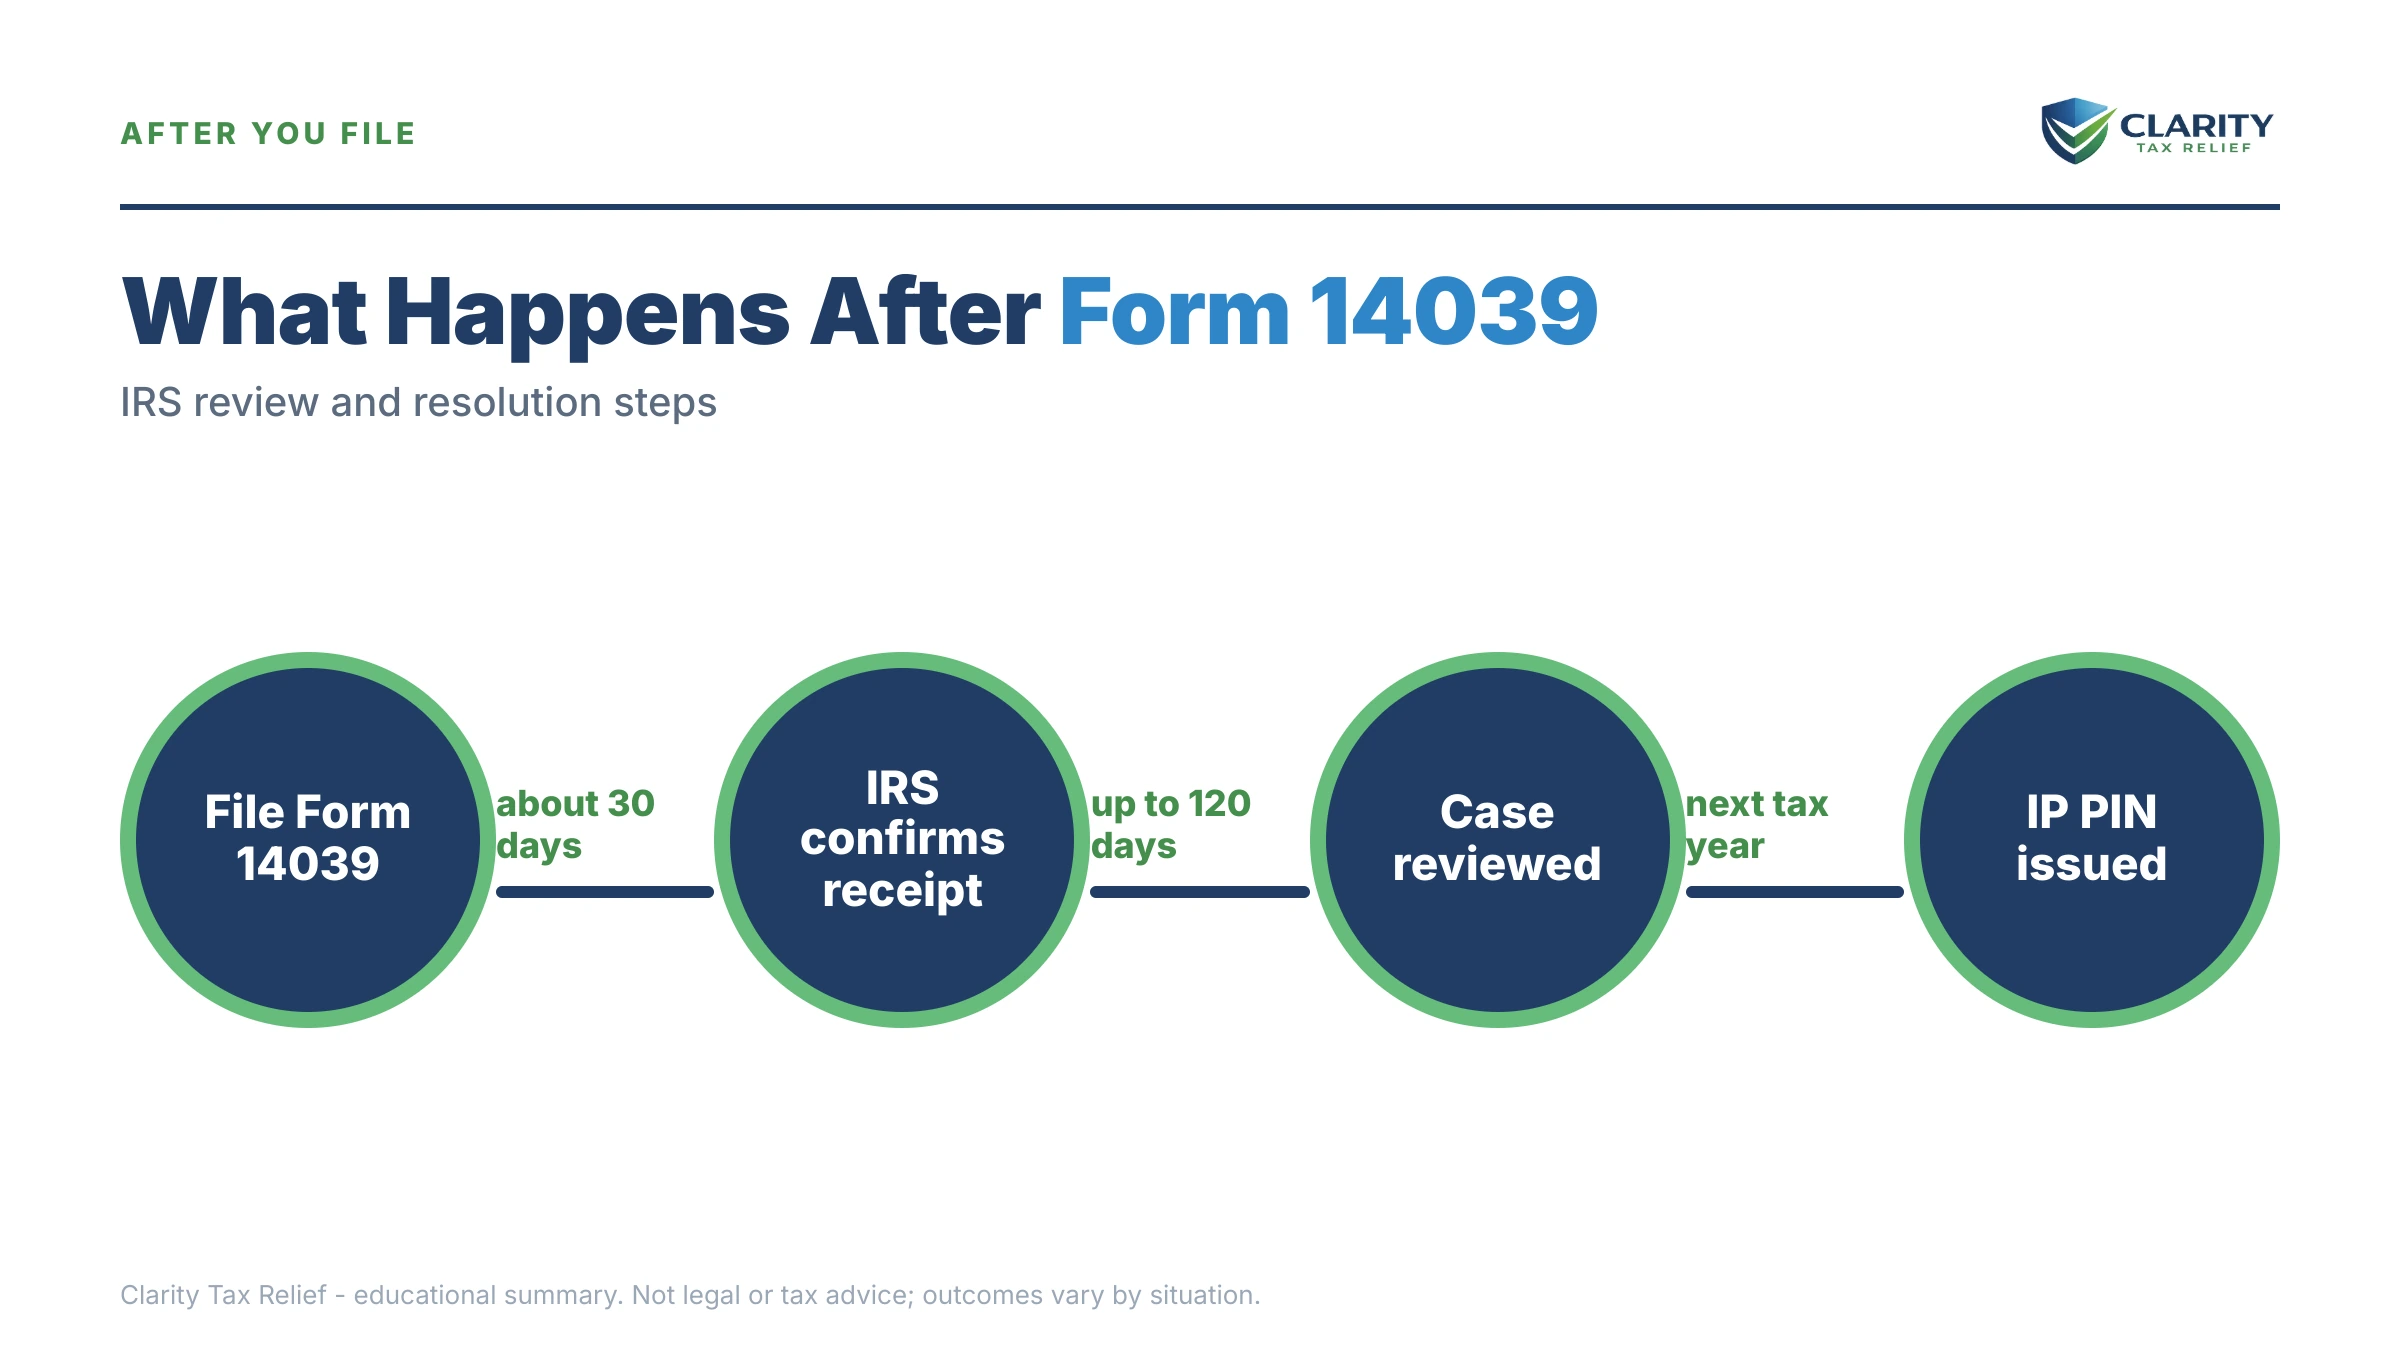
After you file, the case goes to the IRS Identity Theft Victim Assistance unit. The collection side of the IRS does not automatically find out. Expect an acknowledgment letter, then a long stretch of quiet while a caseworker verifies you are the real taxpayer, strips the fraudulent return or wage data from your account, reverses any assessment built on it, and releases whatever legitimate refund got trapped along the way.
Be realistic about the timeline. The National Taxpayer Advocate has reported average resolution times stretching well past a year in recent filing seasons, and 2026 staffing cuts have not helped. That is why the collection-defense moves above run in parallel. You cannot let a levy land while the correction crawls through the queue.
When the case closes, you get a letter confirming the resolution. The IRS enrolls you in the IP PIN program, and a new six-digit PIN arrives by CP01A notice each year. Your SSN cannot be used to e-file without it. Keep filing every return on time while the case is open; the fraud is the IRS's problem to fix, and missed filings become yours.
Red flags and what to check before you mail anything
- The letter in your hand is a 5071C, 4883C, or 5747C. That is a verification letter. Do the verification it describes; an affidavit here only slows your refund.
- An LT11 or Letter 1058 is in the stack. Count 30 days from its date. If that window is still open, Form 12153 goes out before anything else.
- A CP2000 or CP3219A has a printed date. Respond by that date even though the income is not yours. The CP3219A gives 90 days, and after that the IRS's number becomes the legal debt.
- The CP504 pay-by date has passed or is close. Your state refund is exposed once it does.
- The wage transcript shows an employer you never worked for. Check the employment-related box in Section B, and gather proof you were somewhere else.
- The misused number is a business EIN. Form 14039 is the wrong form; Form 14039-B is the business version.
- Part of the balance is real. Keep the real slice and the fraudulent slice separate, and get the fraudulent portion abated before you finance the rest.
Can you handle this yourself, or does help change the outcome?
Plenty of Form 14039 situations are DIY. If your e-filed return bounced as a duplicate and there are no collection notices, your only loss is a delayed refund. Paper-file with the affidavit attached, opt into the IP PIN, freeze your credit, and wait it out. The filings are free, and no professional will meaningfully speed up the IDTVA queue for a clean, single-year refund case. If money is tight, a low income taxpayer clinic can also represent identity-theft victims at no charge if you qualify.
Experienced help changes outcomes when collection is already moving or the fraud is tangled: a levy notice with a live 30-day clock, multiple years of phantom assessments, employment-related fraud mixed into your real income so only part of the balance is bogus, a defaulted CP2000 or IRS-filed return that needs to be reopened with evidence, or business EIN misuse. In those cases the win comes from sequencing the CDP request, the hold, the proof package and the abatement so nothing gets seized in the meantime. A Form 2848 power of attorney lets a professional work the identity-theft unit and the collection function for you at the same time.
Terms on your Form 14039 case, decoded
- IDTVA: Identity Theft Victim Assistance, the IRS unit that works Form 14039 cases and corrects victim accounts.
- Duplicate-return rejection: the e-file error you get when a return has already been filed under your SSN for that year.
- Employment-related identity theft: someone using your SSN to work; their wages land on your IRS record even though no fake return was filed.
- IP PIN: a six-digit Identity Protection PIN, changed yearly, required to e-file under your SSN once you are enrolled.
- CP01A: the annual notice that delivers each year's new IP PIN.
- CDP hearing: Collection Due Process, the formal appeal an LT11 or Letter 1058 triggers. Requesting it within 30 days generally holds levy action while it is heard.
The bottom line on Form 14039
Form 14039 is the right filing when a return or wages went through under your SSN and the IRS is treating the result as yours. It is the wrong filing when the letter in your hand is asking you to verify your identity. The affidavit fixes the account; it does nothing to the collection clock. So file it, then protect each notice deadline on its own, ask for a hold, and keep filing real returns on time until the closing letter arrives.
Form 14039 questions, answered
How long does it take the IRS to resolve a Form 14039 case?
Longer than most victims expect. The IRS has historically told victims to plan on several months. The National Taxpayer Advocate has reported average identity-theft case resolution times stretching well past a year in recent filing seasons. Your legitimate refund is paid after the case closes, so file the affidavit as early as possible and use the 800-908-4490 line to check status rather than waiting silently.
Can I file Form 14039 online?
Yes. You can complete and submit Form 14039 electronically through IRS.gov, or report the theft at the FTC's IdentityTheft.gov, which can transmit the affidavit to the IRS for you. The one exception: if your e-filed return was rejected as a duplicate, print your real return and mail it with the affidavit attached so both are processed together.
Do I need a police report to file Form 14039?
No. The affidavit itself, signed under penalty of perjury, is what the IRS requires. A police report and an FTC identity-theft report are still worth getting — credit bureaus, banks, and some state tax agencies ask for them — but the IRS will open your case without one.
Will filing Form 14039 stop an IRS levy?
Not automatically. Collection systems and identity-theft casework run on separate tracks, so a levy can proceed while your affidavit waits in the queue. To stop enforcement you need a separate move: a Collection Due Process hearing request within 30 days of an LT11, a collection hold requested by phone, or Form 911 to the Taxpayer Advocate if the levy creates immediate hardship.
Should I file Form 14039 if I got a 5071C or 4883C letter?
No — verify first. Those letters mean the IRS caught a suspicious return and paused it. The fix is the verification process described in the letter, online, by phone, or in person. File Form 14039 only if verification confirms the return wasn't yours and the IRS tells you to, or if you find other fraud on your account.
What's the difference between Form 14039 and an IP PIN?
Form 14039 reports theft that already happened; an IP PIN prevents the next one. The IP PIN is a six-digit code that changes each year, and no return can be e-filed under your SSN without it. Once your identity-theft case resolves, the IRS enrolls you automatically and mails a CP01A with your new PIN each year, and anyone can opt in voluntarily at IRS.gov without being a victim first.
Do I still file my real tax return while the case is open?
Yes — never skip a filing deadline because of identity theft. If e-file is blocked by the fraudulent return, file on paper with Form 14039 attached. Your legitimate return keeps you clear of failure-to-file penalties, which run ten times higher than late-payment penalties — though in months where both apply, the failure-to-file portion drops to 4.5 percent (5 percent combined) — and it preserves your refund claim, which expires three years after the original due date.
What is Form 14039-B?
It's the business version of the affidavit, used when someone misuses a company's Employer Identification Number — filing fake business returns, reporting phantom wages, or claiming credits under the EIN. If your business received notices for returns it never filed, file Form 14039-B rather than the individual form, and check whether fraudulent payroll filings created exposure that needs its own response.
Your next 24 hours
- Find the tax year and notice date on every IRS letter in the stack. The notice date starts each response window, if any letter says LT11 or Letter 1058, count 30 days forward and write that date down.
- Gather your proof: your real return for the affected year (or proof you weren't required to file), your W-2s, a government ID, your lease or utility bill for that year, and every IRS notice you've received.
- Get the free case review. The 2-minute form or (888) 825-7779. If the IRS is collecting a debt built on identity theft, we'll map the affidavit, the collection defense. The deadlines in one plan. Before a levy hits the account your rent depends on.
Primary sources: the IRS's About Form 14039 page, its Identity Theft Central hub. The FTC's IdentityTheft.gov recovery portal.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.