
1099 & Platform Income
The 1099-K $20,000 Threshold in 2026: What Changed, and Why Your Old Tax Debt Didn't Go Away
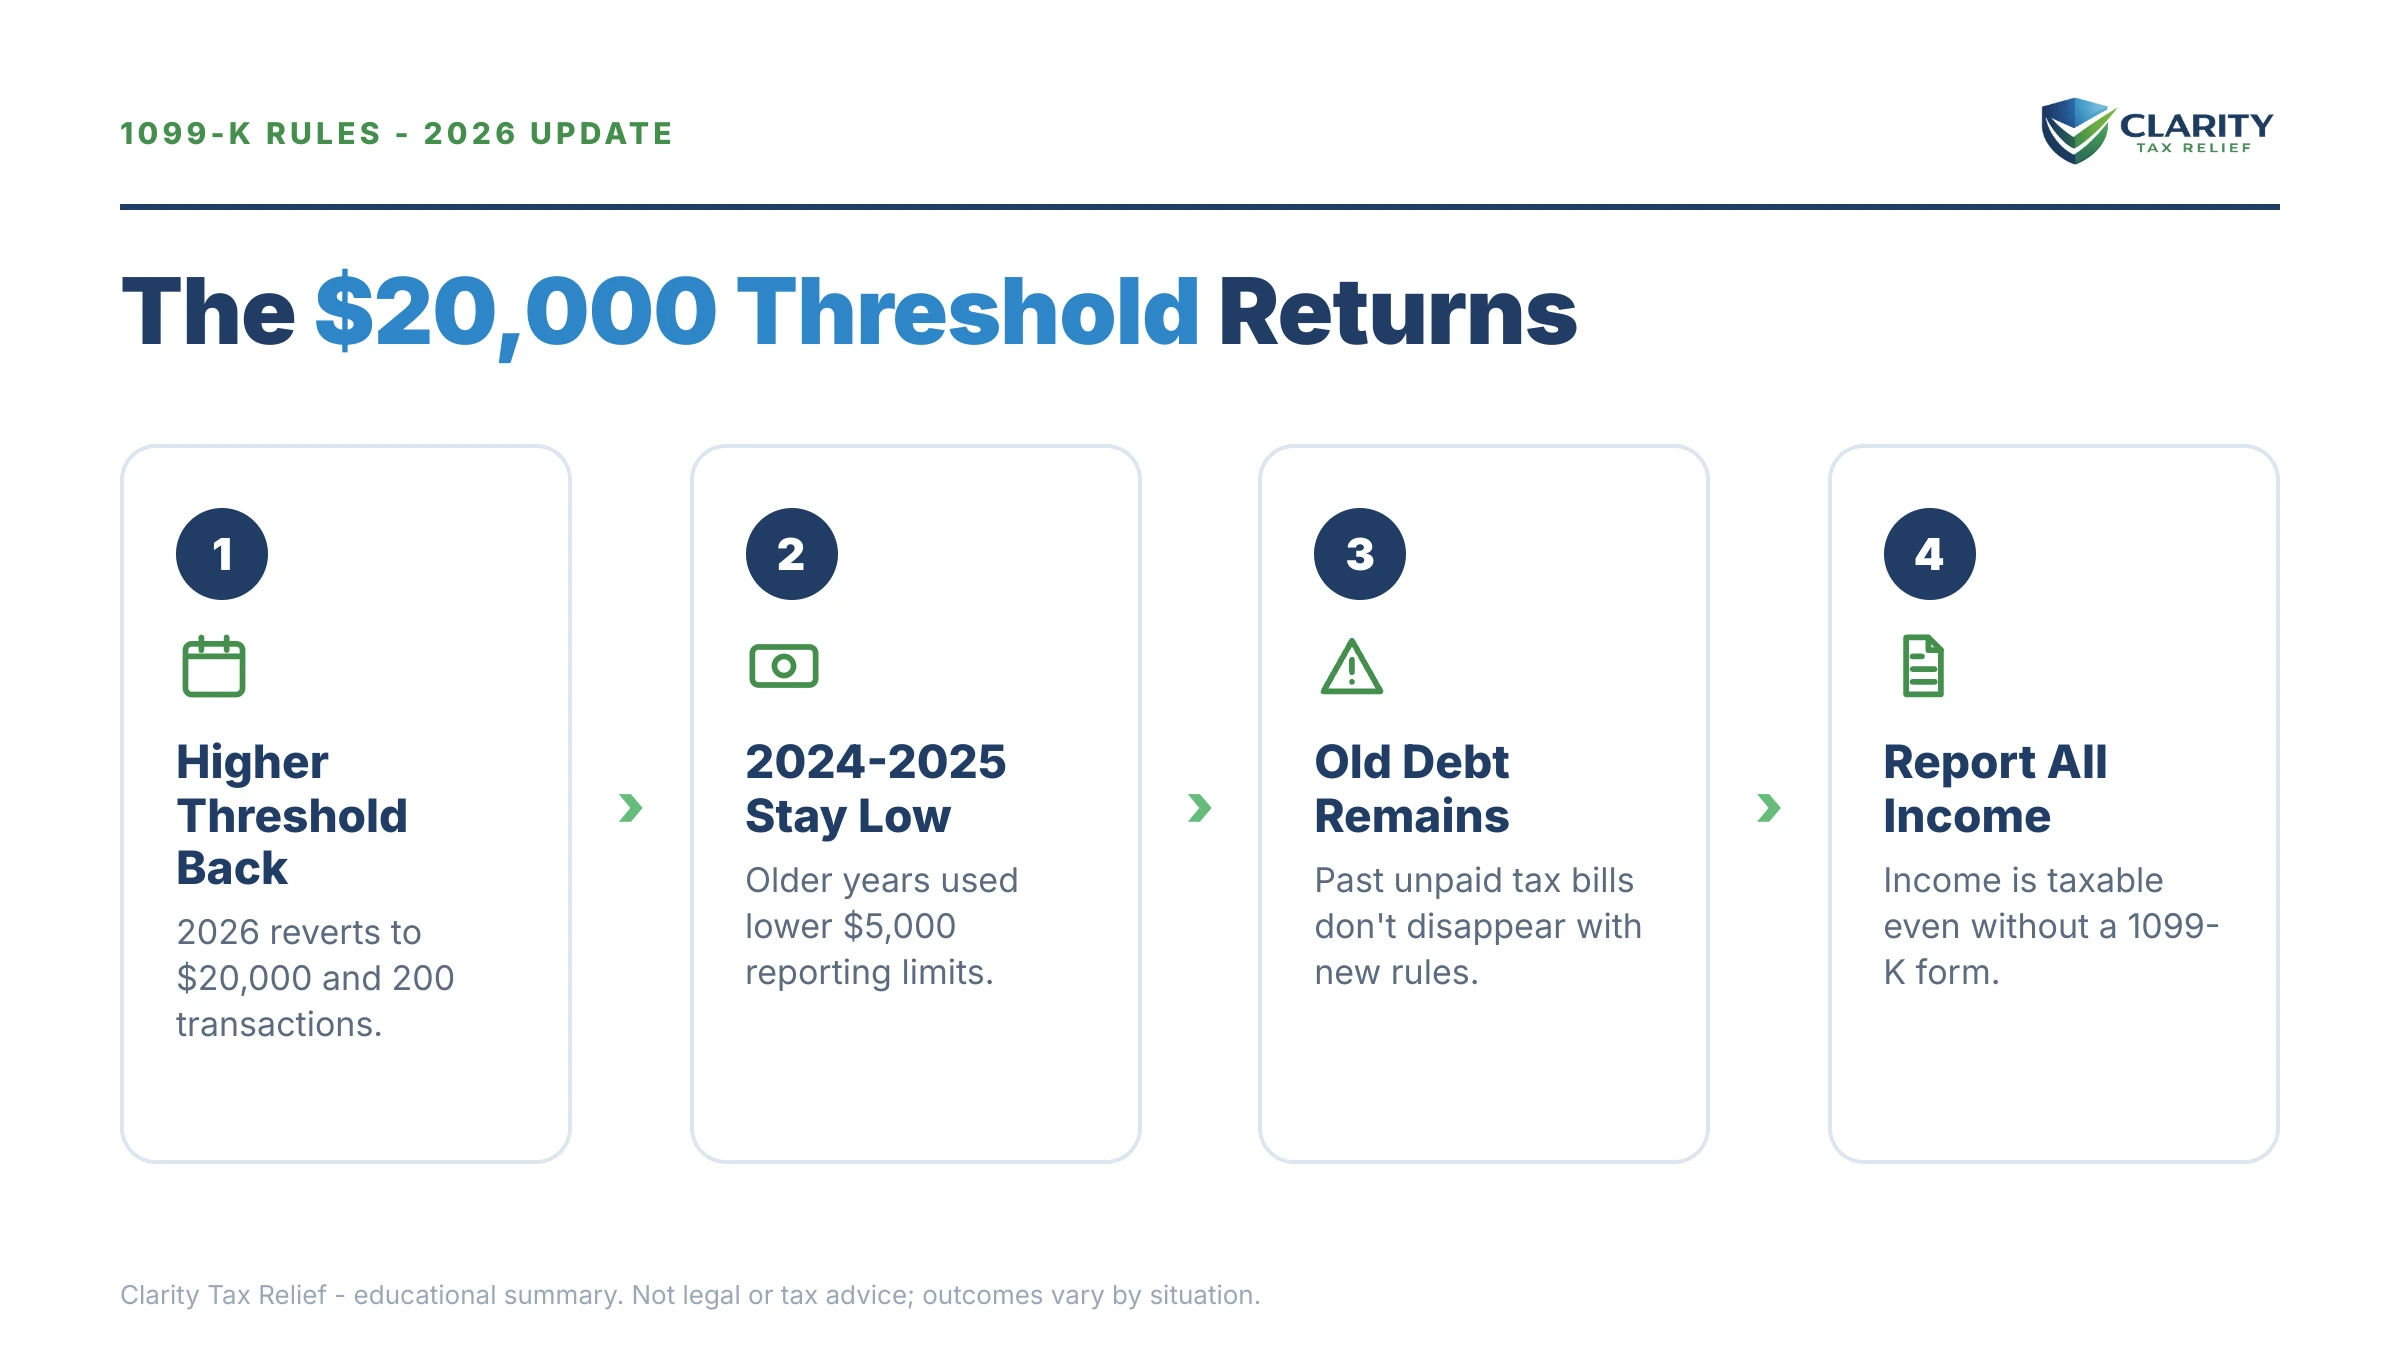
The short answer: the 1099-K threshold for 2026 is back to $20,000 AND more than 200 transactions — the $600 rule was repealed before it ever fully took effect. But the threshold only controls who gets a form. Your platform income was always taxable, and tax debt already assessed from earlier years remains fully collectible.
This guide covers both halves of the 1099-K problem: how the $20,000 threshold works for 2026 payments, and what to do if the IRS is already collecting on platform income from the years before the reversal. Maybe you saw the headline ("1099-K threshold restored to $20,000") and hoped the balance from your selling years would quietly disappear with the $600 rule. Instead, the newest IRS letter on your counter threatens a levy on the same checking account your rent comes out of. Those two things are not a contradiction, and neither one is hopeless. The reporting rules changed. The collection rules did not, and the collection rules have fixes built into them.
The image below shows what a Form 1099-K looks like and where the gross-payment figure that drives all of this sits.
The real clock: the $20,000 threshold changes which forms go out in January 2027. It pauses nothing on debt you already owe. The failure-to-pay penalty adds 0.5% per month and interest compounds daily until the balance is resolved. And if you are holding an LT11 final notice, the 30-day deadline printed on it is real.
What does the 1099-K $20,000 threshold mean for 2026?
For payments received during 2026, a payment app or online marketplace must send you Form 1099-K only if your gross payments for goods and services exceed $20,000 across more than 200 transactions on that platform. Both parts of the test have to be met. A seller who takes in $30,000 across 150 transactions, or $15,000 across 400, generally falls outside the federal reporting requirement.
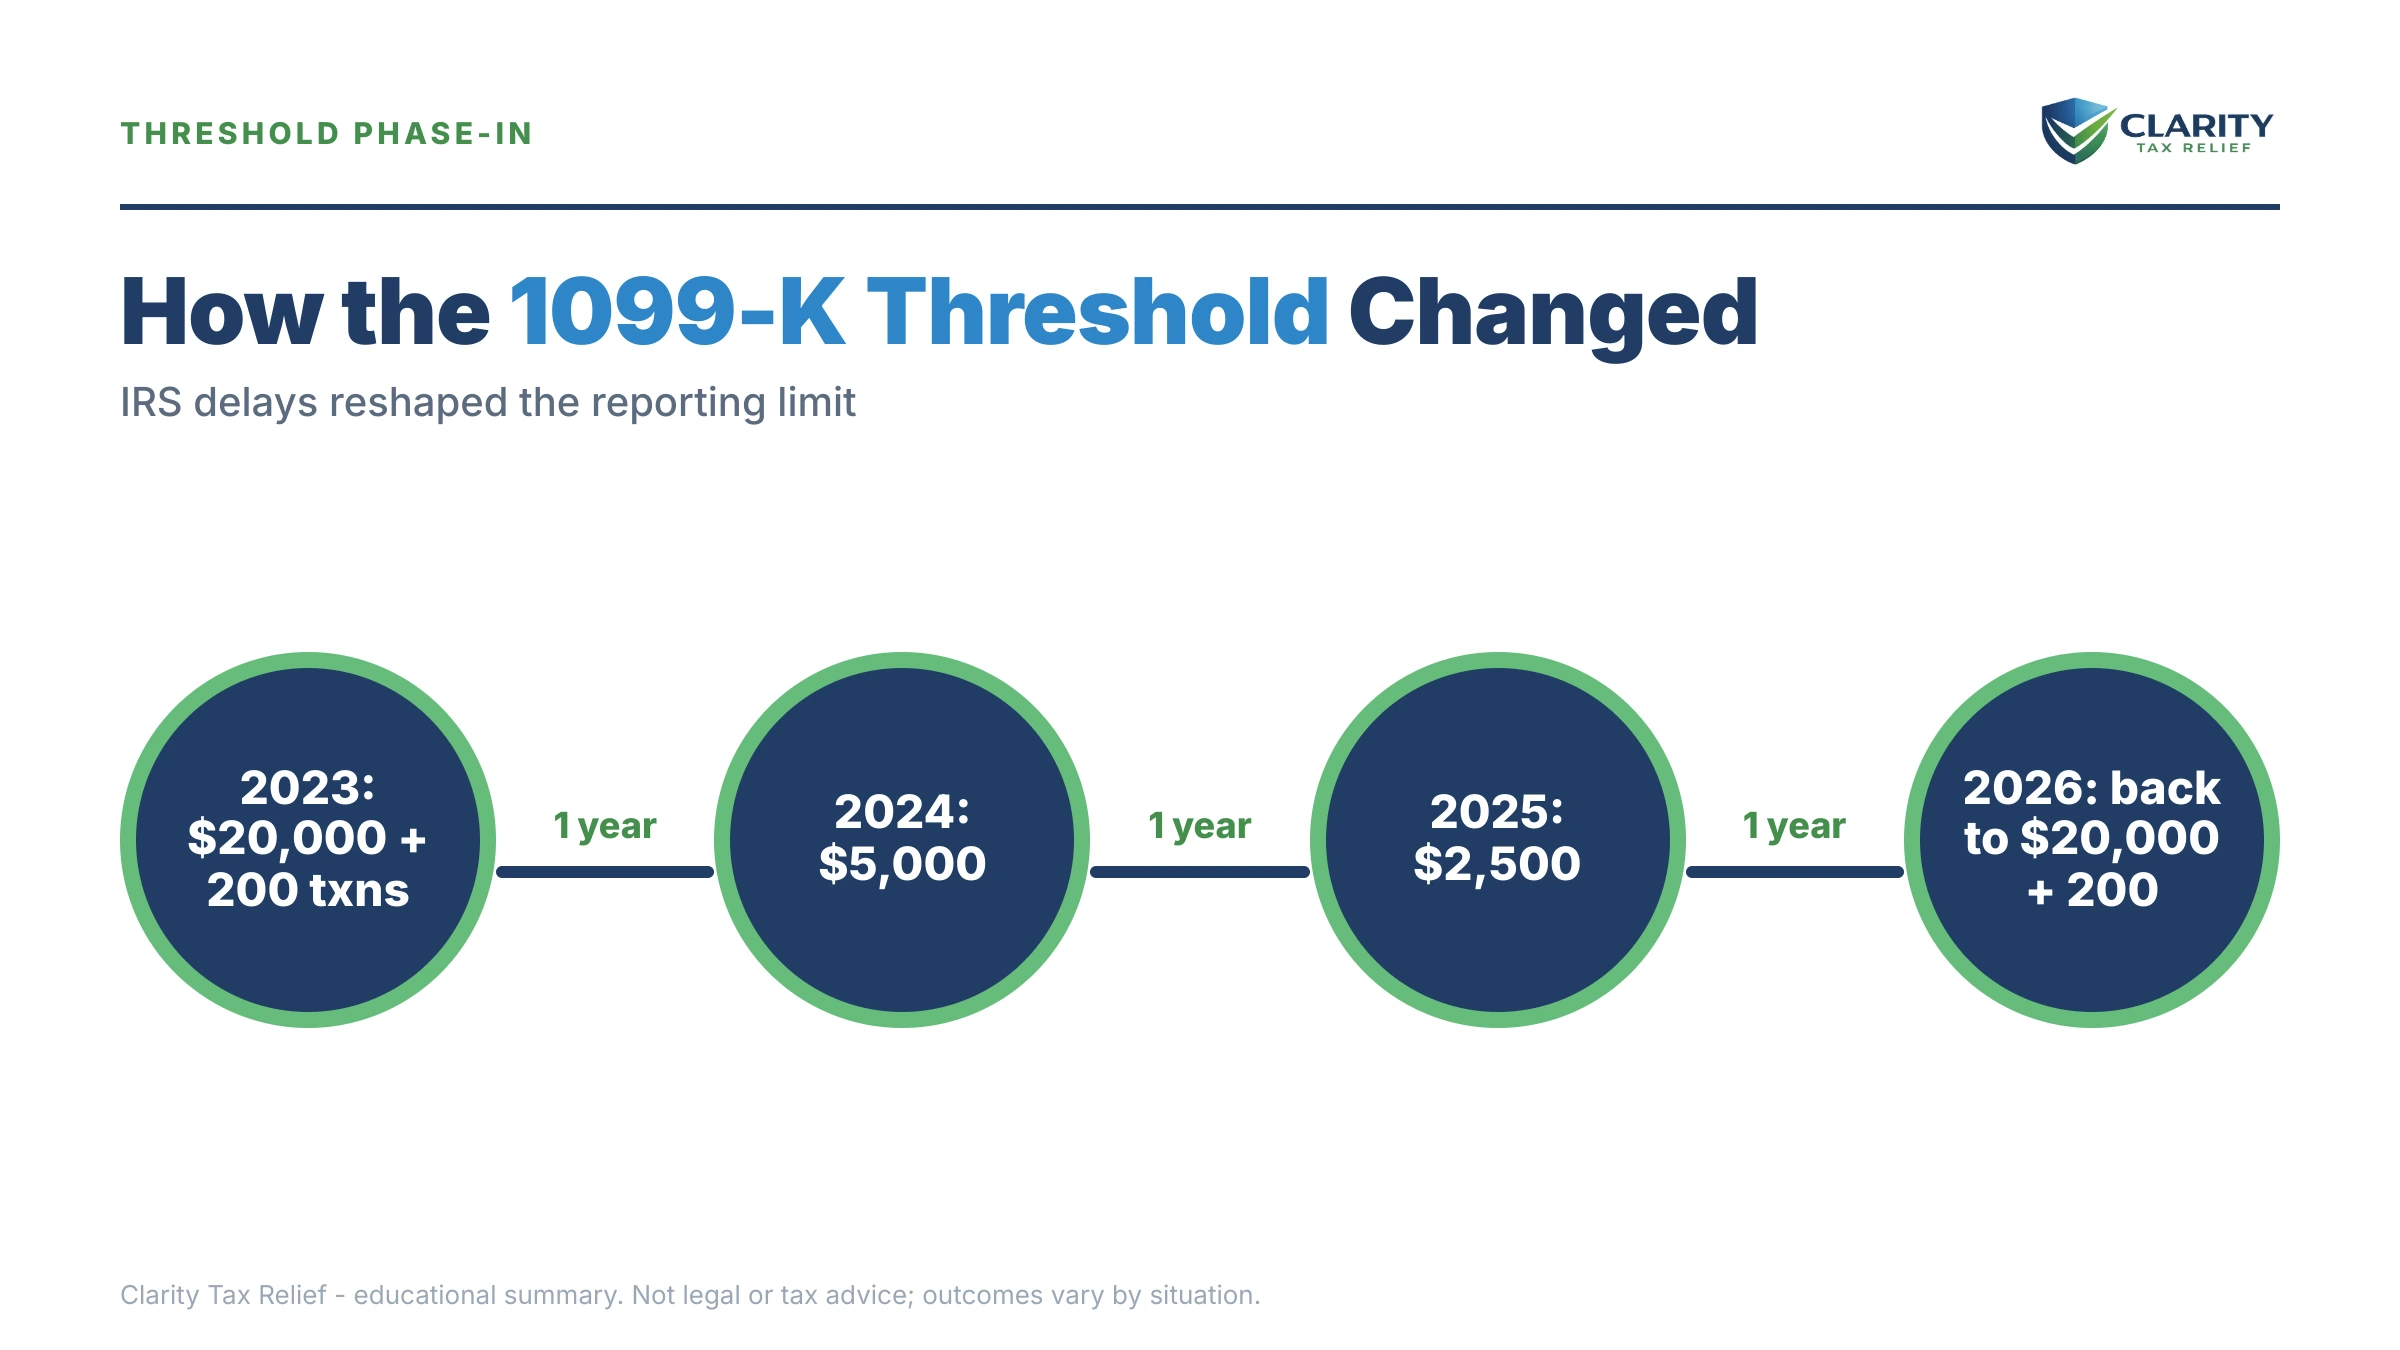
How we got here matters, because it explains why so many people are confused about what they owe. Congress dropped the threshold to $600 with no transaction minimum in 2021. The IRS delayed that rule for 2022 and again for 2023, then applied a transitional $5,000 threshold to 2024 payments, which is why millions of casual sellers got their first-ever 1099-K in early 2025. In 2025, the One Big Beautiful Bill tax changes repealed the $600 rule entirely and restored the original $20,000-and-200-transaction standard.
Three details trip people up even under the higher threshold:
- The test is per platform. $18,000 on eBay plus $12,000 on Etsy may produce no federal forms at all, but all $30,000 of profit-generating activity is still reportable by you.
- The form reports gross payments. Box 1a includes platform fees, shipping the buyer paid, and even refunded orders. Your taxable profit is almost always far lower than the number on the form.
- Some states set lower thresholds. A handful of states require platforms to issue 1099-Ks at much lower dollar amounts, so you may still receive a form for 2026 even under $20,000. Check your state revenue agency's rules rather than assuming the federal line applies.
| Payments received in | Federal threshold that applied | Forms mailed |
|---|---|---|
| 2021 and earlier | $20,000 and more than 200 transactions | Through Jan 2022 |
| 2022 | $600 rule scheduled; IRS delayed it; $20,000/200 applied in practice | Jan 2023 |
| 2023 | Delayed again; $20,000/200 applied in practice | Jan 2024 |
| 2024 | $5,000 transitional threshold; millions of first-time forms | Jan 2025 |
| 2025 | $20,000 and 200 transactions (restored by law) | Jan 2026 |
| 2026 | $20,000 and 200 transactions | Jan 2027 |
“Reminder: Whether or not you receive a Form 1099-K, you must still report any income on your tax return. This includes payments for any goods you sell (including personal items such as clothing or furniture sold at a gain) or services you provide.”
— Understanding your Form 1099-K (IRS.gov)
Why doesn't the higher threshold change what you owe?
The 1099-K threshold has never controlled whether income is taxable. It controls whether a platform must report it. Profit from selling goods or services is reportable from the first dollar, form or no form. The threshold reversal changed the paperwork and left the tax law underneath it alone.
That cuts in two directions. Going forward, fewer casual sellers will get forms, but self-employed sellers, resellers, and gig workers still owe income tax and self-employment tax on their profit, and skipping it invites trouble the moment the IRS gets data from any source. Looking backward, every 1099-K a platform already filed (especially the 2024 wave under the $5,000 rule) is sitting in the IRS's document-matching system. When the gross amount on a filed 1099-K does not appear anywhere on your return, the system generates a CP2000 notice proposing tax on the mismatch. If you never respond, that proposal hardens into an assessed debt.
Once assessed, the balance is collectible for 10 years from the assessment date. The collection statute does not care what the reporting threshold is now. If you got a 1099 you weren't expecting in a past year and set it aside, that is very likely how you ended up here.
One good piece of news. If you sold your own used belongings (furniture, electronics, clothes) for less than you originally paid, that is not taxable income even when it appeared on a 1099-K. Losses on personal items are not deductible. They are not income either. Business sellers report profit on Schedule C; personal-item sales with gains go on Form 8949. Many old assessments taxed the full gross figure because no return was ever filed to say otherwise, which means the debt itself may be overstated, and that is fixable.
What happens if you ignore old 1099-K debt?
An assessed balance from a lower-threshold year moves through the IRS's automated collection sequence no matter what the current reporting rules say. Each stage arrives with more enforcement power than the last:
- CP2000 / assessment. The matching notice proposes tax on the unreported 1099-K amount. No response, and it becomes a legal debt.
- CP14. The first bill for the assessed balance, now with penalties and interest attached.
- CP501 / CP503. Reminder notices while the balance compounds monthly.
- CP504. Intent to levy your state tax refund; a federal tax lien becomes a live possibility.
- LT11 / Letter 1058. The final notice. The LT11 notice starts a 30-day clock and your Collection Due Process rights (Form 12153). After it passes, levies can begin.
- Levy. A bank levy freezes your funds for 21 days before they are sent to the IRS; a wage levy is continuous until released.
Here is the part that matters if you rent. With no house to lien, IRS enforcement goes straight for cash: your bank account, your paycheck, and if you are still selling, even payments owed to you as a contractor. A balance over $66,000 (the 2026 figure) can be certified to the State Department, which can deny or revoke your passport for tax debt. The IRS's workforce shrank roughly 27% in 2025. These notices and levies come from automated systems that never stopped running.
| Notice or event | Your window | What you lose if it passes |
|---|---|---|
| CP2000 proposal | Typically 30 days from the notice date | The easy chance to correct the numbers before assessment |
| CP504 | 30 days | Your state tax refund can be seized |
| LT11 / Letter 1058 | 30 days | Collection Due Process hearing rights (Form 12153); levies can begin |
| Bank levy served | 21-day hold on frozen funds | The money leaves your account for good |
Being collected on for old 1099-K income?
If a levy is in motion, or an LT11's 30-day window is running, the order you act in decides what you keep. An experienced tax professional will review your notices and transcripts free and map the fastest release path. Penalties and interest accrue every month you wait.
Your options for 1099-K tax debt from a lower-threshold year
Every assessed 1099-K balance has at least one workable resolution. Often the first move is correcting an assessment that taxed your gross sales as pure profit, and payment comes after that. The broader mechanics of each program live in our guide to how to settle tax debt yourself. Here is how they map to this specific situation:
| Option | Who it fits | Cost and notes |
|---|---|---|
| Correct the assessment | The IRS taxed gross 1099-K totals with no costs, fees, or personal-item losses subtracted | File the original or amended return, or request audit reconsideration, often the single biggest reduction available |
| Short-term plan | You can pay in full within 180 days | $0 setup; interest and the 0.5%/month penalty continue, but enforcement stops |
| Streamlined installment agreement | Balance of $50,000 or less | Up to 72 months, set up online without full financial disclosure |
| Non-streamlined plan | Balance over $50,000 | Requires financial disclosure (Form 433-F); see IRS payment plan over $50,000 |
| Currently Not Collectible | Income covers only allowable living expenses; common for renters on tight budgets | Collection pauses; the debt and accruals remain. See Currently Not Collectible status |
| Offer in Compromise | Assets plus future income can't cover the balance | $205 fee and 20% down on lump-sum offers (both waived with low-income certification); the IRS accepted roughly 1 in 5 offers in FY2024 |
| Penalty relief | Clean compliance for the prior 3 years, or reasonable cause | First-Time Abate removes penalties, not tax; automatic penalty exemption (AEP) begins replacing it in summer 2026 |
A worked example: $76,400 of assessed 1099-K debt
Say you resold sneakers and electronics across 2022 and 2023, well past the $20,000/200 line, and your platforms reported $118,000 in gross 1099-K payments. You never filed Schedule Cs, and the CP2000s went unanswered. The IRS assessed tax on the full gross amount, as if every dollar were profit. With income tax, self-employment tax, failure-to-file and failure-to-pay penalties, and daily-compounding interest, the balance today reads $76,400. (You can rough out how much of a balance like that is penalties and interest with our Penalty & Interest Calculator.)
At $76,400, three things are true at once: you are over the $50,000 line for a streamlined online plan, over the $66,000 passport-certification threshold, and squarely in levy territory once an LT11's 30 days run out. The assessment is built on a fiction, though. Suppose your inventory costs, platform fees, and shipping totaled $81,000. Your real profit was about $37,000, not $118,000. Filing accurate returns for those years forces the IRS to recompute the tax on real profit. If, in this hypothetical, the corrected balance lands near $29,000, a streamlined 72-month agreement becomes available at roughly $29,000 ÷ 72 ≈ $403/month before ongoing accruals, and entering that agreement is generally what gets a levy released and the passport certification reversed. Same taxpayer, same history. The order of operations changed everything.
How to respond if you owe tax on 1099-K income, step by step
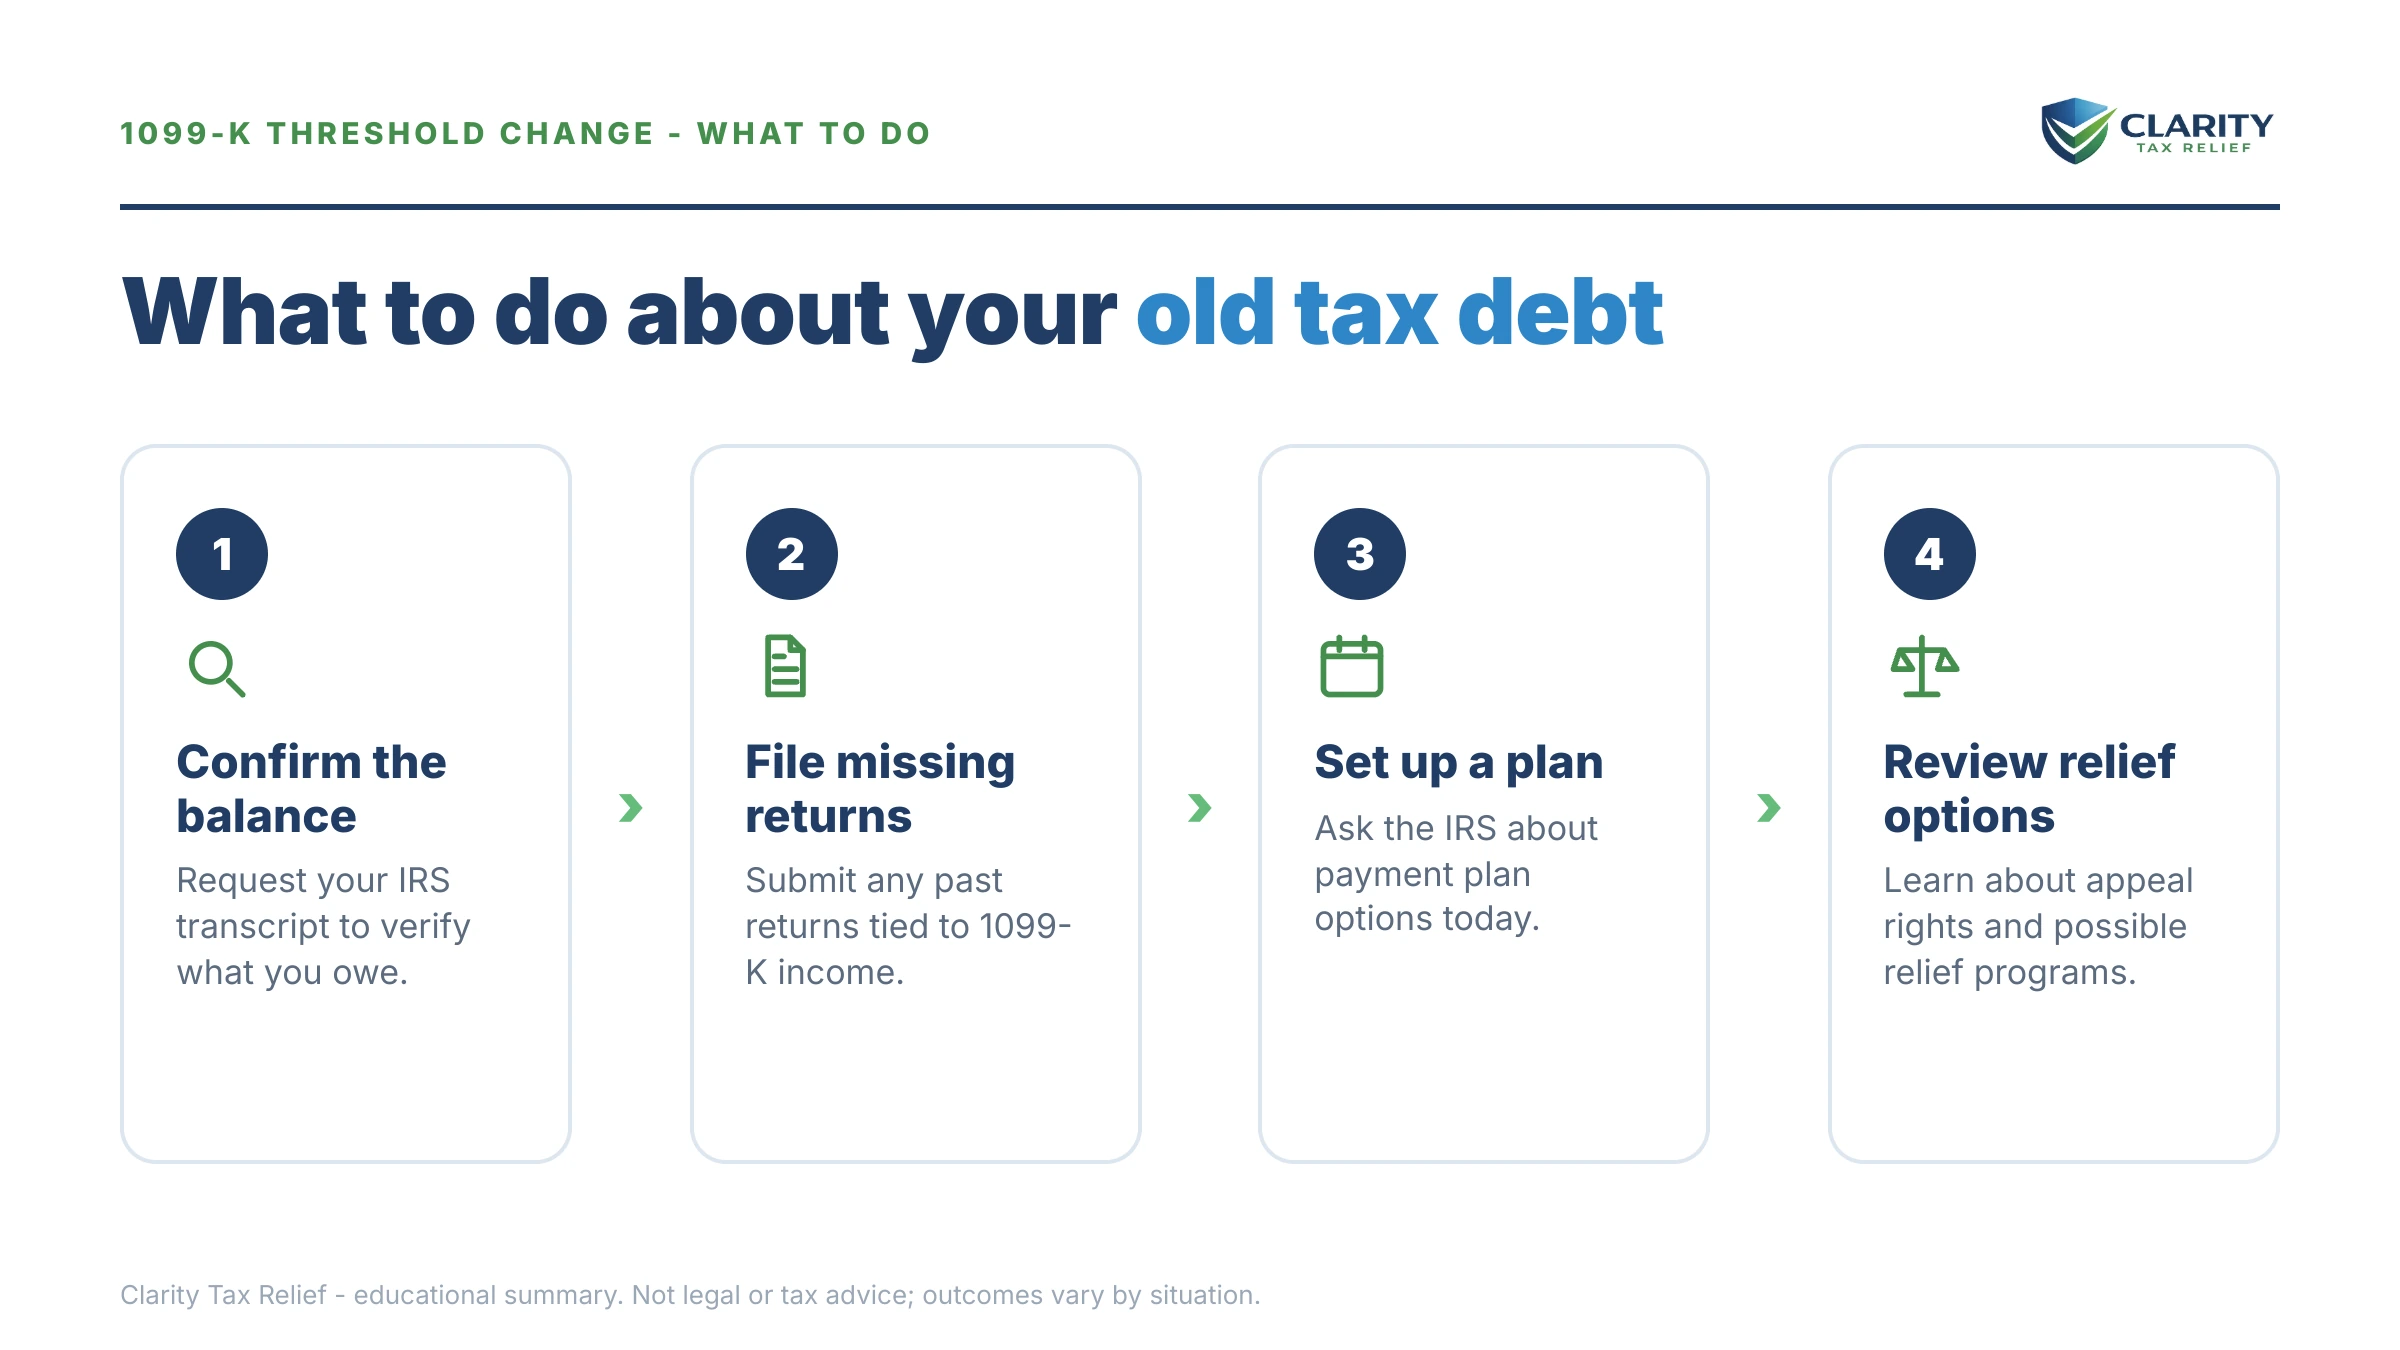
- Pull your IRS records. Log into your IRS online account and request wage and income transcripts. They show every 1099-K filed under your Social Security number and any balance already assessed.
- Check the assessed numbers against reality. If the IRS taxed your gross 1099-K totals with no costs, fees, or personal-item losses subtracted, filing an accurate or amended return can shrink the debt before you negotiate on it.
- Respond to any live notice by its printed date. A CP2000 typically gives 30 days to dispute. An LT11 gives 30 days to request a Collection Due Process hearing on Form 12153 before levies can start.
- Set up a resolution that fits the corrected balance. Pay in full at IRS.gov/payments, use a payment plan, or pursue hardship status or an Offer in Compromise if the numbers support one.
- Fix 2026 before it becomes next year's debt. Set aside a share of every platform payout for quarterly estimated taxes and keep cost records. The form threshold went up. The tax on your profit did not.
Red flags to check before you pay a 1099-K balance
- The assessment equals tax on the gross Box 1a figure. Fees, shipping, refunds and inventory costs were never subtracted. Correct it before you pay a dollar of it.
- Personal items sold at a loss were taxed as profit. Used furniture, electronics and clothes sold for less than you paid are not income.
- An LT11 or Letter 1058 is in hand. The 30-day window for Form 12153 does not restart. Levies follow it.
- The balance is over $50,000. You are outside the streamlined online plan until the number comes down or you complete financial disclosure.
- The balance is over $66,000. Passport certification is on the table for 2026.
- A bank levy has already been served. The 21-day hold is the last window before the money leaves.
- Your platform work is really a job. If the shop controls your hours and methods, the employment-tax split may belong to someone else.
Can you handle this yourself?
Plenty of 1099-K situations need no professional at all. If your only issue is a 2026 form question (you are under $20,000 and 200 transactions, or you sold personal items at a loss), good records and an accurate return solve it. If you agree with an assessed balance and it is modest, a short-term plan or a streamlined agreement takes minutes to set up at the IRS payment plans page, and paying directly at IRS.gov/payments costs nothing extra.
Experienced help changes outcomes in specific situations: a bank or wage levy already in motion, multiple unfiled years that need reconstruction before the assessment can be corrected, a balance over $50,000 where financial disclosure decides your monthly payment, or Offer in Compromise math where one wrong figure sinks the application. If your platform work is really employment in disguise, meaning the shop controls your hours and methods, the analysis in 1099 but should be W-2 (Form SS-8) may shift who owes the employment tax. If you are a booth-renting stylist or barber sorting platform payments from cash, hair stylist taxes owed on 1099 income covers that specific mix. Reseller with multi-year platform debt? See eBay seller tax debt from a 1099-K.
Terms on your 1099-K and IRS notices, decoded
- TPSO: third-party settlement organization, the payment app or marketplace (PayPal, eBay, Etsy, Venmo) legally required to file the 1099-K.
- Gross amount (Box 1a): total payments processed, before fees, refunds, shipping, or your costs; it is not your profit.
- Backup withholding: the tax a platform must withhold from your payouts if you never provide a valid taxpayer ID number.
- CP2000: the automated notice generated when a 1099-K on file does not match what your return reports.
- De minimis threshold: the legal floor below which a platform is not required to file: $20,000 and 200 transactions for 2026.
- CSED: the collection statute expiration date: 10 years from assessment, though certain actions like an OIC or bankruptcy pause the clock.
One nearby trap worth naming: a Form 1099-C is not a 1099-K. If a lender forgave a debt and sent you one, that is cancelled-debt income with its own rules and exceptions. See 1099-C cancelled debt taxes.
The bottom line on the 1099-K threshold and old debt
For 2026 the form goes out only above $20,000 and 200 transactions per platform. That changes paperwork and nothing else. Profit was taxable before the reversal and is taxable after it, and every 1099-K already filed for 2022 through 2024 stays in the matching system. If an old balance exists, check whether it was built on gross sales before you agree to pay it, because a corrected return often cuts the number more than any program will. Then pick the plan that fits the corrected balance. And if an LT11 has arrived, the 30 days on Form 12153 come first.
1099-K threshold questions, answered
What is the 1099-K threshold for 2026?
For payments received during 2026, the federal threshold is more than $20,000 in gross payments AND more than 200 transactions through a single platform. Both parts of the test must be met before the platform is required to send you a Form 1099-K in January 2027. Some states require platforms to issue the form at lower amounts, so you may still receive one below the federal line.
Did the $600 1099-K rule go away?
Yes. The $600 threshold enacted in 2021 was repealed in 2025 before it ever fully took effect, and the law restored the original $20,000-and-200-transaction standard. The one year a lower threshold actually applied was 2024, when a transitional $5,000 rule sent millions of first-time forms out in early 2025. Income was taxable in every one of those years regardless of the form.
Do I still owe taxes if I don't get a 1099-K?
Yes. The threshold controls when a platform must send a form. It has never controlled whether income is taxable. Profit from selling goods or services is reportable from the first dollar, with or without paperwork. And platforms send the IRS the same figures they send you, so leaving platform income off a return is exactly how the IRS's matching program generates CP2000 notices.
Does the $20,000 threshold erase tax debt from earlier years?
No. If the IRS already assessed tax on your platform income from 2022, 2023, or 2024, that balance remains collectible for the full 10-year collection statute, and penalties and interest keep accruing until it is resolved. The threshold change only affects which forms go out in the future. Your realistic paths are a payment plan, hardship status, penalty relief, or correcting the assessment if it overstated your profit.
What if my 1099-K includes personal items I sold at a loss?
Selling your own used belongings for less than you paid is not taxable income, even when the payments appear on a 1099-K. The form reports gross payments, not profit. Report the sales and back out the losses on your return instead of ignoring the form — an unexplained 1099-K is exactly what the IRS's document-matching system flags. Keep any records showing what you originally paid for the items.
Will Venmo or PayPal report money friends send me?
No. Personal transfers — splitting rent, paying a friend back, gifts — are not reportable payments and should not appear on a 1099-K. Only payments for goods and services count toward the $20,000 and 200-transaction test. If personal transfers were miscoded as business payments, ask the platform for a corrected form, because the IRS will otherwise treat the full gross amount as potential income.
Can the IRS levy my bank account over old 1099-K debt?
Yes, once it has sent a final notice of intent to levy (LT11 or Letter 1058) and the 30-day window has passed. A bank levy freezes the funds in your account for 21 days before the bank sends them to the IRS. That hold is your chance to get the levy released. Getting into a payment plan or proving hardship generally stops levy action while the arrangement stays in place. More on the mechanics in our guide to the IRS bank levy and the 21-day rule.
Your next 24 hours
- Find the assessed years and amounts. Pull every IRS notice you have and note the tax year, the balance, and any "final notice" language. An LT11 changes your priorities immediately.
- Gather your platform records. Download each platform's annual sales report plus anything showing your costs: purchase receipts, fee statements, shipping records. This is the raw material for shrinking an inflated assessment.
- Get the free case review. Call (888) 825-7779 or use the 2-minute form. If a levy is in motion, the release path runs through your transcripts, and every month of delay adds penalties and interest to a balance the reporting-threshold change will never touch.
The IRS's own overview of the form is at Understanding your Form 1099-K.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.