
IRS Forms
Form 13711 OIC Appeal: How to Fight an Offer in Compromise Rejection (2026)
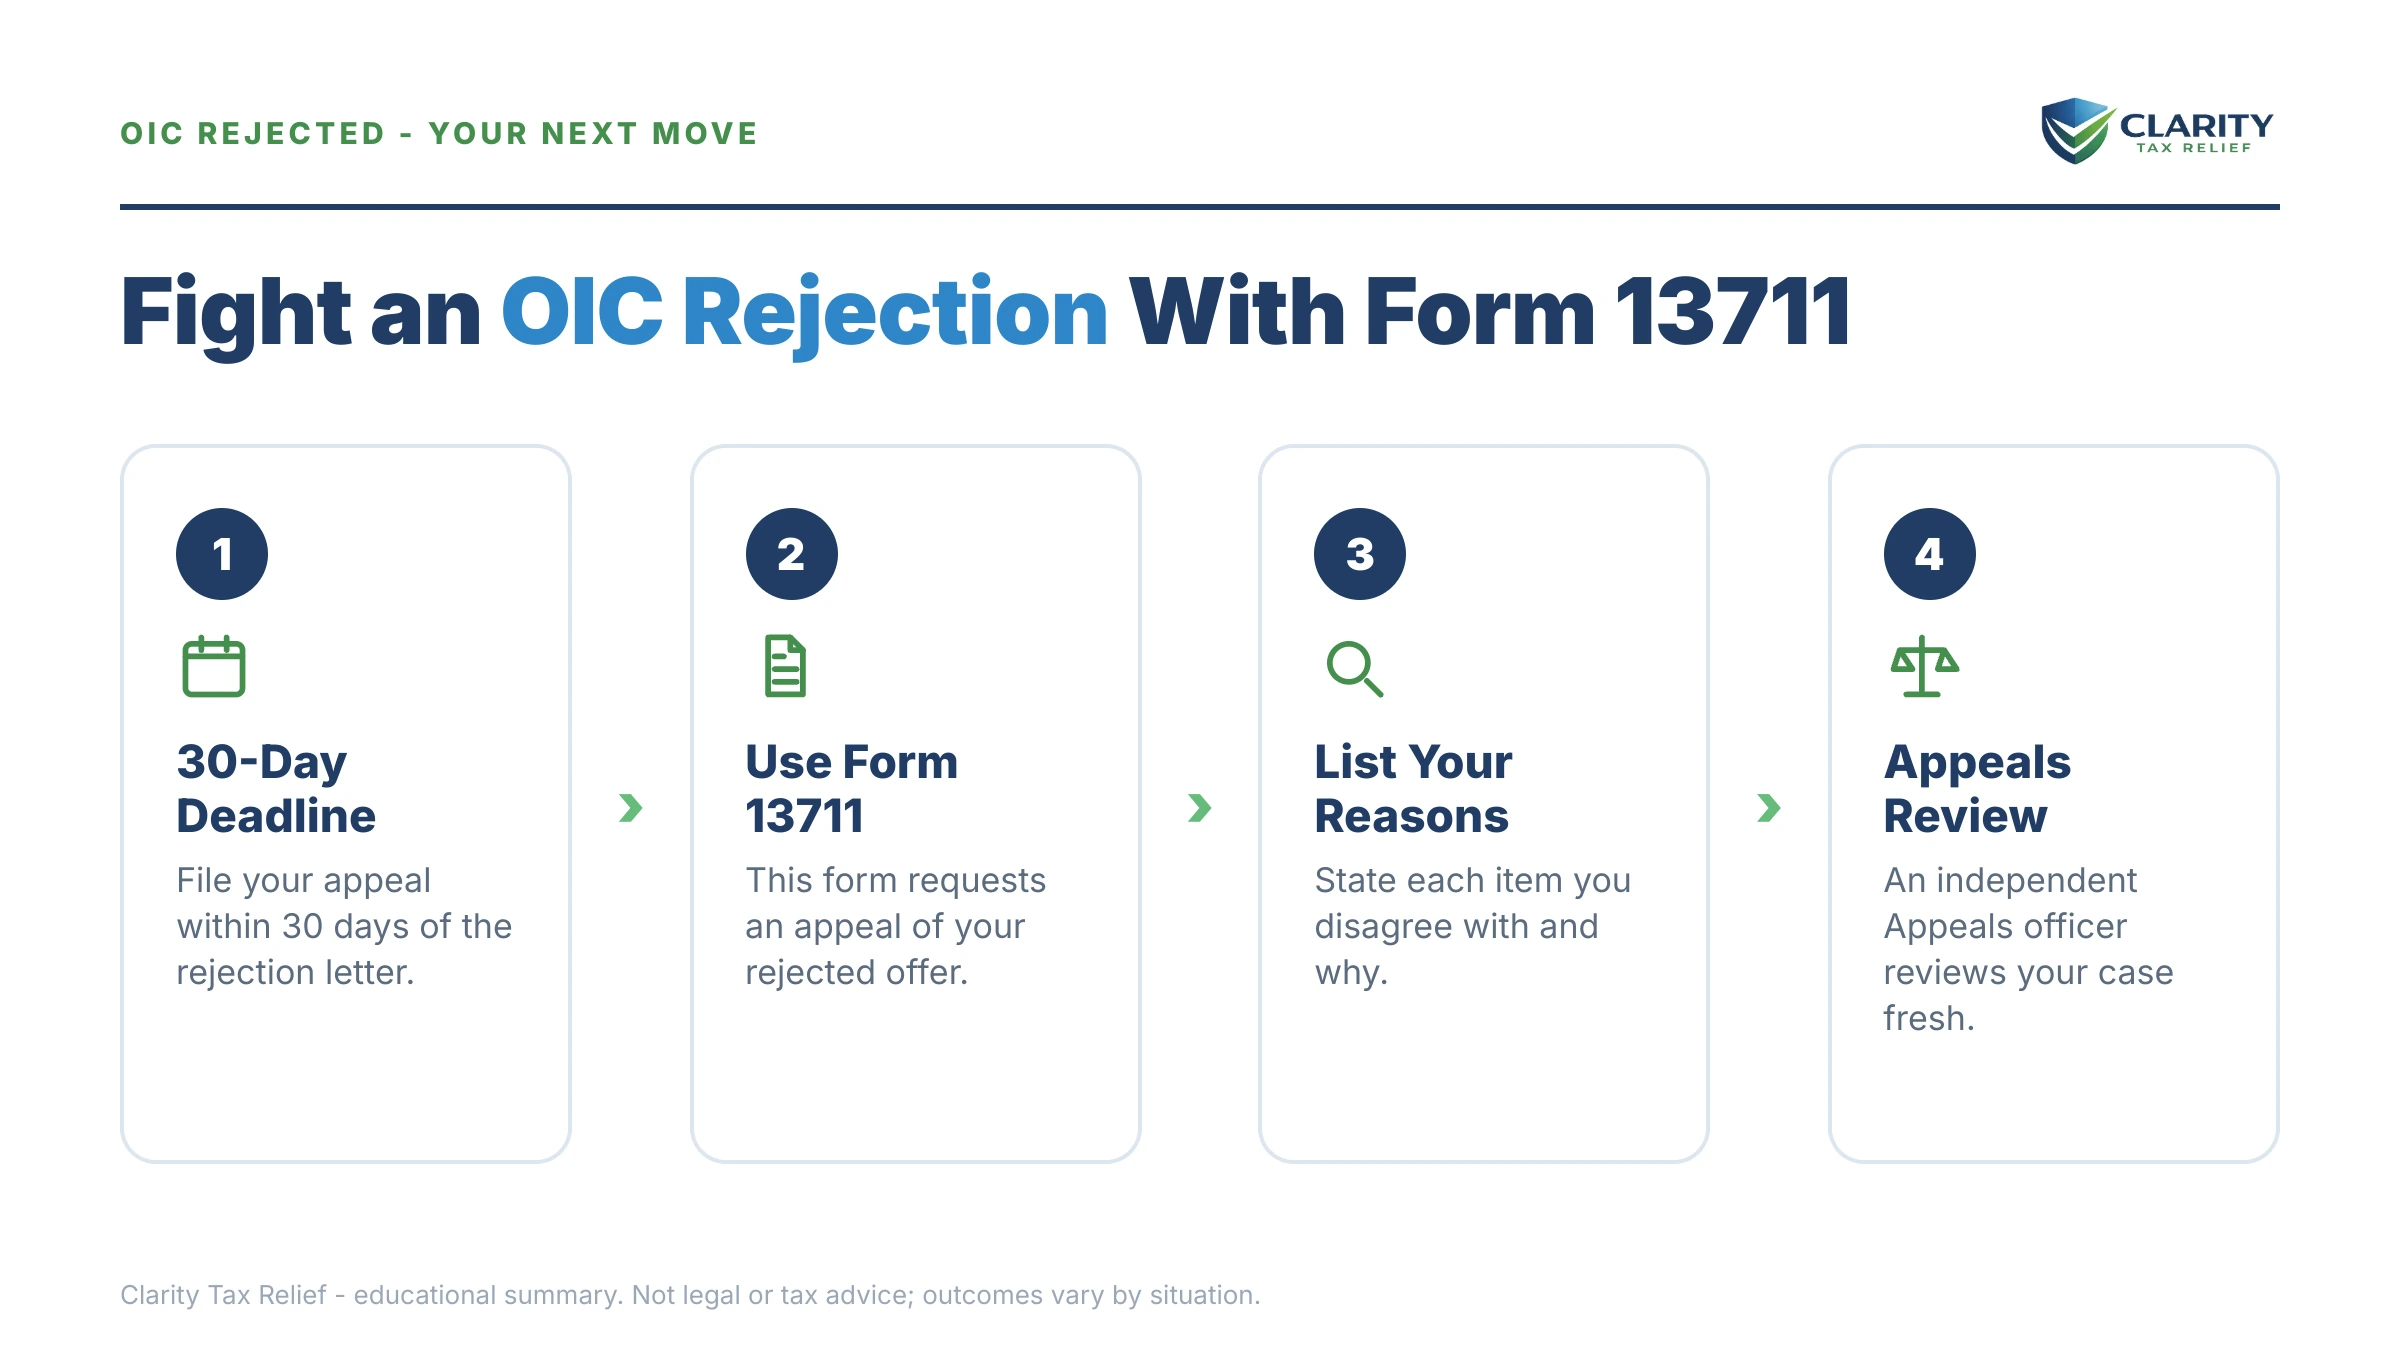
The short answer: Form 13711, Request for Appeal of Offer in Compromise, is how you challenge an IRS offer rejection. You have 30 days from the date on your rejection letter to file it with the office that rejected your offer, and it only works for rejected offers, never returned ones.
What this guide covers: how to use Form 13711 to appeal a rejected offer in compromise, how to tell a rejection from a return, what the 30-day deadline means in practice, which lines in the examiner's Reasonable Collection Potential math are worth disputing, how to file the form, what the appeal process looks like while it is pending, and when a different path may serve you better than appealing.
You spent months on your offer in compromise, and the letter that came back says "we are rejecting your offer" with a Reasonable Collection Potential number far above what you proposed. A Form 13711 OIC appeal is your one built-in chance to put that math in front of a fresh set of eyes, the IRS Independent Office of Appeals, without starting over or paying another fee.
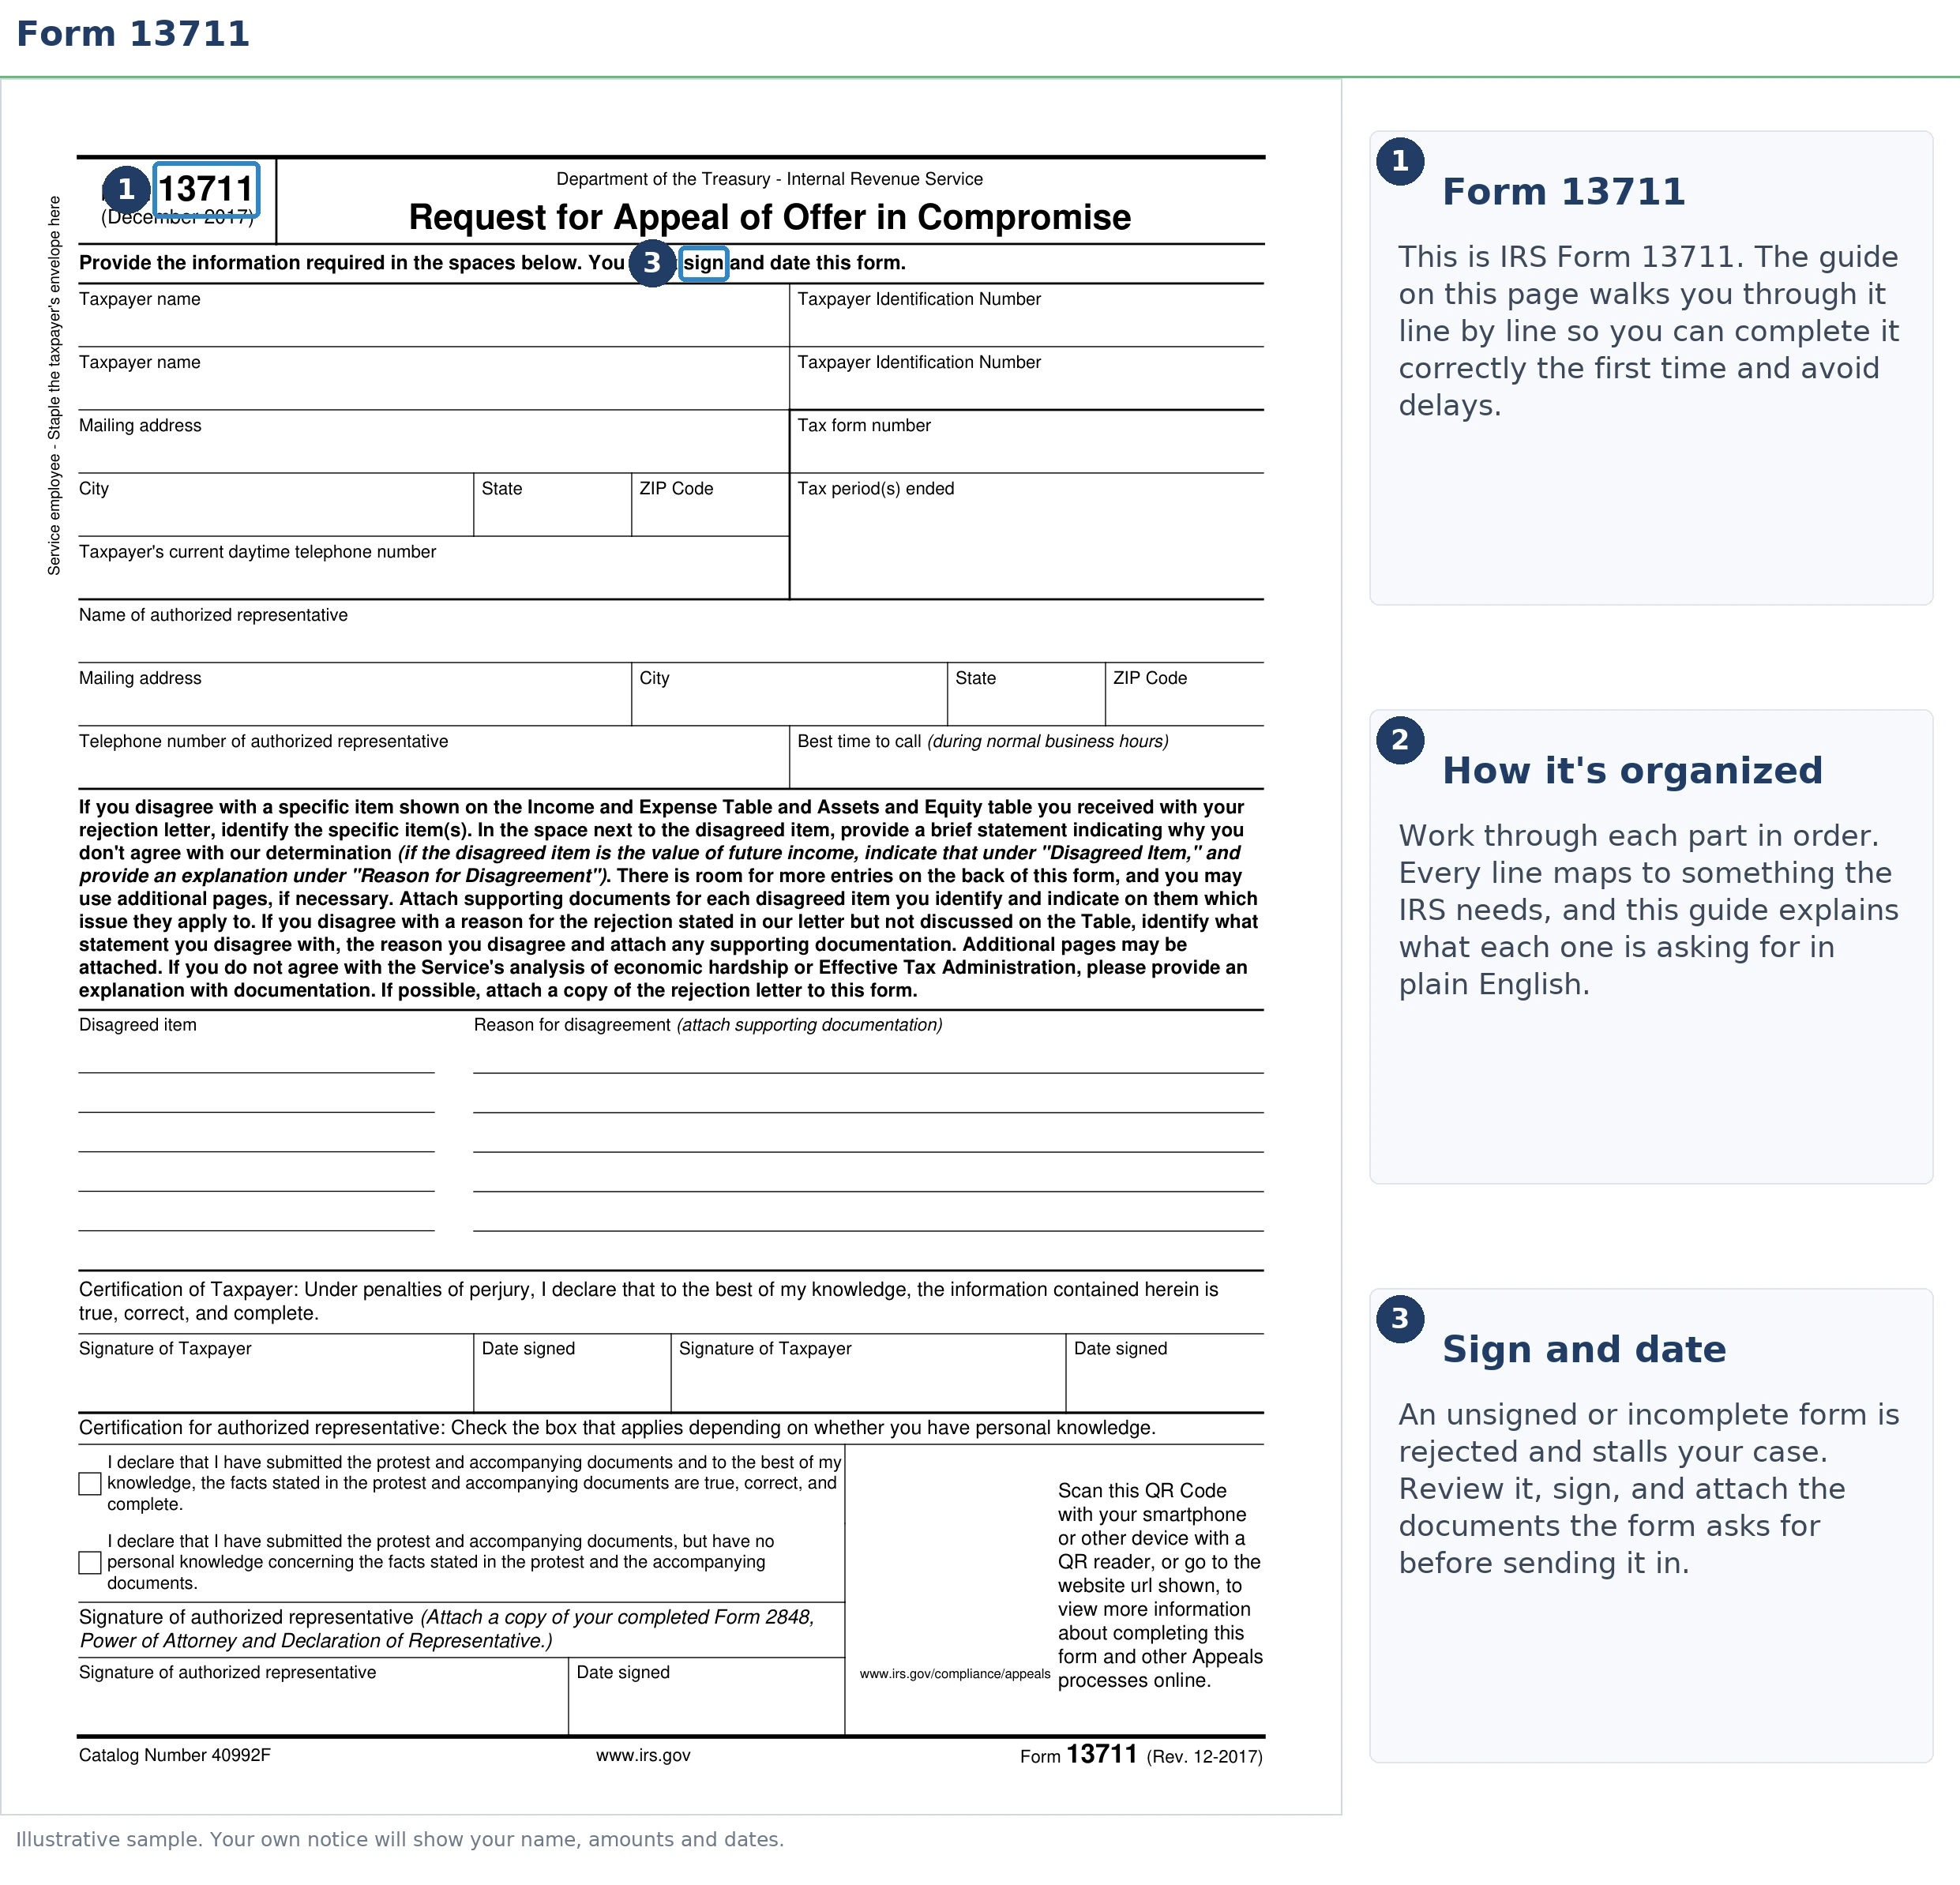
A rejection is the examiner's opinion of your finances, and examiners get the math wrong in documented, correctable ways. The image below shows you what Form 13711 looks like and where each required section sits, so you know what you are filling out before the clock runs down.
Your deadline: You have 30 days from the date printed on your OIC rejection letter to file Form 13711. Count from the date on the letter. The day it arrived does not matter. Use certified mail so you can prove your postmark. A conference with the examiner's manager does not pause this clock.
Why was your offer rejected, and what can a Form 13711 OIC appeal fix?
The IRS rejects an offer when it calculates that it can collect more than you offered. That calculation is called Reasonable Collection Potential (RCP): your monthly disposable income multiplied out, plus the net equity in what you own. If the examiner's RCP came out above your offer amount, rejection is nearly automatic. For the full picture of how offers are evaluated, see our guide to how an offer in compromise works. This page stays focused on the appeal.
The rejection package matters as much as the letter. It should include an income/expense table and asset table showing how the examiner got to their RCP number. Your appeal wins or loses on whether you can prove specific lines of that table wrong. How unfair the result feels carries no weight.
The most common attackable errors, especially for self-employed and gig filers:
- Gross treated as net. The examiner used your gross app deposits or 1099-K totals as income without subtracting mileage, platform fees, and supplies.
- Living expenses capped below the standards. Your actual rent or health costs were cut to a number below what IRS allowable-expense standards or your documentation support.
- Inflated asset values. A vehicle valued at retail instead of quick-sale value, or a loan balance ignored when computing equity.
- A dissipated-asset add-back. Money you spent, say a drained savings account, added back into RCP as if you still had it. These are fightable when the spending went to necessary living expenses.
- Public-policy or compliance grounds. Rarer, and harder to overturn, but still appealable.
One thing Form 13711 cannot do: raise brand-new financial facts that arose after the rejection. Appeals reviews the offer you made on the finances you documented. If your situation has changed since then, a new offer is often the better tool. The options table below covers that.
Did you get a rejection or a return?
Form 13711 only applies to rejected offers. A returned offer has no appeal rights at all. This distinction trips up more people than anything else about the form. It especially matters if you filed your offer while catching up on back returns. An offer gets returned when it is not processable: unfiled returns, missed estimated tax payments, missed periodic offer payments, or missing paperwork. If you recently caught up after three years of unfiled returns and one slipped through, a return letter is what you would get.
| Question | Rejected offer | Returned offer |
|---|---|---|
| Can you file Form 13711? | Yes — within 30 days of the letter date | No — there is no appeal right |
| Why it happened | The IRS decided your RCP exceeds your offer, or rejected on policy grounds | Processability failure: unfiled returns, missed payments, missing information |
| How the letter reads | Explains the rejection and spells out your 30-day appeal right | States the offer is returned; no appeal language |
| Your best move | Appeal the specific math errors, or submit a stronger new offer | Fix the cause, then resubmit a new Form 656 |
If you got a return letter, skip the rest of the appeal mechanics and go straight to fixing the defect. Our guide to refiling after a denial covers resubmission for both situations.
What happens if you don't appeal within 30 days?
Once the 30-day window closes, the rejection becomes final and the protections your pending offer gave you fall away in sequence:
- Day 30 passes. Your administrative appeal right expires. There is no late Form 13711, and no court reviews a standalone OIC rejection after this point.
- Levy protection ends. The law barred levy while your offer was pending and for 30 days after rejection. After that window, the IRS can resume enforced collection.
- Your money stays applied. The $205 application fee, any 20% down payment, and periodic payments you made are kept and applied to the debt. Our guide to whether the OIC down payment is refundable walks through where each dollar went.
- The collection clock restarts. The 10-year collection statute, paused while your offer and any appeal were pending, starts running again, and so does active collection.
- Notices pick up where they left off. If the IRS issued a final notice of intent to levy before your offer, it does not have to warn you again before levying wages or bank accounts.
Interest and the 0.5%-per-month late-payment penalty never stopped accruing during any of this. The offer paused enforcement only. The meter kept running.
Holding an OIC rejection letter right now?
Send us the rejection letter and the examiner's income/asset tables before the 30-day appeal window closes. An experienced tax professional will tell you, free, whether the RCP math has attackable errors, or whether a different path beats appealing.
What are your options after an OIC rejection?
A Form 13711 appeal is one of five realistic moves after a rejection, and it is not always the best one. The right choice depends on why you were rejected and how big the gap is between your offer and the examiner's RCP.
| Option | Upfront cost | Timeline | When it fits |
|---|---|---|---|
| Form 13711 appeal | $0 to file; keep periodic offer payments going unless low-income certified | Often several months for an Appeals conference and decision | The examiner made specific, documentable errors in income, expenses, or asset values |
| Manager conference | $0 — call the number on the rejection letter | Days to weeks; does not extend the 30-day appeal deadline | One obvious factual error (a payment that didn't post, a document they missed) |
| New offer (Form 656) | $205 fee again, plus 20% down on lump-sum — both waived with low-income certification | Restarts the full offer review from the beginning | Your finances genuinely changed, or the first offer had fixable defects |
| Installment agreement | Setup fee varies by method; interest and penalties keep accruing | Can be in place within days online for balances ≤ $50,000 | The RCP math is basically right and you can afford monthly payments |
| Currently Not Collectible | $0, but requires full financial disclosure | Weeks to set up; reviewed periodically | Paying anything at all would leave you unable to cover basic living expenses |
One quiet advantage of appealing first: Appeals officers can, and often do, negotiate. Many appeals end with an accepted offer at a number between yours and the examiner's RCP rather than a flat "sustained" or "reversed." A new offer goes back into the general queue, where the IRS accepted roughly 1 in 5 offers in FY2024. Check the current offer in compromise acceptance rate data before assuming a resubmission fares better.
How do you file Form 13711, step by step?
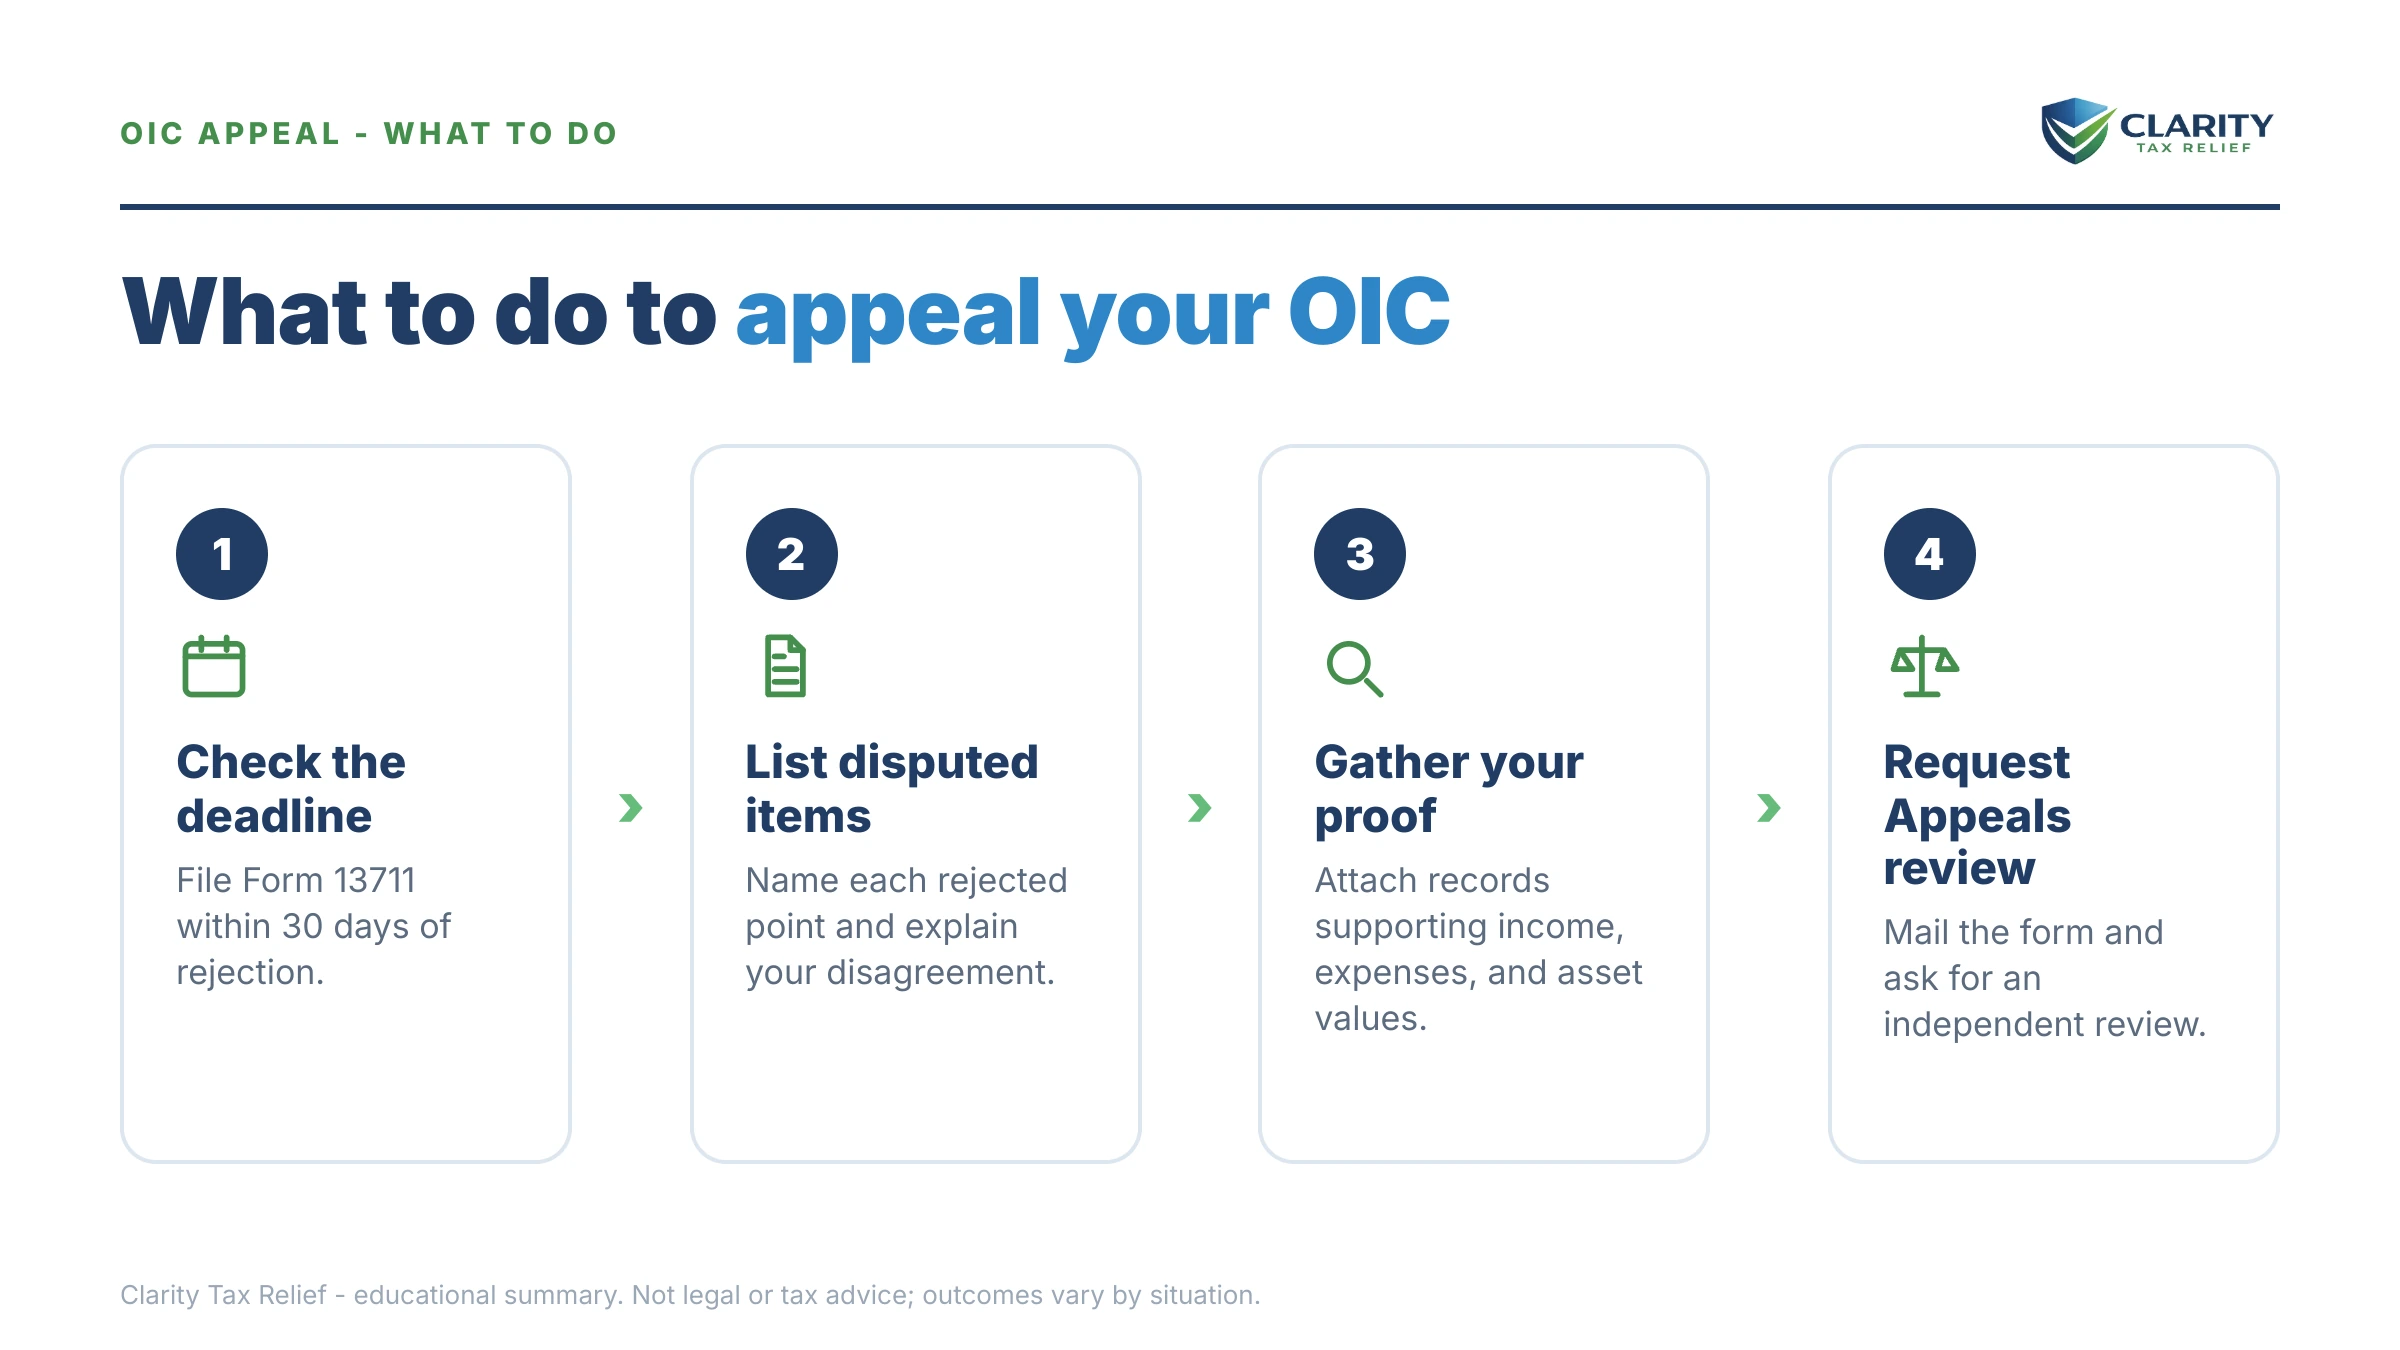
The form itself is two pages. The work is in the attachments. Download the current version from the IRS (linked below), then build your appeal around the examiner's own tables.
- Confirm your offer was rejected, not returned. A true rejection letter spells out your 30-day appeal right. A return letter does not, and Form 13711 will not help.
- List every item you dispute. Pull the examiner's income, expense, and asset figures from the rejection package and state, item by item, what is wrong and what the correct number is.
- Attach proof for each corrected number. Bank statements, app earnings summaries, mileage logs, loan payoff statements, or valuations that support your figures.
- Sign under penalties of perjury. You (and your spouse, on a joint offer) must sign. A representative filing for you needs Form 2848 on file.
- Mail it to the office on your rejection letter within 30 days. Send it certified mail with return receipt so you can prove the postmark date.
- Keep making periodic offer payments unless you are low-income certified. Stopping payments on a periodic-payment offer can sink the offer independently of the appeal.
Two drafting rules separate winning appeals from losing ones. First, dispute specific items. "The RCP is too high" gets nowhere. "Line 3 uses my gross 1099-K deposits of $3,400/month instead of my net $2,950 after documented mileage" gets traction. Second, do not pad the appeal with hardship narrative the numbers do not support. Appeals officers read the financials first and the story second.
What to check before you mail it:
- The letter says "rejected" and states a 30-day appeal right. If it says "returned," Form 13711 does not apply.
- You counted 30 days from the date printed on the letter, and your postmark will fall inside that window.
- Every disputed line has a corrected figure and a document behind it.
- Both spouses signed on a joint offer, or Form 2848 is on file for your representative.
- Periodic offer payments are current, unless you are low-income certified.
- You have not relied on a manager conference to extend the deadline. It does not.
What RCP math does your appeal have to beat?
An OIC appeal succeeds by shrinking two numbers: monthly disposable income and net asset equity. Here is what that looks like with real arithmetic, clearly hypothetical.
Say you deliver for gig apps, just filed three years of back returns to get compliant, and owe $8,900 across those years. You offered $1,200 as a lump sum. The examiner's rejection package shows:
- Monthly income: $3,400 (your gross app deposits) minus allowed expenses of $3,100 = $300 disposable
- Future income component: $300 × 12 (the lump-sum multiplier) = $3,600
- Vehicle equity at quick-sale value: $2,600
- RCP: $3,600 + $2,600 = $6,200, far above your $1,200 offer. Rejected.
Your Form 13711 attacks two lines. The income line used gross deposits. After documented mileage and platform fees, your net self-employment income is $2,950. Your substantiated allowable expenses are $2,890, so disposable income drops from $300 to $60. That cuts the future-income component to $60 × 12 = $720. The vehicle line ignored your $1,800 loan payoff, so real equity falls from $2,600 to $800.
Corrected RCP: $720 + $800 = $1,520. Now your $1,200 offer is in negotiating range. The Appeals officer may accept an amended offer at or near $1,520, a materially different outcome than the $6,200 demand, produced entirely by documentation. Before you file, you can pressure-test your own numbers with our Offer in Compromise Calculator, which estimates RCP the way the IRS computes it.
The honest counterweight at this debt size: $8,900 divided over a 72-month streamlined plan is roughly $124/month before accruing interest and penalties. An installment agreement for balances of $10,000 or less, paid within three years, runs about $248/month. If your corrected RCP still comes out near the full balance, a payment plan may resolve this faster and cheaper than months of appeal.
What happens while your Form 13711 appeal is pending?
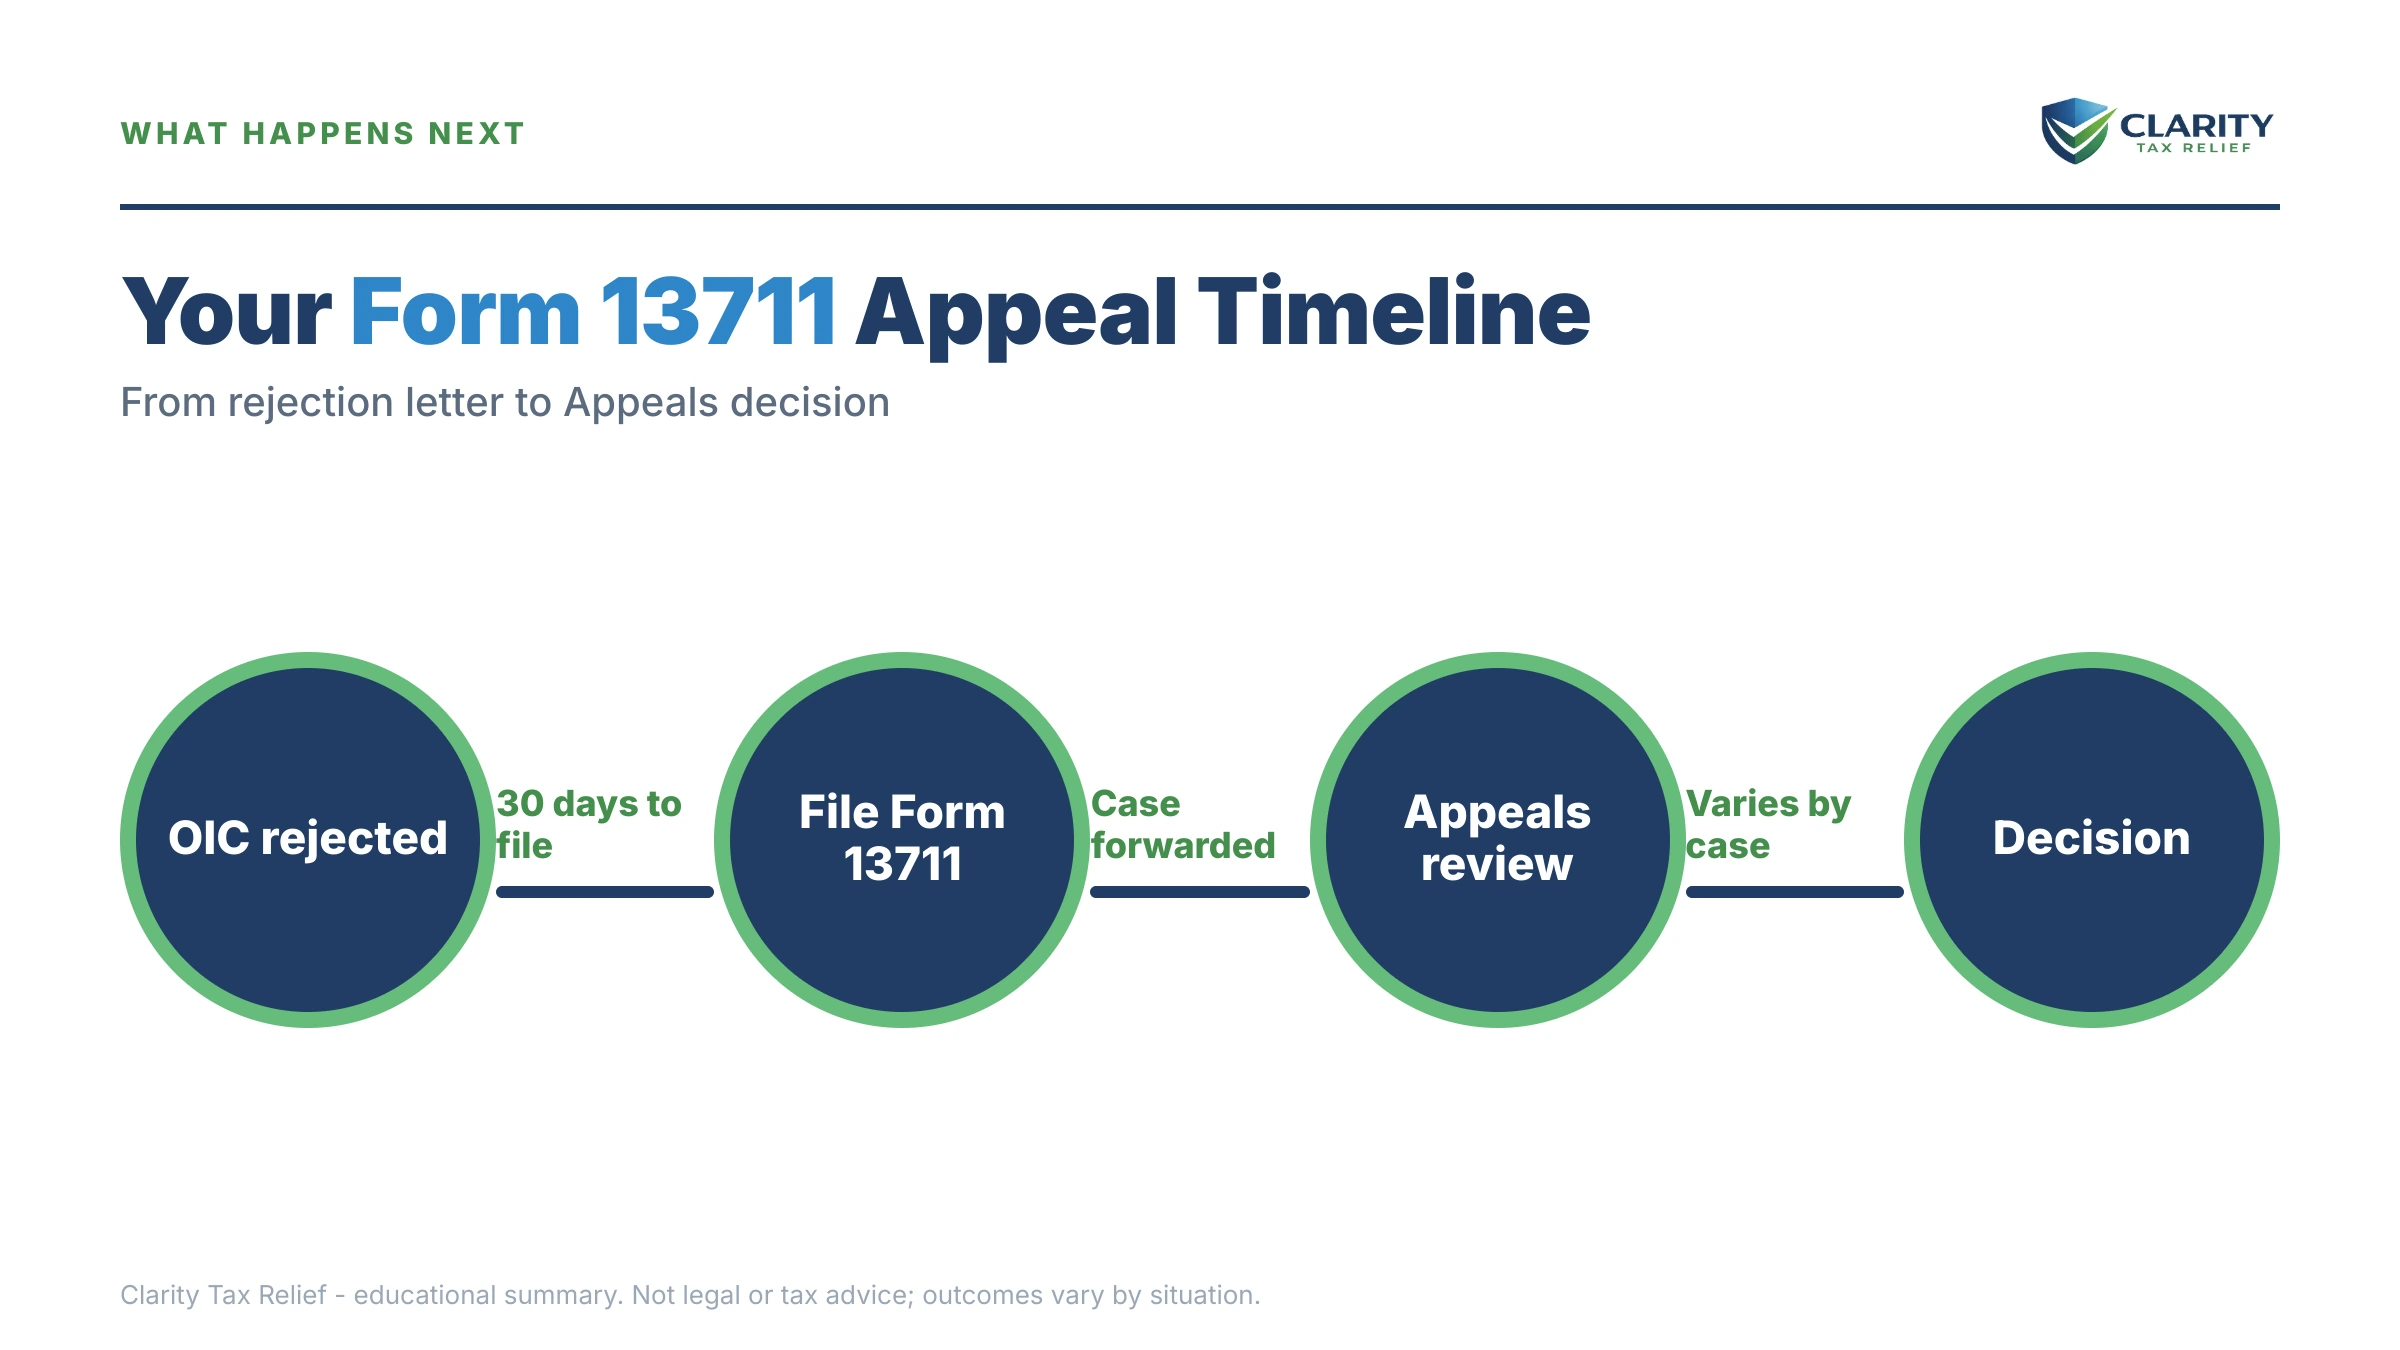
A timely appeal keeps your offer legally "pending," which means levy stays barred and the case moves to an Appeals officer who had no part in the rejection. Expect a letter acknowledging the appeal, then a conference (usually by phone) where you walk through the disputed items. The officer may agree, negotiate a middle number, send new documentation back to the offer unit for review, or sustain the rejection.
Three things to know while you wait. Interest and the late-payment penalty keep accruing on the underlying debt the whole time. The 10-year collection statute stays paused. And the two-year automatic-acceptance rule does not rescue you here. The rejection itself was the IRS's decision, so appeal time does not run that clock.
You can watch the process on your account transcript. These are the codes that matter:
| Code | What it means | What to do |
|---|---|---|
| 480 | Offer in compromise pending. This stays in place through a timely appeal | Nothing; it confirms your levy protection is active |
| 481 | Offer rejected/terminated | If it posts before your appeal resolves, call the number on your letter. It may reflect the original rejection, not the appeal outcome |
| 482 | Offer withdrawn | Should only appear if you withdrew; if you didn't, get it explained before the levy shield lapses |
| 971 | Notice issued | Watch your mail — Appeals correspondence and conference scheduling arrive this way |
If your appeal is sustained, the decision is final administratively. There is no court review of a standalone OIC rejection. The exception: if your offer was raised inside a Collection Due Process hearing (requested on Form 12153), the CDP determination can go to Tax Court. That is one reason timing an offer against collection notices matters.
Can you handle the appeal yourself, or does help change the outcome?
If your dispute is one clear, provable error, you can file Form 13711 yourself for free. A payment that did not post, a loan balance the examiner ignored, a W-2 expense with clean receipts. These are self-service appeals. The form asks for facts and documents. The official instructions on the IRS Form 13711 page are readable.
Experienced help tends to change outcomes in four situations. Reconstructing self-employment income the examiner computed from gross deposits, the single most common gig-worker dispute. Fighting a dissipated-asset add-back, where the standard for "necessary" spending is judgment-heavy. Offers involving business assets or receivables. And multi-year debts where the smarter move may be restructuring the offer rather than defending it. In 2026, with IRS staffing down roughly 27% and Appeals inventories slow, a tightly documented appeal that an officer can resolve in one conference is worth real money. A sloppy one just sits.
You can also read the IRS's own overview of the appeal path on the Independent Office of Appeals site. The program rules are on the IRS offer in compromise page.
What do the terms on your rejection letter mean?
- Reasonable Collection Potential (RCP): the IRS's estimate of the most it could ever collect from you. Future disposable income multiplied out, plus net equity in assets.
- Rejected vs. returned: a rejection is a decision on the merits with appeal rights. A return is a processing failure with none.
- Independent Office of Appeals: the IRS unit, separate from collections, that reviews your Form 13711 with fresh eyes and authority to negotiate.
- Periodic payments: the monthly installments required with a periodic-payment offer, which must continue during the appeal unless you are low-income certified.
- CSED: the Collection Statute Expiration Date, the end of the IRS's 10-year window to collect, paused while your offer and appeal are pending.
- Doubt as to collectibility: the offer basis behind most rejections, the claim that you cannot fully pay. The only basis (along with effective tax administration) Form 13711 covers.
Bottom line
Form 13711 gives you 30 days from the date on a rejection letter to put the examiner's RCP math in front of the Independent Office of Appeals at no added fee. The appeal works when you dispute specific lines, income counted gross instead of net, expenses capped below the standards, assets valued at retail or without the loan, and attach proof for each corrected figure.
Confirm the letter says rejected rather than returned, keep periodic payments current, mail by certified post inside the window, and compare the appeal against a new offer or a payment plan before you commit. If the gap between your offer and a corrected RCP is small, the appeal is often worth the months. If the corrected number still sits near the full balance, a payment plan may get you there faster.
Form 13711 questions, answered
How long do I have to appeal an offer in compromise rejection?
You have 30 days from the date printed on your rejection letter — go by that date, not the day you opened the envelope. Mail Form 13711 (or a written protest) to the office that issued the letter, and use certified mail so you can prove the postmark. Asking for a conference with the offer examiner's manager does not pause or extend the 30 days; the appeal deadline runs regardless.
Can I appeal a returned offer in compromise?
No — a returned offer carries no appeal rights, which is the single most misunderstood fact about Form 13711. A return happens for processability reasons: unfiled returns, missed estimated payments, missed periodic offer payments, or missing information. Your move is to fix whatever caused the return and submit a new offer. A true rejection letter explicitly describes your 30-day appeal right; a return letter does not.
Can the IRS levy me while my Form 13711 appeal is pending?
Generally no. The law bars levy while an offer is pending, for 30 days after a rejection, and while a timely filed appeal is under consideration. But that protection is narrow: interest and the monthly late-payment penalty keep accruing the entire time. A federal tax lien that was filed before or during your offer stays on record. The levy shield also ends if your appeal is untimely.
What are my chances of winning an OIC appeal?
The IRS does not publish a standalone win rate for OIC appeals, so be wary of anyone quoting one. What is known: the Independent Office of Appeals reviews your case fresh, and appeals succeed most often when you can point to specific, documented errors in the examiner's Reasonable Collection Potential math — wrong income figures, disallowed expenses that meet IRS standards, or inflated asset values. For context, the IRS accepted roughly 1 in 5 offers overall in FY2024, so no outcome is ever assured.
Should I file a new offer instead of appealing?
Sometimes. It depends on why you were rejected. An appeal is free and keeps your levy protection running, so it fits when the examiner made a factual or math error. A new offer restarts the process with a new $205 application fee (waived with low-income certification) and fits when your finances have genuinely changed or your first offer had defects you can now fix, like documentation gaps. Filing both paths at once is not how the process works — pick the one that matches your rejection reason.
What happens to my 20% down payment if I lose the appeal?
The IRS keeps it and applies it to your tax balance. It is not refunded, and neither are periodic payments you made while the offer was pending or the $205 application fee. That money isn't wasted, since it reduces what you owe, but you can't get it back as cash. Taxpayers who qualified for low-income certification never had to make the down payment or periodic payments in the first place, so they have nothing at stake here.
Does a Form 13711 appeal extend the IRS 10-year collection statute?
Yes. The 10-year collection clock (CSED) is paused while your offer is pending, while your appeal is being considered, and for 30 days after a rejection becomes final. That's the trade-off for the levy protection you get during the same window. For most people appealing a rejection it's a fair trade, but if your debt is within a year or two of the CSED expiring, extending the clock may cost more than the appeal is worth — check your dates before you file.
Do I need a tax professional to file Form 13711?
No — the form is free, and if your dispute is one clear factual error (a payment that didn't post, an expense the examiner missed), you can file it yourself. Experienced help tends to change outcomes when the dispute is about reconstructing self-employment income, defending against a dissipated-asset add-back, or valuing business assets — the arguments Appeals officers push back on hardest. If a representative files for you, they need a Form 2848 power of attorney on record.
Your next 24 hours
- Find the date on your rejection letter, first page, top right. Count 30 days forward and write that date down; it's your Form 13711 postmark deadline, and it's already running.
- Gather the examiner's tables and your proof. The full rejection package (not just the letter), your Form 433-A (OIC). The documents that contradict the examiner's income and asset lines: bank statements, app earnings summaries, mileage logs, loan payoffs.
- Get the rejection reviewed free before the window closes. An experienced tax professional can tell you in one call whether the RCP math is beatable or an installment agreement is the smarter play. Use the 2-minute form at claritytaxrelief.com/#consult or call (888) 825-7779.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.