
IRS Notices
CP59 Notice: What It Means and How to Respond in 2026
The short answer: a CP59 notice means the IRS has no record of a personal tax return from you for the prior year printed on it, usually because a 1099-R, SSA-1099, or W-2 arrived under your SSN with no matching Form 1040. Respond by filing that return, or by returning the attached Form 15103 explaining that you already filed or were not required to. Mail it, fax it, or submit the form through your IRS Online Account. Clarity Tax Relief answers every CP59 in writing, once, with the return or the reason.
Updated October 5, 2026 against the IRS pages for the CP59, CP516, CP518, CP2566 and CP3219N notices, the failure-to-file penalty, and the fourth-quarter 2026 interest rate.
This guide covers what a CP59 notice is asking for, how to answer it with Form 15103 or a return, which clocks are already running on an unfiled year, and when it is worth filing even if you owe nothing. Maybe you assumed that once the paychecks stopped, the filing stopped too. Then a CP59 lands in the mailbox asking about a tax year you had already filed away in your head, and suddenly you are wondering what else the IRS thinks you missed. Here is the reassuring part: a CP59 is a question rather than a bill, and the correct answer usually takes one mailing.
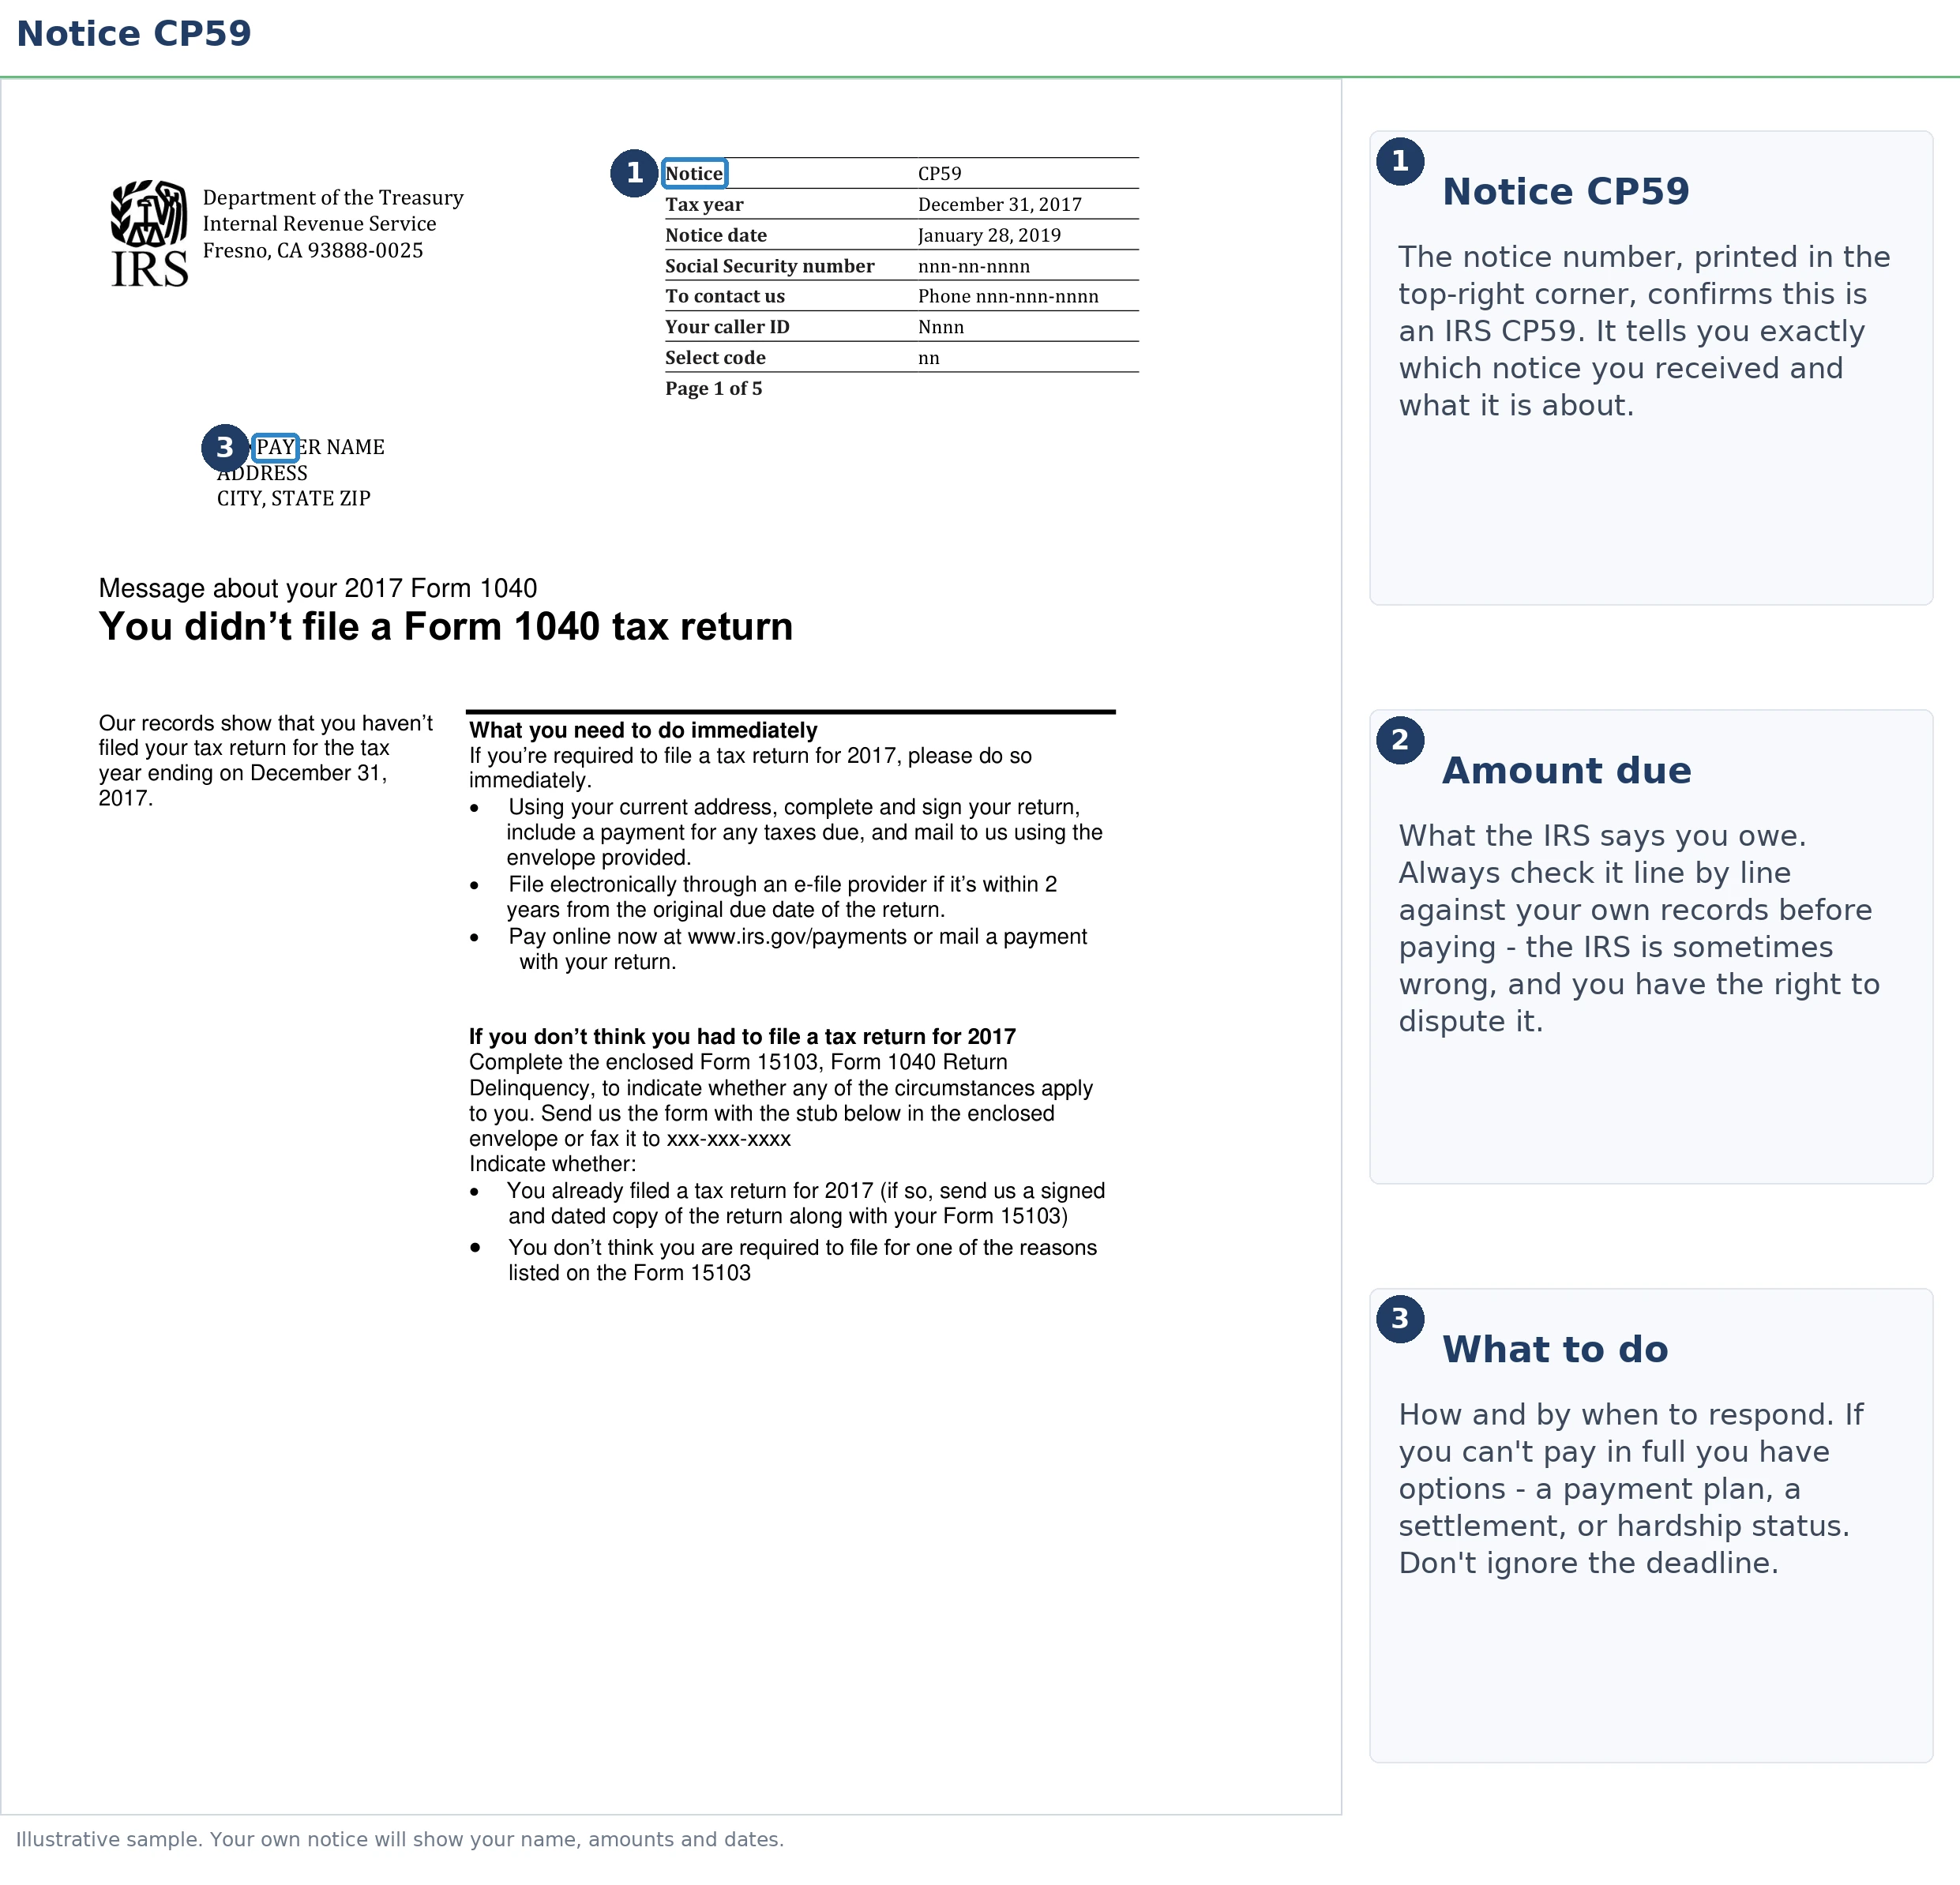
Unlike most IRS letters, a CP59 does not claim you owe a specific amount. It says the IRS computers matched income documents to your Social Security number, looked for a return for that year, and found nothing. The image below shows what a CP59 looks like and where to find the two things that matter (the tax year in question and the Form 15103 response form) so you know which reply the IRS wants.
The clocks already running: a CP59 does not print a levy countdown. Two deadlines are live anyway. If you owe tax for that year, the failure-to-file penalty grows at 5% per month, up to 25% of the unpaid tax, and interest runs at 7% for the fourth quarter of 2026. And if the IRS owes you money, you generally have 3 years from the return's original due date to claim a refund from an old return. After that it is gone for good.
Why did you get a CP59 notice?
A CP59 notice means the IRS matched income documents to your Social Security number and found no Form 1040 posted for that tax year. The IRS's own wording is that it has no record you filed your prior year personal tax return. It is the first of three return-delinquency notices, and in 2024 the IRS restarted mailing them at scale after a pandemic-era pause, which is why many people are hearing about years that sat quiet for a long time. If you want the broader map of why IRS mail shows up at all, our guide to why you got a letter from the IRS covers the whole system. This page stays on the CP59 itself.
For retirees, the trigger is almost always a third-party form: the SSA-1099 for Social Security benefits, a 1099-R for a pension or IRA distribution, or a 1099-B from a brokerage sale. The payers sent copies to the IRS whether or not you filed. The IRS is not guessing you had income. It is holding the paperwork that proves it.
That said, a CP59 does not automatically mean you did anything wrong. Common innocent explanations include:
- You filed and it didn't process. Paper returns especially can sit for months. The IRS says you need not respond at all if you filed within the last eight weeks; the return is probably still in the pipeline.
- The return is under your spouse's SSN. If you filed jointly and your spouse was listed first, the return posted to their number, not yours.
- You weren't required to file. Many retirees whose income is mostly Social Security fall below the filing threshold, which is what Form 15103 lets you say.
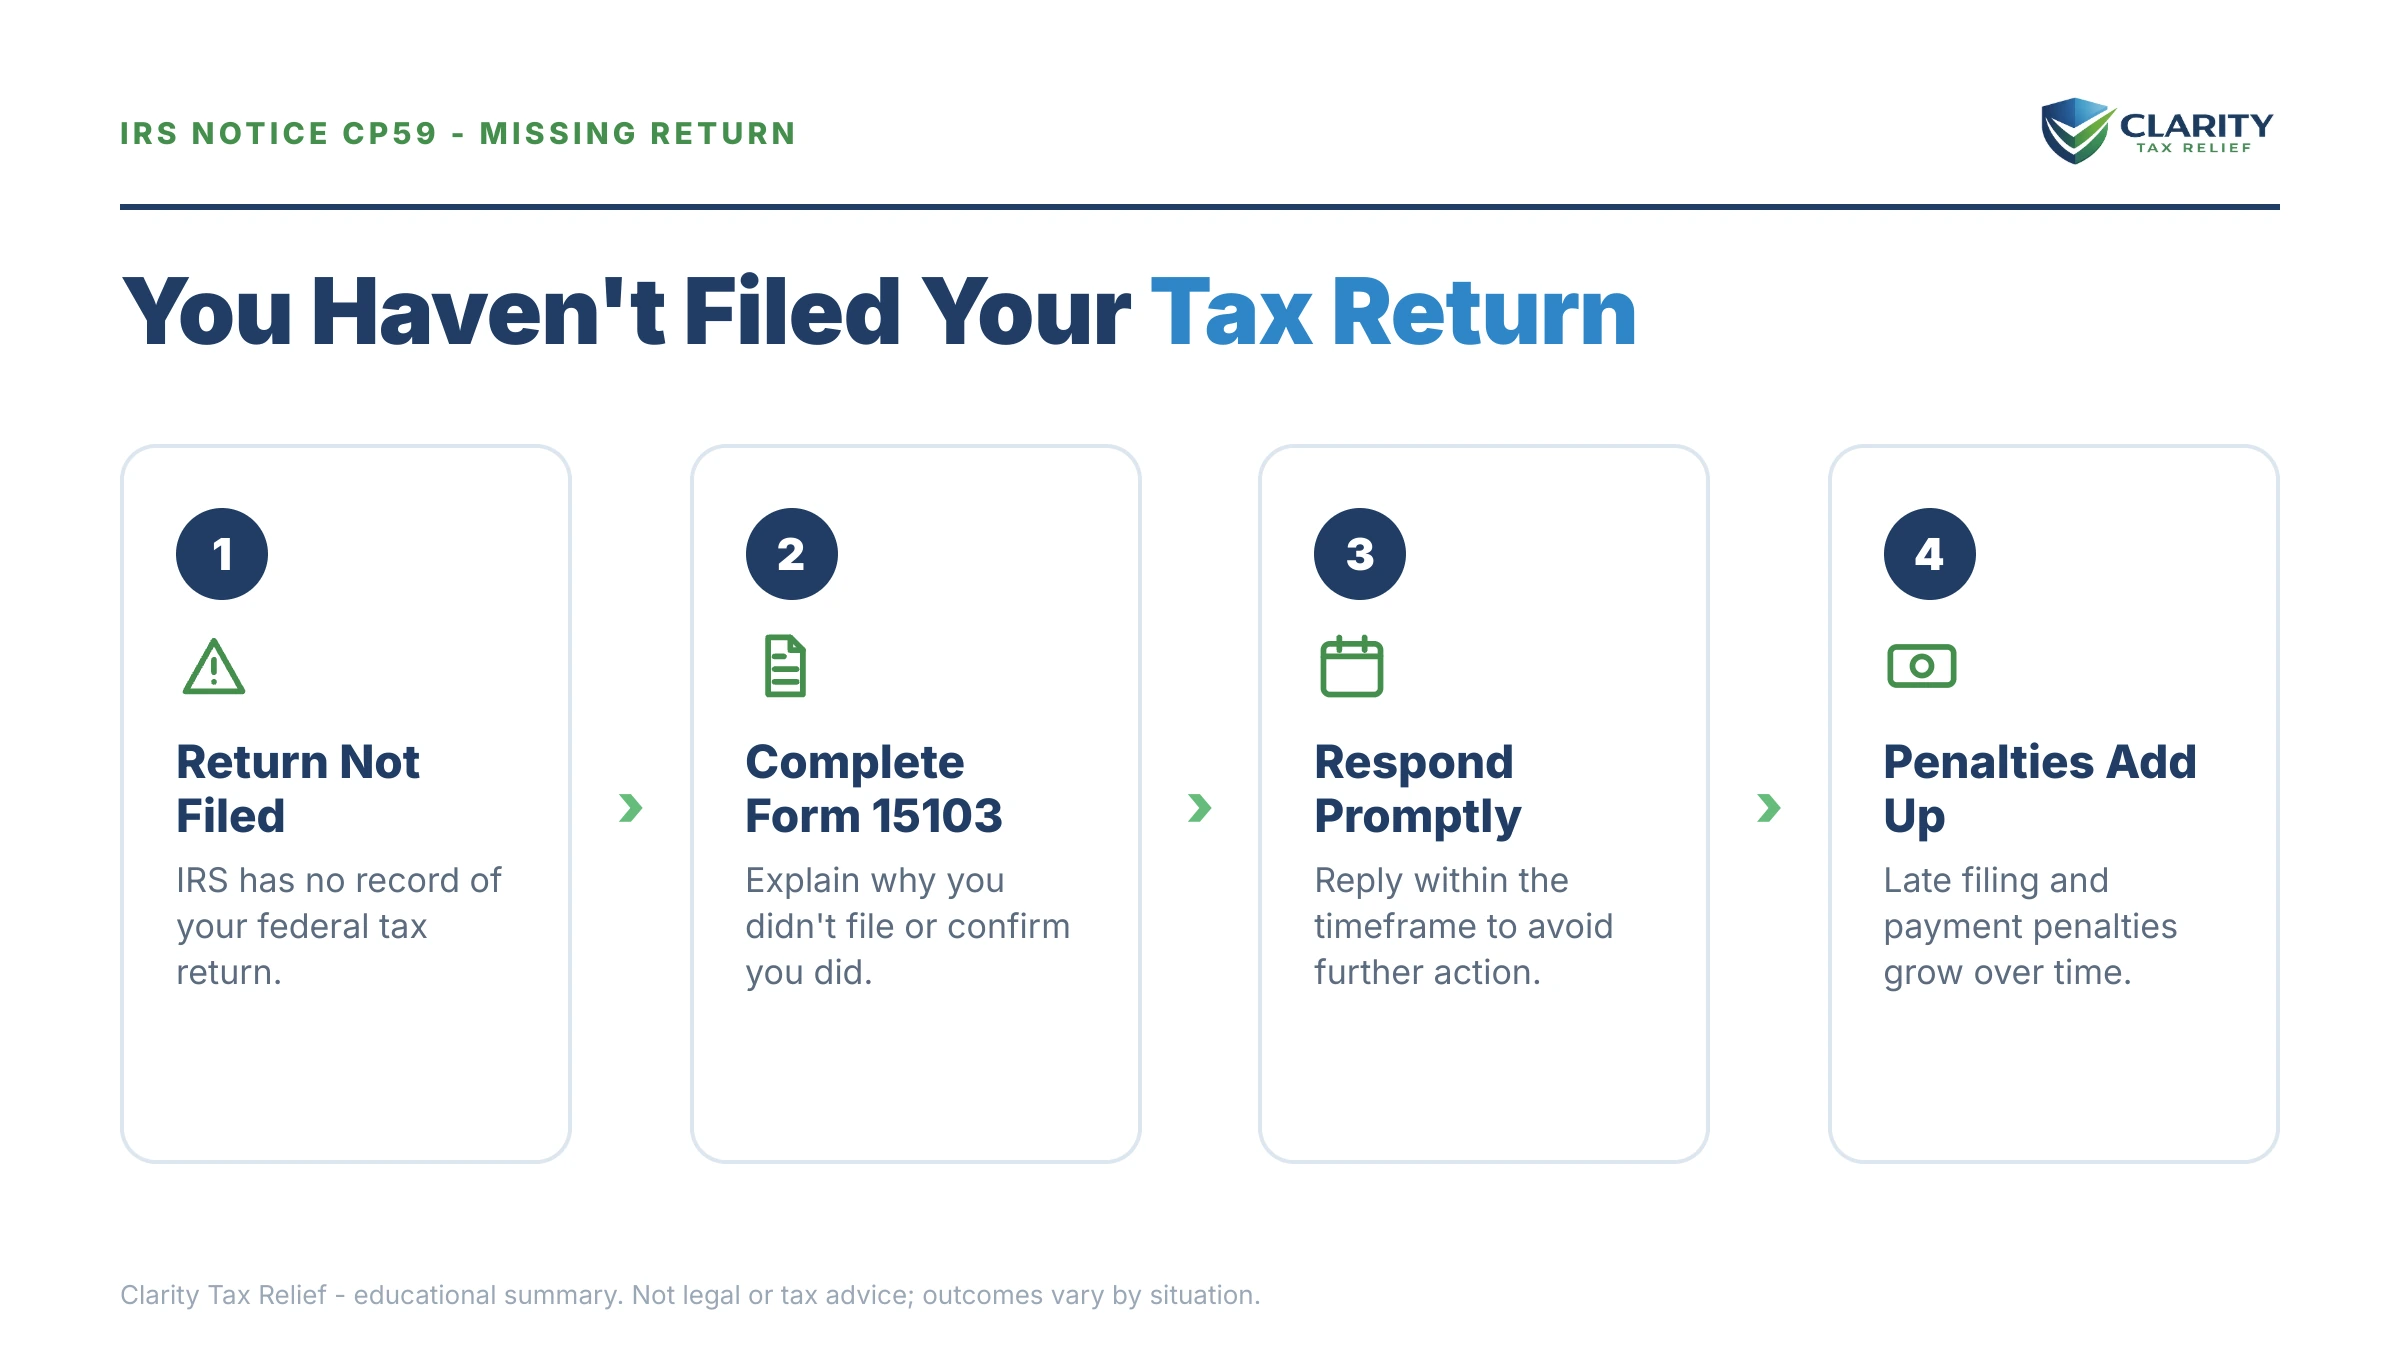
“We show that we didn’t receive your tax return. Check the name, Social Security Number (or Taxpayer Identification Number), and tax year on your notice. Make sure they match the name, number, and year on the return. Mail us a signed and dated copy of the tax return.”
, Understanding your CP59 notice (IRS.gov)
What is Form 15103?
Form 15103 is called Form 1040 Return Delinquency (the current revision is dated June 2017), and it is the response form the IRS encloses with a CP59. Two pages, one signature. It exists so you can tell the IRS one of three things: you already filed for that year, you were not required to file, or the person named on the notice has died.
It is not a tax return and it does not replace one. If you did have a filing requirement, the form is the cover letter and the return is the thing that resolves the notice. What the form does is stop the file sitting in silence, which is the state that eventually produces a return the IRS prepares for you.
You sign it under penalties of perjury, so the answers matter as much as anything you would put on a 1040.
How do you fill out Form 15103?
The top of page 1 is contact information: Social Security number, name, and address. If your address has changed, you correct it right there on the form rather than filing a separate change of address. It also asks for two phone numbers and the best time of day to reach you on each. Fill that in honestly, because a revenue officer who cannot reach you will proceed without you.
Then you pick the situation that applies:
- You already filed. Enclose a signed and dated copy of the return as verification, and list the names shown on it, the forms filed, the tax years, and the dates you filed. A copy you did not sign is not verification.
- You do not think you were required to file. Explain why, and give your filing status and total income for that year. There is a checklist beside it: 65 or older, blind, spouse 65 or older, spouse blind, not a U.S. citizen or permanent resident, work performed in another country, or could be claimed as a dependent on someone else's return. Those answers apply to that tax year only.
- The person addressed has died. Give the date of death. If an estate return went in instead, there is a line for the Form 1041 details, including the EIN it was filed under.
| Box you check | What to enclose | What the IRS does with it |
|---|---|---|
| I already filed | A signed and dated copy of the return, with the names on it, the forms, the tax year and the date you filed | Matches the copy to your account and closes the delinquency once it posts (code 150 on your transcript) |
| I don't think I was required to file | Your filing status and total income for that year, plus the age, blindness, citizenship and dependent checkboxes that apply | Closes the filing requirement for that year if the facts support it; no return needed |
| The person addressed is deceased | Date of death and, if an estate return was filed, the Form 1041 details and EIN | Stops notices to the decedent and routes any final-return question to the executor or survivor |
If none of the three fits because you need to file, skip the form and send the signed return. The return is the response.
Page 2 handles one thing people miss: a credit from a prior year that you applied forward. You can ask for it to go against another return or come back as a refund check. The form says plainly that you have to file a return either way. Its own wording is that you must file to be eligible for a refund even though you may not be required to file. If a refund has been sitting in that year, "I did not have to file" and "I want my money" cannot both be your position.
Sign it, date it, and mail it back in the envelope that came with the notice, with the IRS address showing through the window. The form asks for that specifically. The envelope routes it to the unit holding your file.
Where do you send Form 15103 or your return?
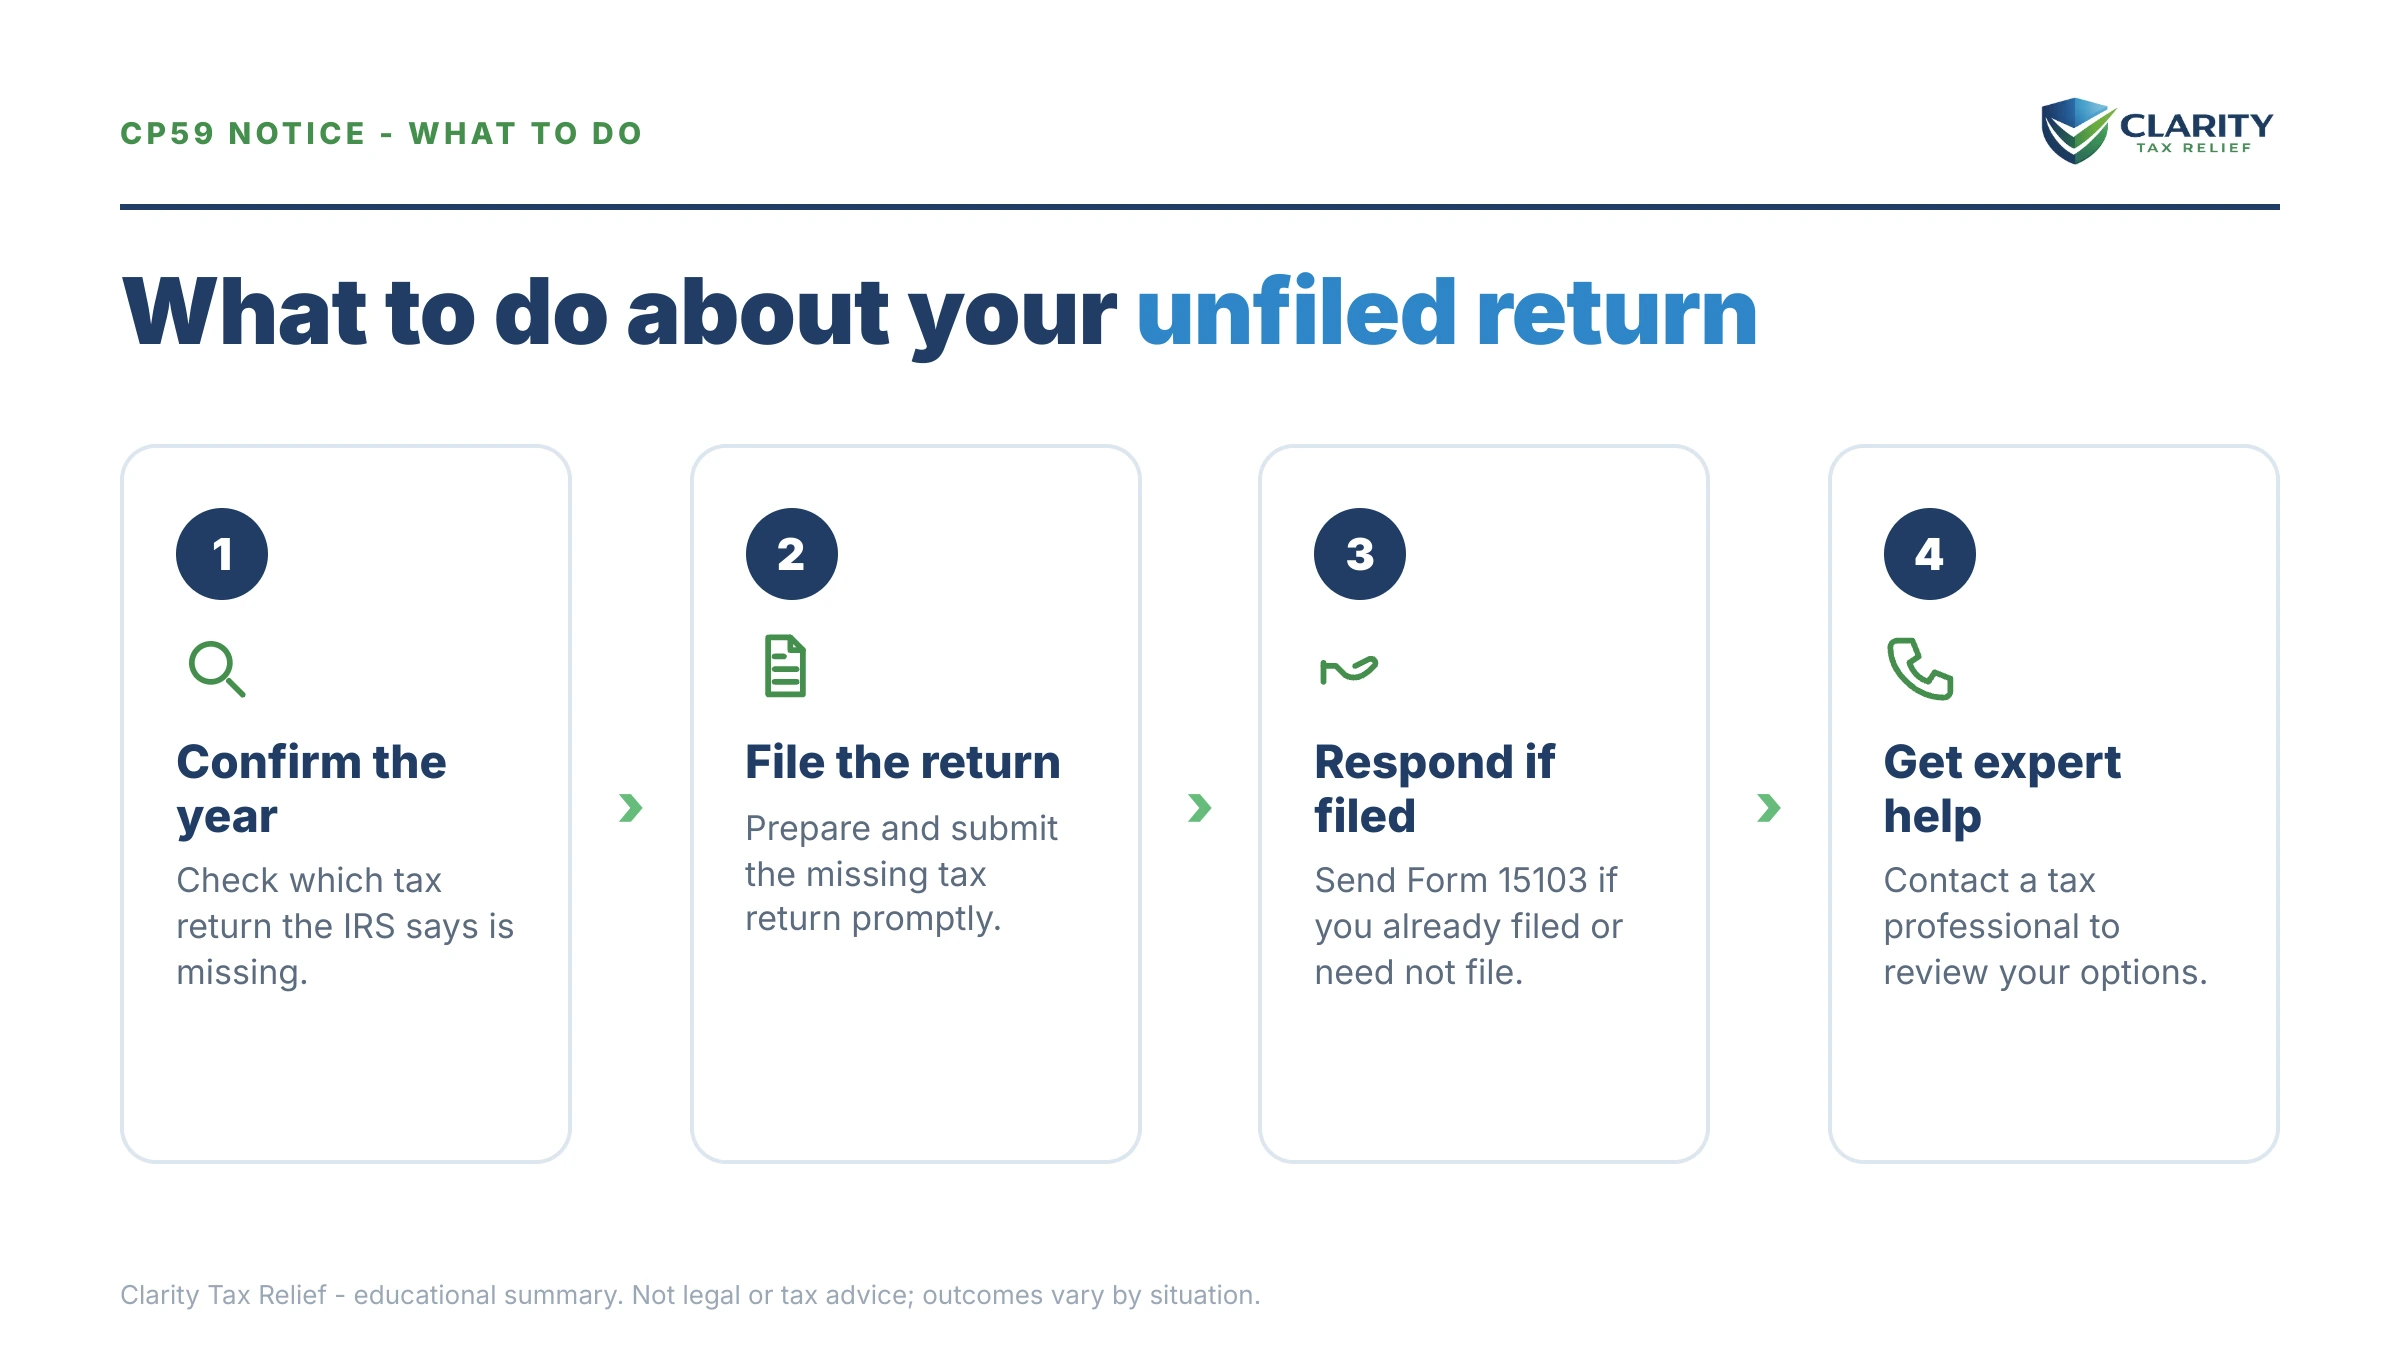
Three routes, all listed on the IRS's CP59 page. Mail the form or return to the address printed on your notice. Fax it to the fax number on the notice. Or sign in to your IRS Online Account and submit Form 15103 there as a mobile-friendly form, which is the fastest way to get a "not required to file" or "already filed" answer in front of a person.
A return you are filing for the first time follows different rules. The IRS accepts prior-year returns electronically only for the two most recent tax years, through an e-file provider. Anything older goes in on paper, signed and dated, to the address on the notice. If you have an Identity Protection PIN, put it on the return. Keep proof of mailing either way. If you are mailing both a return and the form, put them in the same envelope so they land in the same file.
Were you required to file that year at all?
Clarity Tax Relief checks the filing requirement before preparing anything. If Social Security was your only income for the year on your CP59, you likely had no filing requirement. Benefits alone generally are not taxable, and gross income for the filing-requirement test often excludes them. In that case the right response is Form 15103 with the "not required to file" explanation, sent to the address on the notice, faxed, or submitted through your Online Account.
The math changes the moment other income enters: a pension, an IRA or 401(k) withdrawal, interest and dividends, a brokerage sale, or part-time 1099 work. Any of those can push you over the threshold and make up to 85% of your benefits taxable. Our retired and owe back taxes guide walks through how fixed-income filers end up owing without ever getting a paycheck.
Do not skip the response because you believe you are exempt. The computer that mailed your CP59 does not know your income mix. It only knows no return posted. Silence reads as delinquency, and the sequence below keeps moving.
Why file when no tax is due?
Clarity Tax Relief looks for refundable credits in every missing year. People treat a missing year as a liability, and often it is the opposite. Federal income tax returns are also how refundable tax credits are claimed, and if you never filed your tax return for that year, nothing was claimed on your behalf.
There is a deadline on that, and it is the part worth acting on. A refund has a claim window, and once it closes the money stays with the Treasury whatever the return would have shown. So the older the unfiled year, the more urgent it is to look at, which is the reverse of how most people rank them.
What happens if you ignore a CP59 notice?
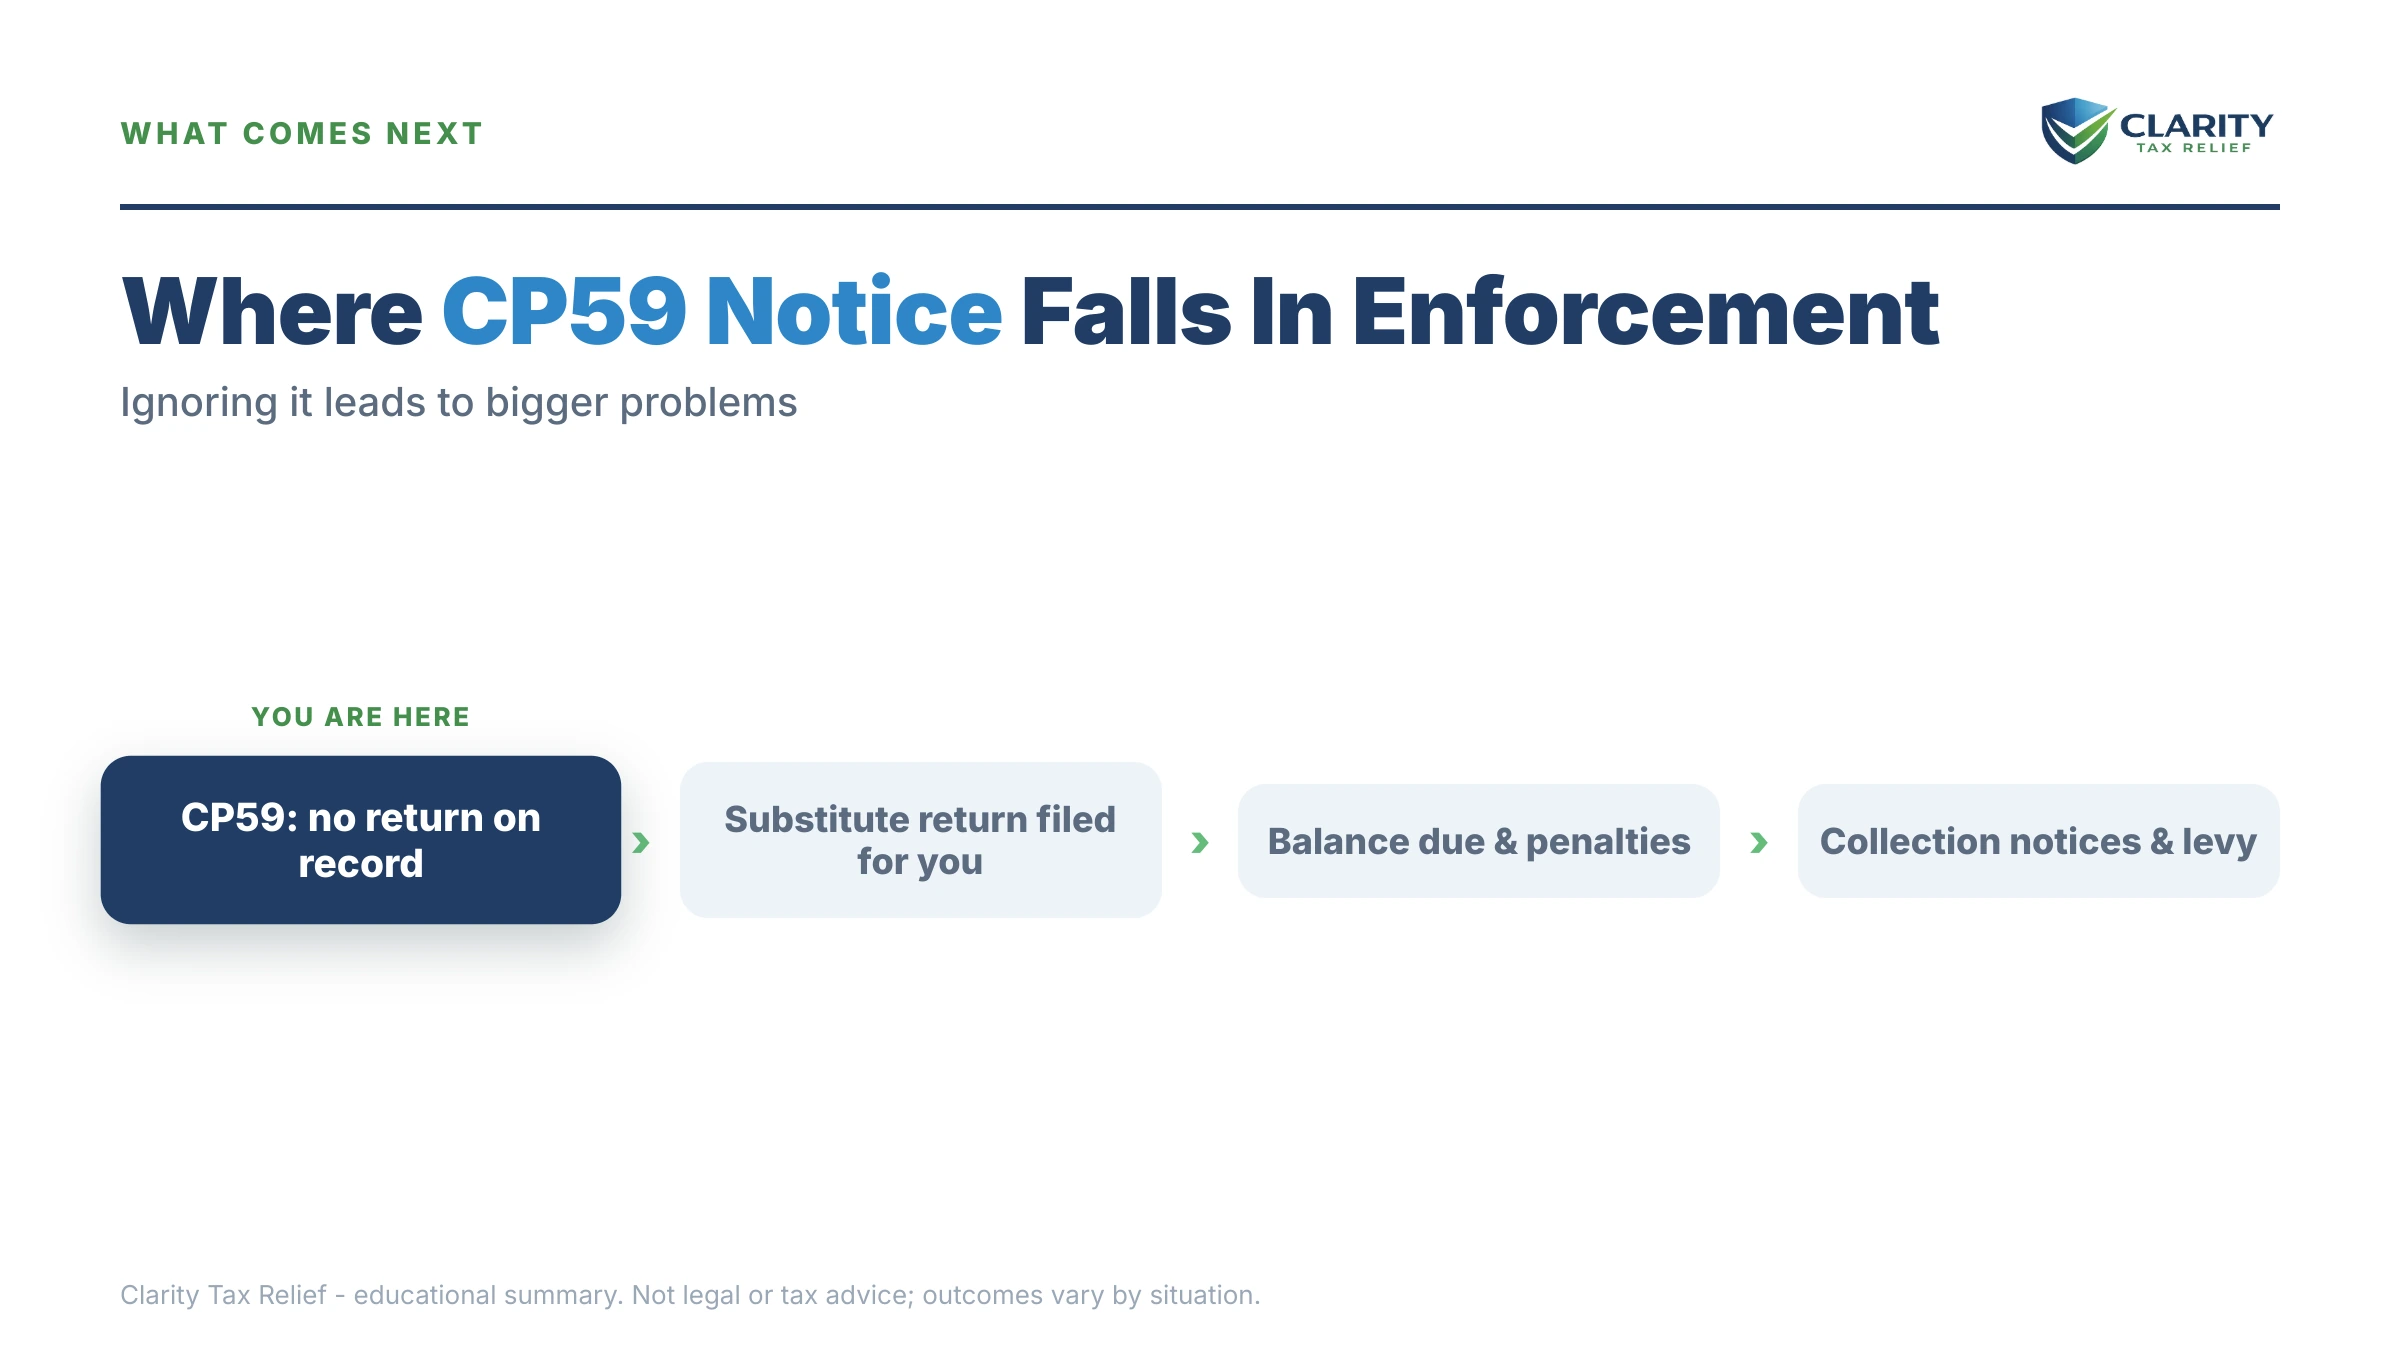
Ignoring a CP59 leads to a substitute for return, a tax return the IRS prepares for you using the worst assumptions the law allows. The IRS's CP518 page says it plainly: if you don't respond, the IRS may calculate your taxes for you, penalties and interest keep accruing, and any refund you are owed can be delayed. The non-filer track runs on its own automated sequence, and each stage takes options off the table.
“Ignore a CP59 and the IRS may prepare a substitute return for you, built on the worst assumptions the law allows,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
| Notice | What the IRS says | Your response |
|---|---|---|
| CP59 | No record of your prior year personal tax return | File the return, or send Form 15103 by mail, fax or Online Account |
| CP516 | Second request: a previous notice went out and there is still no record of a return | Same as CP59; Form 15103 is still the response form |
| CP518 | Final reminder before the IRS stops asking | Same as CP59; the last stage where nothing has been calculated |
| CP2566 | The IRS calculated your tax, penalty and interest from the income reported to it | File your own return by the date on the notice, or accept and pay the proposed amount |
| CP3219N | Notice of deficiency on those calculated figures | File the return, or petition Tax Court within 90 days (150 days if you are outside the country) |
| Assessment | The proposed balance becomes a legal debt and billing begins | Payment plan, hardship status or an amended-style original return to replace the SFR figures |
In more detail:
- CP59, first request. You are here. Nothing has been assessed, and you control what goes in the file.
- CP516, second request. Same demand, firmer language. Still no assessment.
- CP518, final notice. The IRS's last request before it stops asking and starts calculating.
- CP2566, the substitute for return (SFR) proposal. The IRS drafts your return itself: single or married-filing-separately status, no dependents, no itemized deductions, and, critically, zero cost basis on anything a broker reported. The substitute for return is legal to assess and almost always overstates what you would owe on a real return.
- CP3219N, notice of deficiency. A statutory 90-day window (150 days if you are outside the United States) to petition Tax Court before the SFR numbers become a legal assessment.
- Assessment and collection. The inflated balance is now legally owed. Billing notices begin, penalties and interest compound, a federal tax lien becomes possible. The account moves toward levy, including the Federal Payment Levy Program, which can take up to 15% of Social Security benefits.
Two quieter consequences run alongside the notices. First, the IRS can hold your current refunds while a prior year sits unfiled. Second, an unfiled year never expires: the statute of limitations on assessment never starts until a return is filed, so the year stays open indefinitely. The notice stream, SFR program, and levy systems are automated, and they do not pause for staffing.
Holding a CP59 for a year you can't reconstruct?
The substitute-return process builds your worst-case tax bill from documents you may not even have copies of. Send us the notice and an experienced tax professional will pull the IRS's own records for that year, tell you whether you even had to file, and map the cheapest way to close it. Free and confidential.
Your options after a CP59: file, prove it, or explain
Clarity Tax Relief picks one of these three answers for every CP59. Every CP59 has one of three correct responses: file the missing return, prove you already filed it, or show you were not required to. Which one fits, and what goes in the envelope, depends on your situation:
| Your situation | Send this | What it does |
|---|---|---|
| You already filed for that year | Signed copy of the return + Form 15103 | Lets the IRS match the return to your account and close the delinquency |
| You weren't required to file | Form 15103 with the explanation completed | Closes the filing requirement for that year; no return needed |
| You need to file and can pay | The original signed return + payment | Stops the failure-to-file penalty and ends the notice sequence |
| You need to file and can't pay | The return anyway, then a payment-plan request | Filing alone stops the 5%/month penalty; the balance is a separate, solvable problem. See file even if you can't pay |
| Several years are unfiled | Usually the most recent six years | IRS policy generally requires six years to get compliant. See how many years of back taxes you have to file |
| The notice covers a deceased spouse's year | The final return, filed by the survivor or executor | Closes the decedent's filing requirement and stops notices to the estate |
One thing that is not on the menu: negotiating the balance before a return exists. Payment plans, hardship status, and settlement programs all require the year to be filed first. Filing is the key that opens every other option. If several years are open, our unfiled tax returns service rebuilds them from the IRS's own records; start with a free case review.
What does waiting cost? A worked example at $83,100
Say you are 68, single, and in the year on your CP59 your income documents totaled $83,100: $48,000 in gross proceeds from selling brokerage funds (reported on a 1099-B), a $13,000 pension (1099-R), and $22,100 in Social Security benefits (SSA-1099). This is hypothetical, but the mechanics are how the SFR math works.
If you never respond and the IRS builds a substitute return, it treats the entire $48,000 of proceeds as pure gain (the SFR assumes your cost basis is zero), stacks the pension and the maximum taxable share of your benefits on top, and allows only the single standard deduction. Say that produces a proposed tax of roughly $10,800. Add the capped failure-to-file penalty (25% × $10,800 ≈ $2,700), plus the 0.5%-per-month failure-to-pay penalty and interest, which runs at 7% for the fourth quarter of 2026 and compounds daily. The assessed bill can push past $14,000.
Now the real return. Suppose you paid $41,000 for those funds. Your true gain is $7,000 rather than $48,000. With $7,000 of gain, the $13,000 pension, the correctly computed taxable slice of Social Security and your standard deduction, the tax might land around $1,800. Even with the full 25% late-filing penalty (≈ $450) plus interest, you are near $2,400 instead of $14,000, and penalty relief could shrink that further. You can rough out your own penalty and interest exposure with our Penalty & Interest Calculator; it estimates, it does not promise.
The IRS is not being unfair here. A substitute return legally cannot include facts only you know. Filing is how those facts get into the record.
How to respond to a CP59 notice, step by step
- Pull the year's income records. Request your wage and income transcript for the year on the notice. It lists every W-2, 1099, and SSA-1099 the IRS received under your SSN, so your return matches what the IRS already knows.
- Confirm whether you were required to file. Compare that year's gross income (Social Security often does not count toward the threshold) against the filing requirement for your age and filing status.
- File the return or return Form 15103. Mail the original signed return, or Form 15103 explaining that you already filed or were not required to, to the address printed on the CP59, and keep proof of mailing. Form 15103 can also go by fax or through your IRS Online Account.
- Handle any balance the same day. Pay what you can at IRS.gov/payments, or request a payment plan when you file. Filing stops the 5%-per-month failure-to-file penalty even if you cannot pay anything yet.
- Request penalty relief after the return posts. Ask for first-time penalty abatement or reasonable-cause relief on the failure-to-file penalty once the IRS processes the return and bills you.
- Verify the year is closed. Check your account transcript in 6 to 8 weeks for a code 150 (return posted) and confirm no delinquency notices are still queued for that year. Our IRS transcript codes guide decodes the rest of what you will see there.
Deadlines and rights on an unfiled year
An unfiled year runs on different clocks than an ordinary tax bill, and several of them work against you the longer you wait:
| Clock | How long | What it means for you |
|---|---|---|
| Refund claim window | Generally 3 years from the return's original due date | File late but inside the window and you still get the refund; miss it and the money is forfeited permanently |
| Failure-to-file penalty | 5% of unpaid tax per month, capped at 25% | Hits the cap in five months, ten times harsher than the 0.5%/month failure-to-pay penalty. Returns due in 2026 and more than 60 days late carry a $525 minimum (or 100% of the tax, if less) |
| Assessment statute (ASED) | Never starts until a return is filed | An unfiled year stays open to IRS assessment indefinitely. It does not age out |
| Collection statute (CSED) | 10 years, but only from the date of assessment | No expiration protection exists while nothing is assessed; the clock you may be counting on isn't running |
| Interest | 7% for the fourth quarter of 2026, compounded daily | Runs on the unpaid tax and on penalties from their own start dates, until paid in full |
| CP3219N Tax Court window | 90 days from the notice of deficiency (150 days outside the United States) | Your last chance to contest SFR numbers before they become a legal debt. Filing your own return before this stage avoids it entirely |
Red flags to check before you mail anything
- The name, SSN or tax year on the notice does not match your records. The IRS's own instructions say to check all three against the return before you send a copy.
- You filed within the last eight weeks. The IRS says no response is needed; the return is probably still processing.
- The return went in under your spouse's SSN. A joint return posts to the first-listed number. Send a signed copy and say so on Form 15103.
- A brokerage 1099-B is in the mix. A substitute return assumes zero cost basis, so the IRS's version of that year will be far larger than yours.
- The year is close to the 3-year refund window. Once it closes, the refund stays with the Treasury.
- The copy you are sending is unsigned. An unsigned copy is not verification.
- A CP2566 or CP3219N has already arrived. The IRS has calculated your tax. Filing your own return is still the answer, but the 90-day Tax Court window on a CP3219N is a hard stop.
Can you handle a CP59 yourself?
You can usually resolve a CP59 on your own when it covers a single year, you have (or can reconstruct) your records, and you are either due a refund or owed nothing. Downloading the transcript, preparing one return, and mailing it with Form 15103 is a do-it-yourself job. If you qualify by income, free preparation help exists through Low Income Taxpayer Clinics and volunteer programs, and the Taxpayer Advocate Service can step in when the IRS itself is the bottleneck.
Experienced help changes the outcome in a narrower set of situations: an SFR has already been proposed or assessed (unwinding one is harder than preventing it), multiple years are unfiled, the year includes brokerage sales where zero-basis math inflates the bill, there is self-employment income with reconstruction work to do, or you are a surviving spouse or executor filing for someone who is gone. In those cases, the sequence you fix things in (returns first, then penalties, then the balance) often determines what you ultimately pay.
The IRS's own explainer, Understanding your CP59 notice, confirms the response options straight from the source. If you end up on the phone with the IRS about it, our 188-call hold-time study shows which hours get through.
Terms on your notice, decoded
- Form 15103 (Form 1040 Return Delinquency): the response form attached to your CP59, how you tell the IRS you already filed or were not required to.
- Substitute for return (SFR): a return the IRS prepares for you from third-party documents, using the least favorable filing status, no deductions beyond the standard, and zero cost basis.
- Failure-to-file penalty: 5% of the unpaid tax per month a return is late, capped at 25%, charged on top of the smaller failure-to-pay penalty.
- Refund statute of limitations: the roughly 3-year window from a return's original due date to file and still collect a refund for that year.
- ASED (assessment statute expiration date): the deadline for the IRS to assess tax for a year. It does not begin until you file, so an unfiled year never closes.
- Notice of deficiency: the formal letter (CP3219N on the non-filer track) that gives you 90 days to challenge proposed tax in Tax Court before it is assessed.
The bottom line on a CP59 notice
A CP59 is the IRS asking one question: where is the return for that year? Answer it once, in writing, and the sequence stops. File the return if one was due. Send a signed copy with Form 15103 if you already filed. Explain on Form 15103 if you were not required to file. Silence is the only response that costs you, because it leads to a substitute return built on zero cost basis and no deductions, and it keeps an unfiled year open forever. If a refund is sitting in that year, the 3-year window makes the oldest year the most urgent one.
CP59 notice questions, answered
What is a CP59 notice from the IRS?
A CP59 is the IRS notice that says it has no record of your personal tax return for a prior year. Income documents such as a W-2, 1099-R or SSA-1099 reached the IRS under your Social Security number and no matching Form 1040 posted. It asks you to file the return now or explain why you do not need to, and it comes with Form 15103 for that explanation.
What do I do if I already filed the return the CP59 asks about?
If you filed within the last eight weeks, the IRS says you do not need to do anything; the return is probably still in processing. If it was longer ago, send a signed and dated copy of the return with Form 15103, and check that the name, Social Security number and tax year on the return match the notice. Keep proof of mailing and watch your account transcript for a code 150.
What if I need to file the return?
File it now. The IRS accepts prior-year returns electronically only for the last two years, so older years go in by mail as a signed paper return to the address on the notice. If you owe and cannot pay in full, file anyway and request a payment plan. Filing stops the failure-to-file penalty, which is ten times the failure-to-pay rate.
What if I was not required to file for that year?
Complete the section of Form 15103 that says you do not think you were required to file, give your filing status and total income for that year, and sign it. If Social Security benefits were your only income, this is usually the right answer. Send it even though you owe nothing, because the IRS computer only knows that no return posted.
Where do I send Form 15103 or my return?
Use the address or fax number printed on your CP59, and the enclosed envelope if you have it. The IRS also accepts Form 15103 through your IRS Online Account as a mobile-friendly form. A newly filed return goes by mail or, for the last two tax years, by e-file.
What happens if I ignore a CP59 notice?
The IRS sends a CP516 second request and a CP518 final reminder. If there is still no return, it calculates the tax itself from the income reported to it and sends a CP2566 with the proposed amount, then a CP3219N notice of deficiency with 90 days to petition Tax Court. After that the IRS assesses the balance and collection begins. Penalties and interest run the whole time.
Can I still get a refund for the year on the CP59?
Only if you file in time. The IRS states that the time to claim a refund is generally three years from the date the return was due or filed, or two years from the date the tax was paid, whichever is later. For a return that was never filed, that means roughly three years from its original due date. Miss the window and the refund is forfeited.
What penalties apply to the year on a CP59?
If you owe tax, the failure-to-file penalty is 5% of the unpaid tax for each month or part of a month the return is late, up to 25%, with a minimum of $525 for returns due in 2026 that are more than 60 days late. The failure-to-pay penalty is 0.5% per month. Interest runs at 7% for the fourth quarter of 2026 and compounds daily. If you are owed a refund, there is no failure-to-file penalty.
Your next 24 hours
- Find the tax year and Form 15103 on your CP59. The year is printed near the top; the response form is attached. Those two items define exactly what the IRS is asking for.
- Gather what you have for that year: any SSA-1099, 1099-R, or brokerage statements, your last filed return, and, if you believe you already filed, a copy or proof of mailing. If your records are gone, the IRS's own transcript can rebuild them.
- Get a free case review. Call (888) 825-7779 or use the 2-minute form. The failure-to-file penalty grows monthly and the substitute-return track only moves one direction. A CP59 answered now is the cheapest this year will ever be to close.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.
Read the transcript
Host: So you've got a letter in your hand that says the IRS has no record of a tax return from you. And you're pretty sure you filed. Or you're pretty sure you didn't have to. Either way, it's a CP59.
Tax specialist: Right. And the first thing worth saying is what a CP59 isn't. It isn't a bill. There's no amount due printed on it, because nothing's been assessed yet. It's the IRS asking a question.
Host: Which question?
Tax specialist: "We have income documents under your Social Security number for this year, and we don't see a Form 1040 that matches. What happened?" That's it. Their computer matched paperwork to your SSN, looked for a return, found nothing.
Host: And the paperwork is usually what, a W-2?
Tax specialist: For retirees, almost never. It's an SSA-1099 for Social Security, a 1099-R for a pension or an IRA distribution, or a 1099-B if you sold something at a brokerage. The payers sent copies to the IRS whether or not you filed anything.
Host: Hm. So they're not guessing.
Tax specialist: They're holding the documents. But, and this matters, a CP59 doesn't mean you did something wrong. There are three totally innocent explanations that come up constantly. One, you filed and it never processed. Paper returns can sit for months, and IRS staffing is down roughly twenty-seven percent since 2025. Two, you filed jointly and your spouse was listed first, so the return posted under their number, not yours. Three, you really weren't required to file.
Host: That third one. If Social Security is all somebody's got...
Tax specialist: Then there likely was no filing requirement. Benefits alone generally aren't taxable, and the gross income test for whether you have to file often excludes them entirely.
Host: Okay, so that person can just ignore the letter.
Tax specialist: No. No, that's the trap. The computer that mailed the CP59 doesn't know your income mix. It knows one thing: no return posted. Silence reads as delinquency and the sequence keeps moving.
Host: Say more about the sequence.
Tax specialist: There's a form attached to your CP59 called Form 15103. Form 1040 Return Delinquency. That's where you say "I already filed, here's a copy," or "I wasn't required to file, and here's why." That's the whole response for a lot of people. One envelope.
Host: Form 15103. And if nothing goes in the envelope?
Tax specialist: Then it's CP516, second request. Then CP518, which is the final one. That's the IRS's last ask before it stops asking. Then CP2566.
Host: What's CP2566?
Tax specialist: That's where the IRS prepares your return for you. It's called a substitute for return. And it's built on the least favorable assumptions the law allows: single or married filing separately, no dependents, no itemized deductions, and this is the one that hurts, zero cost basis on anything a broker reported.
Host: Wait. Zero basis meaning...
Tax specialist: Meaning if you sold forty-eight thousand dollars of brokerage funds, the IRS treats all forty-eight thousand as gain. Not the gain. The whole thing.
Host: Even though you paid for those funds.
Tax specialist: They don't know what you paid. Only you know that. The article walks a hypothetical: sixty-eight years old, single, eighty-three thousand one hundred in income documents for the year. Forty-eight thousand of brokerage proceeds, a thirteen-thousand-dollar pension, twenty-two thousand one hundred in Social Security. Substitute return math produces a proposed tax of roughly ten thousand eight hundred, and once you stack the capped failure-to-file penalty and the failure-to-pay penalty and interest, the assessed bill can push past fourteen thousand.
Host: And the real return?
Tax specialist: Say the funds actually cost forty-one thousand. Your true gain is seven thousand, not forty-eight. Same pension, correctly computed slice of benefits, standard deduction, the tax might land around eighteen hundred. Even with the full late-filing penalty you're near twenty-four hundred instead of fourteen thousand.
Host: That's a hypothetical, to be clear.
Tax specialist: Completely hypothetical. But the mechanism is real, and the point isn't that the IRS is being unfair. A substitute return legally can't contain facts only you have. Filing is how those facts get into the record.
Host: Okay. After CP2566?
Tax specialist: CP3219N. Notice of deficiency. Ninety days to petition Tax Court before those numbers become a legal assessment. And filing your own return before that stage avoids the whole thing.
Host: Ninety days. Then it's a real debt.
Tax specialist: Then it's assessed. Billing notices, penalties and interest compounding, a federal tax lien becomes possible, and the account moves toward levy, including the Federal Payment Levy Program, which can take up to fifteen percent of Social Security benefits.
Host: Let's do the clocks, because I think people get this backwards.
Tax specialist: They do. Failure-to-file penalty is five percent of unpaid tax per month, capped at twenty-five percent. It hits the cap in about five months. The failure-to-pay penalty is half a percent per month, so late filing is ten times harsher than late paying. That's the whole argument for filing even when you can't pay a dime.
Host: And the refund side?
Tax specialist: Generally three years from the return's original due date to claim a refund on an old year. Miss that window and the money is forfeited permanently. And plenty of retirees with withholding on pension or IRA distributions are owed money on unfiled years and don't know it.
Host: Now the one I hear people count on. Doesn't the IRS only have ten years?
Tax specialist: Ten years from the date of assessment. And the assessment clock never starts until a return is filed. So an unfiled year doesn't age out. It stays open indefinitely, and the ten-year collection clock you might be waiting on isn't running at all.
Host: Oh. That's the part people miss.
Tax specialist: That's the part people miss. And separately, the IRS can hold your current-year refunds while a prior year sits unfiled.
Host: So what actually goes in the envelope? Give it to me simply.
Tax specialist: Three correct answers, pick the one that's true. Already filed: signed copy of the return plus Form 15103. Wasn't required to file, Form 15103 with the explanation. Need to file, the original signed return, with payment if you can, and a payment-plan request if you can't. If several years are unfiled, IRS policy generally looks for the most recent six.
Host: Six years.
Tax specialist: And one thing is not on the menu: negotiating a balance before a return exists. Payment plans, hardship status, settlement programs, every one of those requires the year to be filed first. Filing is the key that unlocks the rest.
Host: What about getting the penalty knocked off?
Tax specialist: You ask after the return posts, not before. First-time abatement has a criterion, a clean compliance record for the prior three years. Reasonable cause is the other path: serious illness, a death in the family, a disaster. And since summer 2026 the IRS applies automatic penalty relief to eligible returns processed after it started, but a 2025 return processed before that still needs a first-time abatement request. Whether any of it applies to your facts is decided by the IRS, not by me.
Host: Fair. Can somebody do this themselves?
Tax specialist: Honestly, often yes. One year, records you have or can rebuild, and you're either owed a refund or owe nothing. Pull the wage and income transcript, prepare the return, mail it to the address on the notice, keep proof of mailing. There are free volunteer preparation programs if you qualify by income, and the Taxpayer Advocate Service exists when the IRS itself is the bottleneck.
Host: And when is it not a do-it-yourself job?
Tax specialist: When a substitute return has already been proposed or assessed, because unwinding one is harder than preventing it. Multiple unfiled years. Brokerage sales, because of that zero-basis math. Self-employment income you have to reconstruct. Or you're a surviving spouse or an executor filing for someone who's gone. In those, the order you fix things in (returns, then penalties, then the balance) drives what you end up paying.
Host: Last thing. The fear nobody says out loud.
Tax specialist: Jail. A CP59 is a civil notice. Criminal prosecution for failure to file is reserved for willful cases, years of high income, deliberate concealment. Filing voluntarily, now, is what keeps a case on the civil track.
Host: So today: find the tax year printed near the top of your CP59, find the Form 15103 attached to it. Those two things define what the IRS is asking for.
Tax specialist: Gather whatever you have for that year: SSA-1099, 1099-R, brokerage statements, your last filed return. If the records are gone, the IRS transcript can rebuild them. And in six to eight weeks, check your account transcript for a code 150 for that year. That's the return posting.
Host: Code 150. Got it. And if you'd rather have someone pull the IRS's own records for that year and tell you whether you even had to file, Clarity's Enrolled Agents do a free, confidential case review. 888-825-7779.
Tax specialist: Nothing's been assessed at the CP59 stage. That's the one advantage you have. Use it while you've got it.