
IRS Notices
IRS CP63 Notice: Missing Return, Local Office, and Your Held Refund
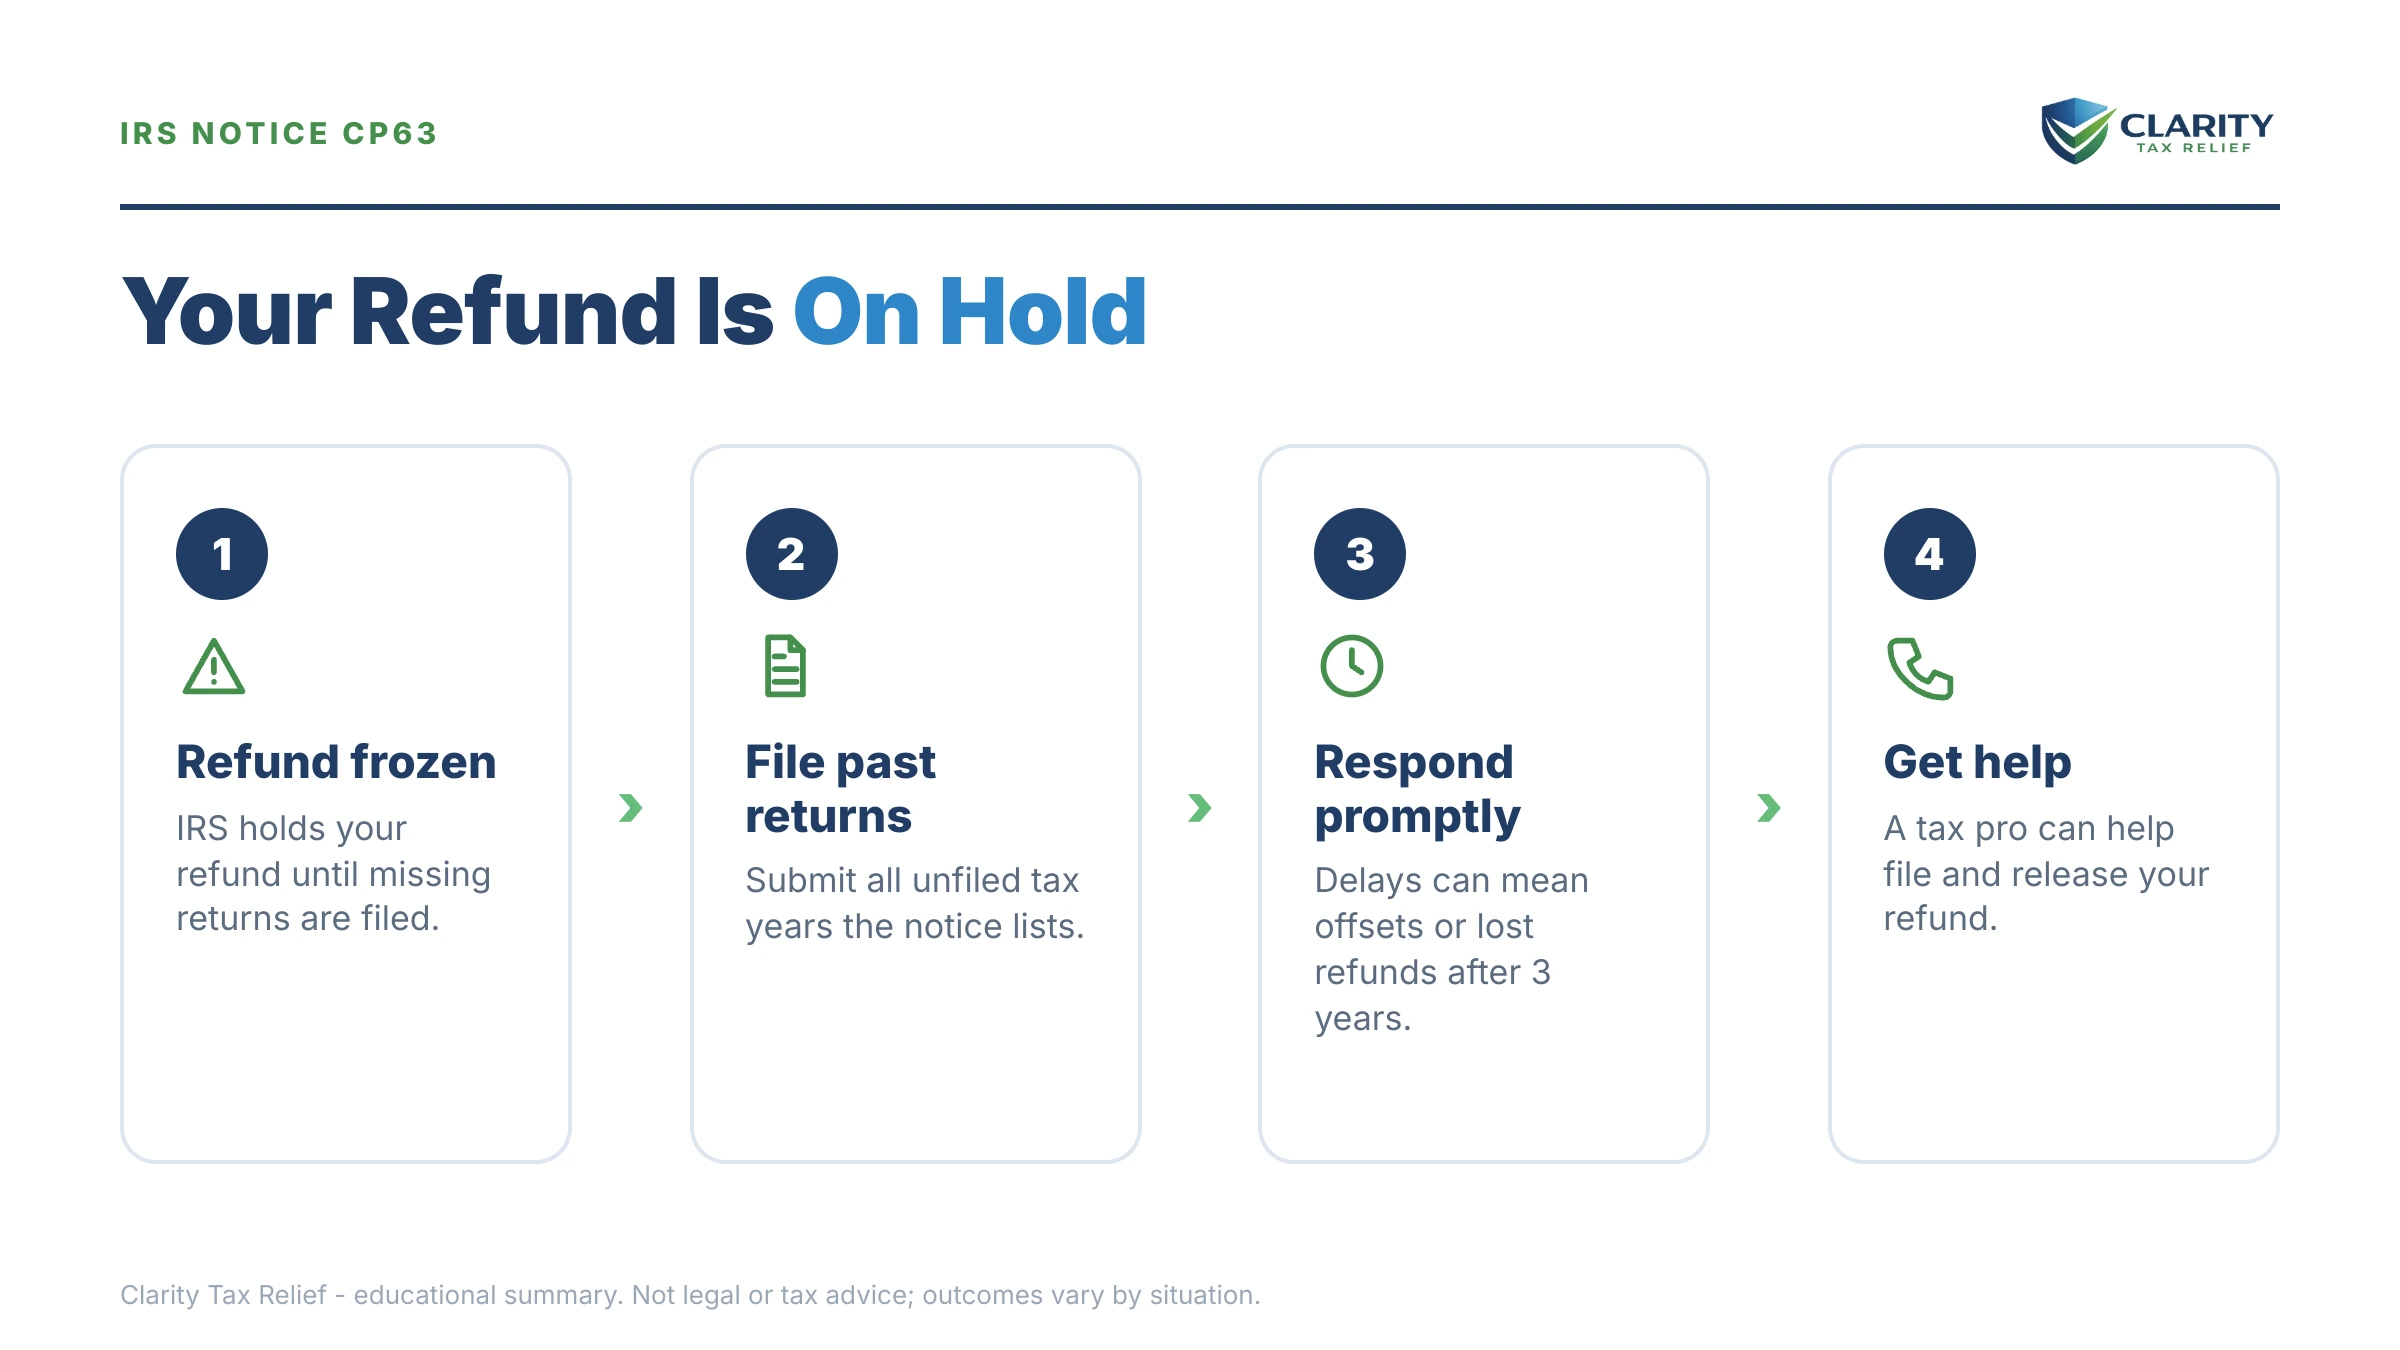
The short answer: an IRS CP63 notice means the IRS is holding your entire tax refund because its records show you haven't filed one or more prior-year returns, and it believes those returns may show tax due. The refund stays frozen until you file the missing years or prove you weren't required to file. Clarity Tax Relief treats the missing years as the whole job, because filing them is what frees the refund.
This guide covers the IRS CP63 notice: why the IRS is holding this year's refund over a past year you never filed, the three responses the notice accepts, what happens if you ignore it, what the held money does once the missing return posts, and how to file that return without records. You filed on time, watched "Where's My Refund" for weeks, and instead of a deposit you got a letter. That is the CP63 in one sentence. This year's refund is being held hostage by a past year's paperwork.
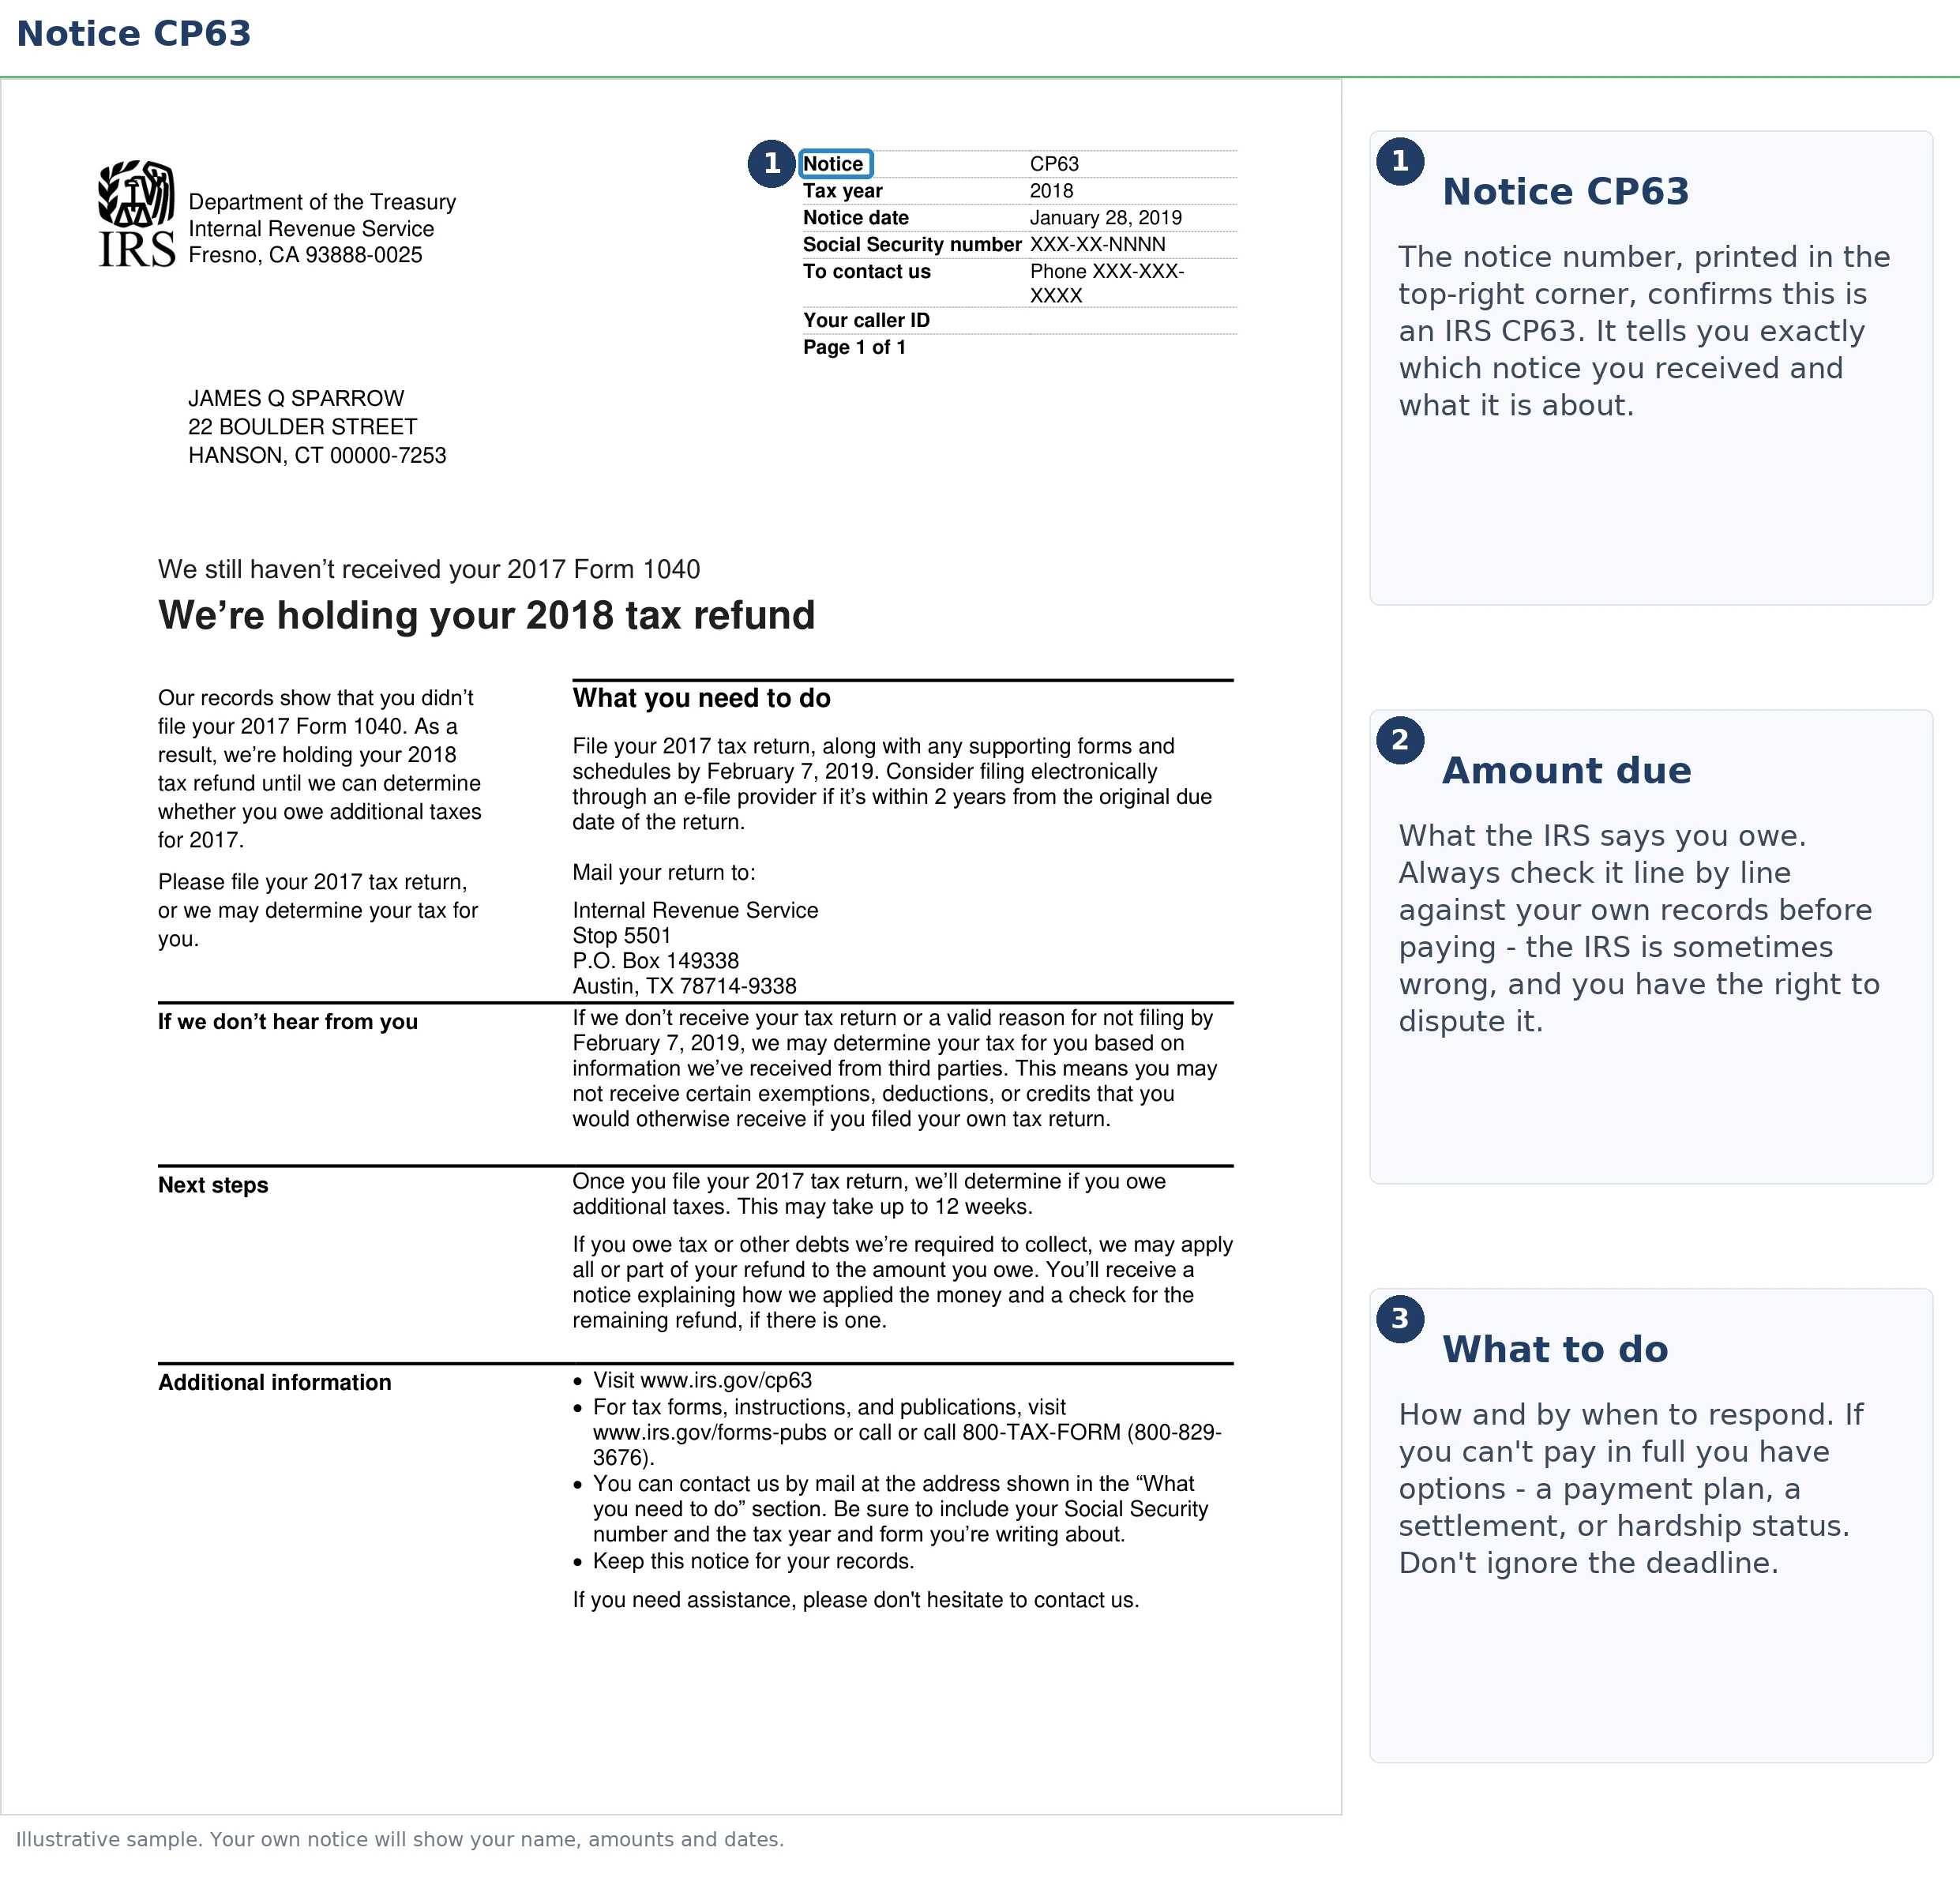
Unlike most IRS letters, the CP63 tells you the exact fix. File the year or years it names, and the hold has a defined end. The image below shows what a CP63 looks like and where to find the specific tax years the IRS says are missing. Those years are your entire to-do list.
Updated October 5, 2026. Every IRS figure on this page was checked against IRS.gov that week: the failure-to-file penalty, the minimum late-filing penalty, the interest rate for the quarter that began October 1, 2026, and the IRS's own processing and contact guidance for this notice.
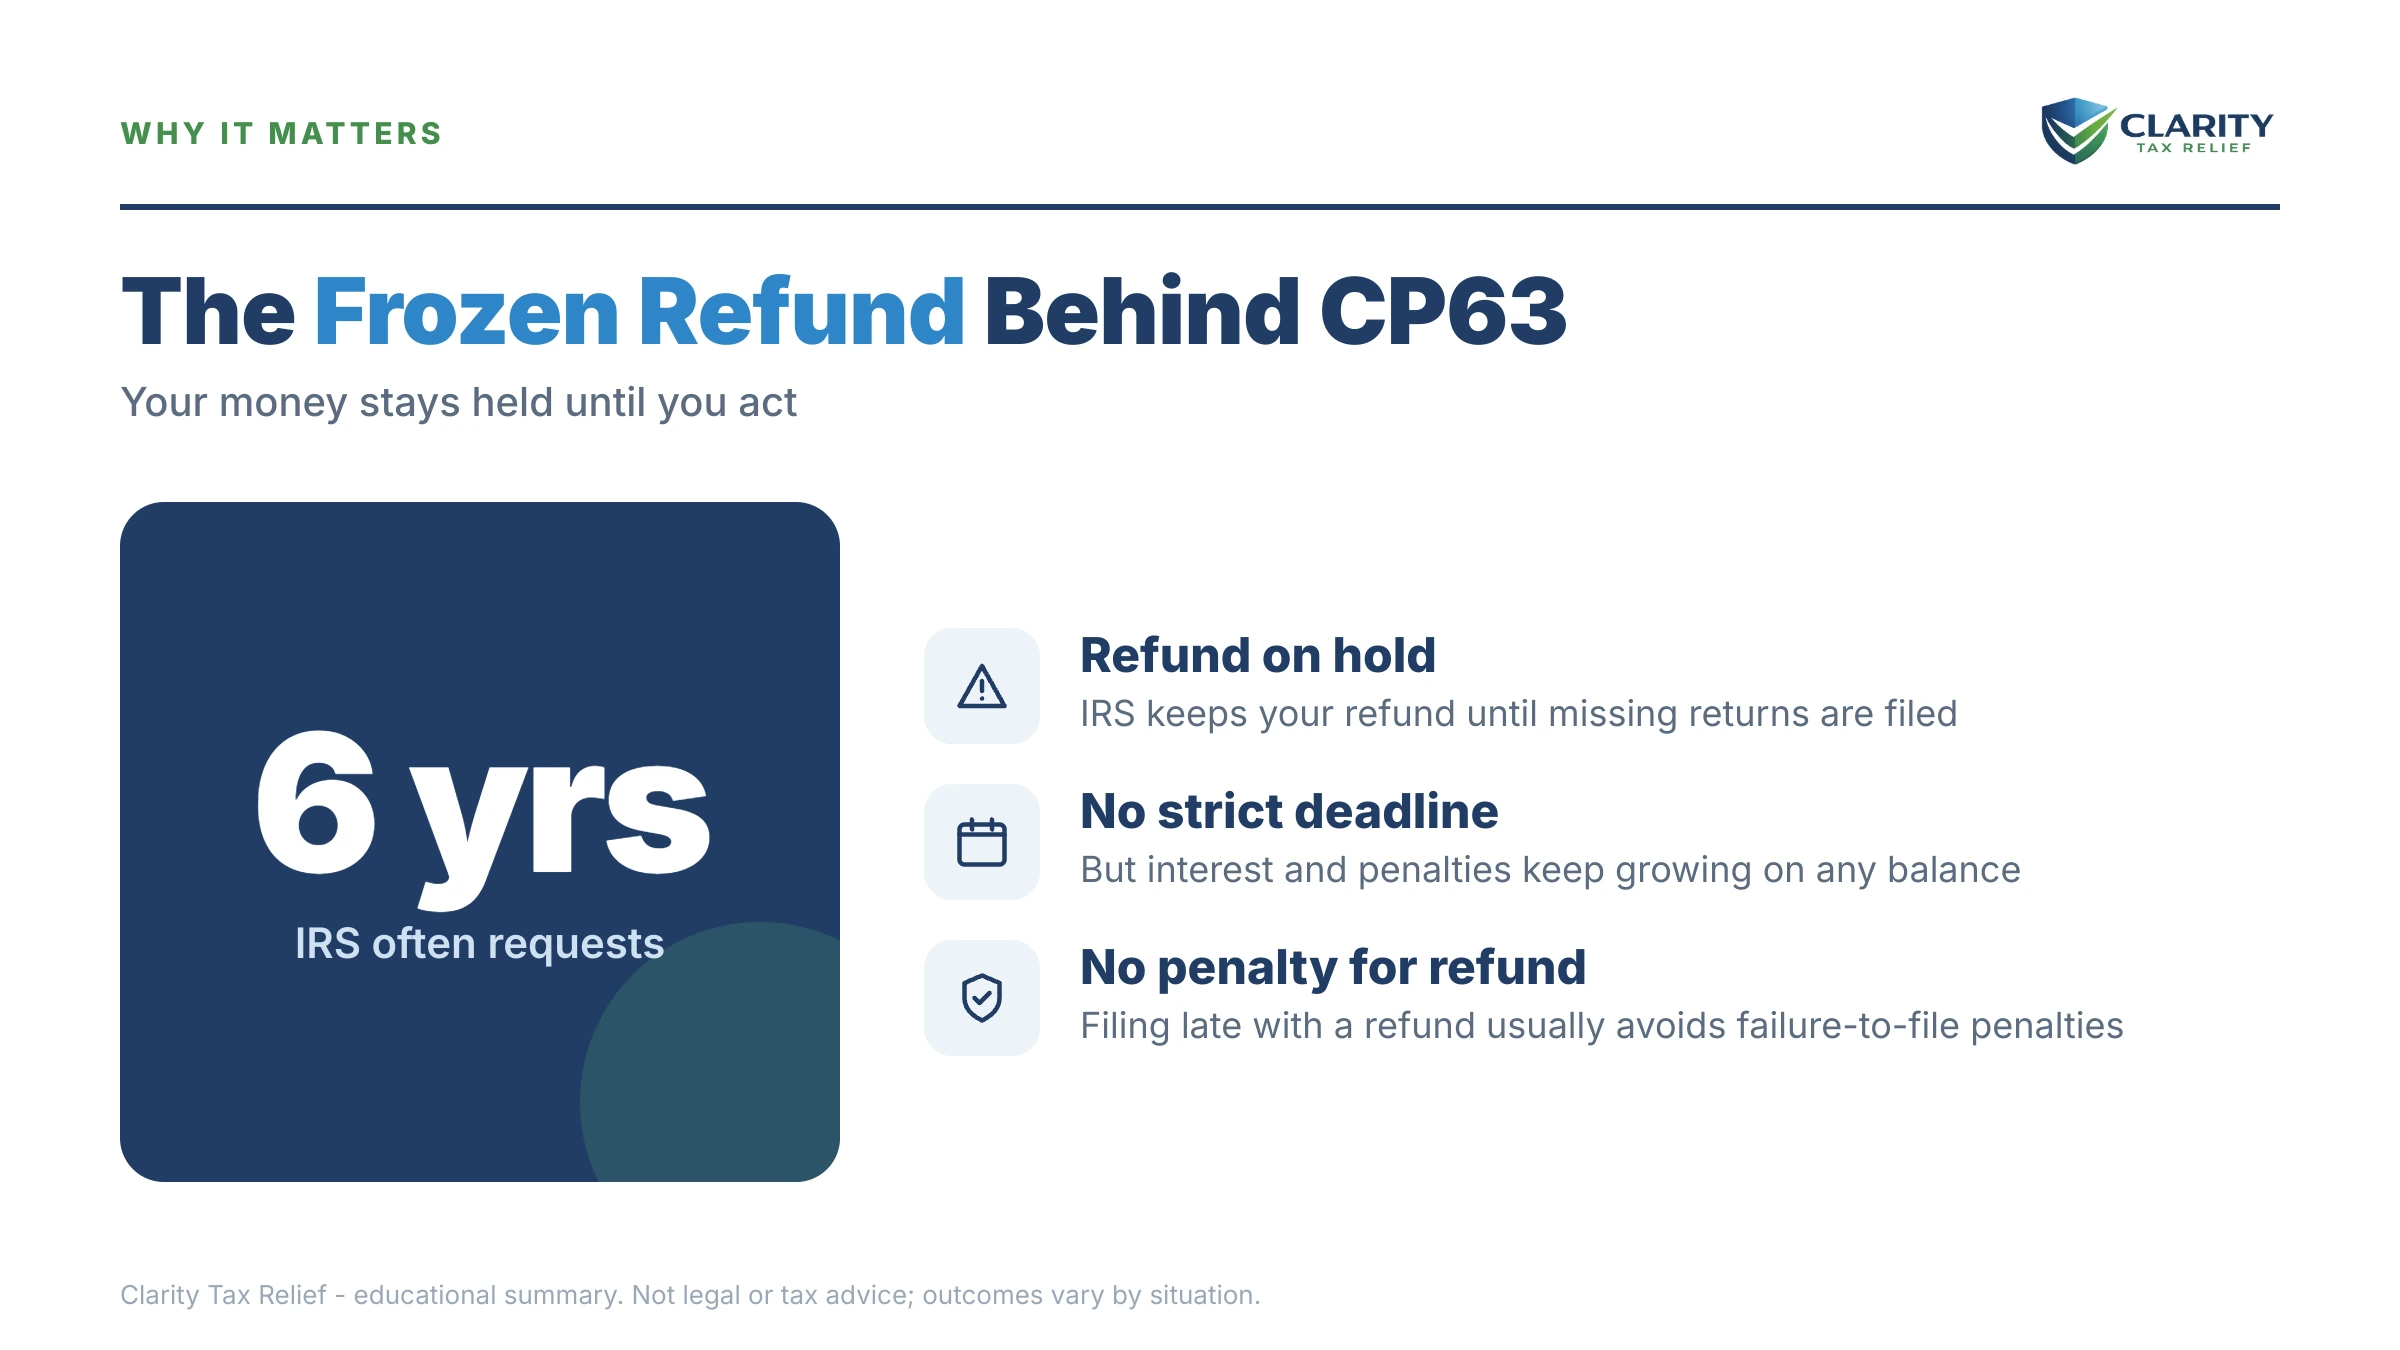
⏱ The real clock: a CP63 has no printed response deadline; the hold is open-ended until you act. But two clocks are running anyway. If the unfiled year owes tax, the failure-to-file penalty grows at 5% per month, up to a 25% cap, plus interest (7% per year, compounded daily, for the quarter beginning October 1, 2026). And if the unfiled year was owed a refund, you generally have only 3 years from that return's due date to claim it before it is gone permanently.
Why did the IRS send you a CP63 notice?
The IRS sends a CP63 when it processes a return claiming a refund while its records show at least one unfiled prior-year return it believes will show tax due. The trigger is automated. Employers, banks, brokerages, and payment platforms send the IRS copies of your W-2s and 1099s every year. When those documents exist for a year with no return attached, and the income looks big enough to create a tax bill, the system flags you.
Then, the moment you file a return with a refund on it, the IRS grabs the refund as a deposit against what the missing year might owe. It will not send you the money and then chase you for the old year separately. It holds first and asks questions second.
Note what the CP63 is not. It is neither an audit nor a judgment about the return you just filed. If your refund were held because the IRS was reviewing this year's numbers, you would have a CP05 notice instead, and if they wanted documents to support that review, a CP05A notice. The CP63's problem lives entirely in the past years it lists. (For the bigger picture on how the IRS decides who gets which letter, see why you got a letter from the IRS.)
You may also see a CP88 notice at some point. It comes from the same delinquent-return refund-hold program and carries the same instruction: file the missing years.
Do you have to contact the IRS, or is filing the missing return enough?
Clarity Tax Relief reads the CP63 instruction literally. The notice gives you one instruction with three ways to satisfy it. In the IRS's words: "File your tax return immediately or explain to us: why you're filing late, why you don't have to file, or that you've already filed." The IRS will "continue to hold your refund until we hear from you," and it releases the refund once it has "received all past due returns, or an explanation showing you did not have to file for those years." That is the whole test. Nothing about the current-year return matters here.
Many people read the notice and assume they have to go to a local IRS office in person. You do not. The CP63 tells you to call the toll-free number printed on it with your paperwork ready, or write to the address on it. A Taxpayer Assistance Center (the IRS's local office) is an option when you want to hand over a return or proof of filing face to face. It requires an appointment, booked at 844-545-5640, and the staff there verify identity and take documents. They do not prepare the missing return for you. For most CP63 cases the local office adds a trip without changing the outcome; mailing the return to the notice address with proof of mailing gets the same result.
One exception the notice itself names: if you filed the missing return within the last eight weeks, "you don't have to do anything." The return is probably still in the processing pipeline, and the hold should clear on its own once it posts.
| Your situation | What to send | Where it goes and what happens next |
|---|---|---|
| The return really is missing | The completed prior-year return (that year's Form 1040 and schedules), signed, with any payment you can make | Mail to the address on the notice with proof of mailing. The IRS says a past-due return takes about 6 weeks to process; the hold releases after it posts |
| You already filed it | If filed within the last 8 weeks, nothing. Otherwise a signed copy of the return plus proof of the original filing (certified-mail receipt, e-file acceptance) | Call the toll-free number on the notice first; the agent can often see a return that is in processing. Mail the copy only if asked |
| You were not required to file that year | A written explanation, with the income figures for that year, showing you were below the filing threshold or the 1099 overstates what was taxable | Call the number on the notice or write to the address on it. The hold releases when the IRS accepts the explanation; if it does not, it will still want a return |
“The penalty is 5% of the tax due (less any tax paid on time and available credits) for each month or partial month the return is late. The penalty accrues up to a maximum of 25%.”
, Failure to file penalty (IRS.gov)
What does a CP63 refund hold do to your money?
A CP63 freezes 100% of your refund, the whole thing, with nothing sized to the estimated old debt. For a married couple filing jointly, that means the entire joint refund is held even if only one spouse has the unfiled year. The IRS treats the joint refund as one pot.
Three things about how the hold behaves:
- It doesn't expire. There is no point where the IRS gives up and releases the money. The hold ends when the listed returns post or the IRS accepts that no filing was required.
- It repeats. File next year with the old gap still open, and next year's refund gets held too. One unfiled year can quietly confiscate several refunds in a row.
- It's a warning shot. The refund hold is the gentlest tool in the IRS's unfiled-return toolkit. What follows if you stay silent is considerably worse, and it is already queued up.
What happens if you ignore a CP63?
Ignoring a CP63 ends with the IRS filing the missing return for you, with no deductions, no credits and the least favorable filing status, and then applying your held refund to that inflated bill. The sequence is automated, and it runs in stages:
- CP63, refund held. You are here. Your money is frozen, but nothing has been assessed against you yet. This is the cheapest moment in the whole sequence.
- Delinquent-return notices. The IRS starts demanding the missing returns directly: a CP59 notice asking you to file, followed by reminder notices for the same years.
- Final filing demand. A CP518 notice tells you this is the last request before the IRS acts on its own.
- Substitute for Return (SFR). The IRS prepares the return itself from the W-2s and 1099s on file (gross income only, no business expenses, no dependents, married-filing-separately or single status) and proposes the tax via CP2566 or a CP3219N notice of deficiency. The CP3219N gives you 90 days to file your own return or petition the Tax Court. Here is what it means when the IRS files a substitute return for you.
- Assessment and collection. The SFR balance becomes legally owed. Your held refund is applied to it, and whatever remains enters the collection notice stream: a CP14 balance-due bill first, then intent-to-levy notices, with liens and levies at the end of that road.
| Stage / notice | What it says | What changes for you |
|---|---|---|
| CP63 | Refund held; file your missing return(s) | Refund frozen; no tax assessed yet; you still control the numbers |
| CP59 / reminders | You have unfiled returns; file now | The unfiled years become their own active case |
| CP518 | Final notice; file or the IRS acts | Last chance to file on your own terms |
| SFR: CP2566 / CP3219N | The IRS computed your tax for you | Tax proposed with zero deductions or credits, usually the worst-case number |
| Assessment & collection | Balance due; pay or face enforcement | Held refund applied to the SFR bill; the rest goes to collections |
The 2026 wrinkle: the IRS workforce was cut roughly 27% in 2025, so reaching a human about your hold is harder than ever (our 188-call hold-time study measured how long that wait really runs). The systems that flag non-filers, hold refunds, and build SFRs are automated, though, and they never stopped. Silence buys you no slack. It moves you down the list above.
Holding a CP63 with years you're afraid to open?
Send us a photo of the notice. An experienced tax professional will pull your IRS records, tell you exactly which years to file and what they'll likely show, before penalties and a substitute return make the numbers worse. Free and confidential.
What happens to the held refund after you file?
Clarity Tax Relief estimates the old year's result before filing, so the outcome is no surprise. Once the missing return posts, the held refund goes one of three ways: released in full, partially applied, or fully absorbed by the old balance. Which one you get depends entirely on what the unfiled year shows:
| What the missing year shows | What happens to the held refund | Your move |
|---|---|---|
| A refund, filed within 3 years of its due date | Held refund released, and the old year's refund is paid too | File fast; you're leaving two refunds on the table |
| A refund, but the 3-year window has closed | Held refund released; the old refund is forfeited | File anyway to clear the hold and stop future holds |
| A balance smaller than the held refund | Refund applied to the balance; the difference is sent to you | File and let the refund settle it, often no cash out of pocket |
| A balance larger than the held refund | Entire refund applied; the remainder becomes a collection balance | File, then set up a payment arrangement for the rest |
| No filing requirement that year | Hold released after the IRS accepts your explanation | Call the number on the notice and document why no return was due |
That first row deserves emphasis. Many CP63 recipients had withholding in the unfiled year and are owed money on it. The refund on an unfiled year dies 3 years after that return's due date, though. Here is how the 3-year refund deadline works. If your missing year is close to that line, filing it is urgent even though the CP63 itself prints no deadline.
What if the missing year leaves a balance you can't pay?
Filing the missing return is still the right move even when it creates a bill, because filing stops the 5%-per-month failure-to-file penalty and replaces the IRS's worst-case SFR math with your real numbers. Once the balance is fixed, your options scale with its size:
“File the missing year even if it shows a bill. Filing stops the 5% monthly failure-to-file penalty and replaces whatever return the IRS would build for you,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
| Balance after the refund is applied | Realistic options | What it takes |
|---|---|---|
| Under $10,000 | Pay within 180 days ($0 setup) or a guaranteed installment agreement, individuals only, with an income-tax balance of $10,000 or less excluding penalties and interest, all returns filed, timely filing and payment for the past 5 years with no installment agreement in that period, and full payment within 3 years | Set up online in minutes; no financial disclosure |
| $10,000 to $25,000 | Streamlined installment agreement | Up to 72 months; no detailed financials required |
| $25,000 to $50,000 | Streamlined agreement, typically with direct debit; online setup up to 72 months | Direct debit usually expected at the upper end |
| Over $50,000 | Non-streamlined agreement, hardship (CNC) status, or an Offer in Compromise if the math supports it | Full financial disclosure (Form 433 series); professional review pays for itself here |
Interest (7% per year for the quarter beginning October 1, 2026, compounded daily) continues on any plan, and the late-payment penalty drops from 0.5% to 0.25% per month while an approved installment agreement is in place. A plan buys protection from enforcement. It is no discount. Penalty relief is a separate conversation, and since first-time abatement requires a clean prior-three-year history, a taxpayer with multiple unfiled years usually needs a reasonable-cause argument instead.
A worked example: the numbers on a real-shaped CP63 case
Say you are married filing jointly. In 2023 your spouse went independent and grossed $68,500 on 1099s. That return never got filed. Quarterly taxes felt impossible, then the deadline slid by. This April you filed jointly as usual, expected a $4,800 refund, and got a CP63 instead. Here is roughly how the math plays out (hypothetical figures, real mechanics):
- The 2023 return: after mileage and expenses, net self-employment profit comes to about $54,000. Self-employment tax alone runs about $54,000 × 92.35% × 15.3% ≈ $7,630. Add income tax on that profit, offset partly by your W-2 withholding, and suppose the return shows $10,000 unpaid.
- Failure-to-file penalty: 5% per month capped at 25%, and the cap hit long ago: $2,500. (For a return more than 60 days late the IRS also sets a floor: for returns due after December 31, 2025 the minimum is $525 or 100% of the unpaid tax, whichever is less. It does not change this example, where the percentage figure is far larger.)
- Failure-to-pay penalty: 0.5% per month, roughly 24 months so far: about $1,200.
- Interest on all of it: call it roughly $1,700 by October 2026 at the 7% rate. Total: about $15,400.
- The held refund: your $4,800 is applied automatically, leaving about $10,600 that fits a streamlined installment agreement at roughly $148 a month over 72 months before ongoing interest.
Now compare the do-nothing version. An SFR on $68,500 of gross 1099 income, filed married-filing-separately with zero expenses, would propose tax on $14,500 more income than existed, easily thousands more, plus the same penalties on the bigger number. Filing your own return is the single biggest dollar lever in the whole case. You can rough out your own penalty and interest exposure with our Penalty & Interest Calculator.
How do you find which years the IRS says are missing?
The years are printed on the CP63 itself. Start there. If you suspect there are more gaps than the notice lists, or you want to see what the IRS has on file before you build the return, two IRS records settle it in minutes:
- Your Individual Online Account at IRS.gov shows every year with a filed return and lets you view, print or download transcripts immediately. A year with no return transcript and a "no return filed" account transcript is a missing year.
- The wage and income transcript for each missing year lists every W-2, 1099, 1098 and 1099-K sent to the IRS under your Social Security number. It is available online for the current year and nine prior years, by mail through Form 4506-T (check box 8) for the same range, or by the automated line at 800-908-9946. Mailed transcripts arrive in 5 to 10 calendar days.
That transcript is the same data the IRS will check your return against, so building the missing return from it means the numbers reconcile the first time. Our guide to IRS transcript codes decodes what the account transcript shows for a year that was never filed.
How do you file the missing return?
Clarity Tax Relief builds each missing year the way it would have been filed at the time. File the year's actual return, on that year's forms, with that year's rules. The IRS keeps prior-year forms and instructions on IRS.gov, and the standard deduction, brackets and credit amounts all change year to year, so the current-year form will not work. Claim every deduction and credit you are entitled to. The whole point of filing yourself is to replace the IRS's worst-case math with real numbers.
Getting it to the IRS: the past-due return goes to the address on the notice, by mail, with proof of mailing. IRS Free File only handles the current tax year. Commercial software and paid preparers can transmit the most recent tax years electronically, and older years go on paper no matter who prepares them. If an SFR has already been assessed for that year, file your real return anyway; the IRS says it "will generally adjust your account to reflect the correct figures."
If a missing year is going to owe money you cannot pay, the IRS notes you can request a payment plan online once the return is filed. If the missing years are self-employment years, or you have several of them, our unfiled tax return service rebuilds the returns from transcripts and bank records and files them in the order that keeps penalties and payment terms workable. Call (888) 825-7779 to start with a free case review.
How long does the refund hold last after you file?
There is no fixed release date on a CP63, but the IRS publishes two numbers that bound it. A past-due return takes "approximately 6 weeks" to process when it is complete and accurate, and the IRS says to take no further action on a CP63 if you filed within the last 8 weeks. Put together, a mailed return that arrives clean usually posts in 6 to 8 weeks, and the refund release follows the posting. A return with math errors, a missing signature, or a year that owes more than the held refund takes longer, because the IRS has to apply the refund and bill the difference before anything moves.
| When | What happens | How you can tell |
|---|---|---|
| Day 0 | You mail the return to the address on the notice | Keep the certified-mail or tracking receipt; it is your proof of the filing date |
| Weeks 1 to 3 | The envelope is opened and the return enters processing | Nothing visible yet; the IRS asks you not to call or refile during the first 8 weeks |
| About week 6 | An accurate past-due return finishes processing (the IRS's own estimate) | The account transcript for that year shows the return posted and any tax assessed |
| Weeks 6 to 8 | The held refund is released, or applied to the old balance with the remainder paid out | Where's My Refund updates; a CP14 arrives if the old year still owes after the offset |
| After week 8 | No movement means something is wrong: an unsigned return, a math error, or an identity mismatch | Call the toll-free number on the notice with your mailing receipt and a copy of the return |
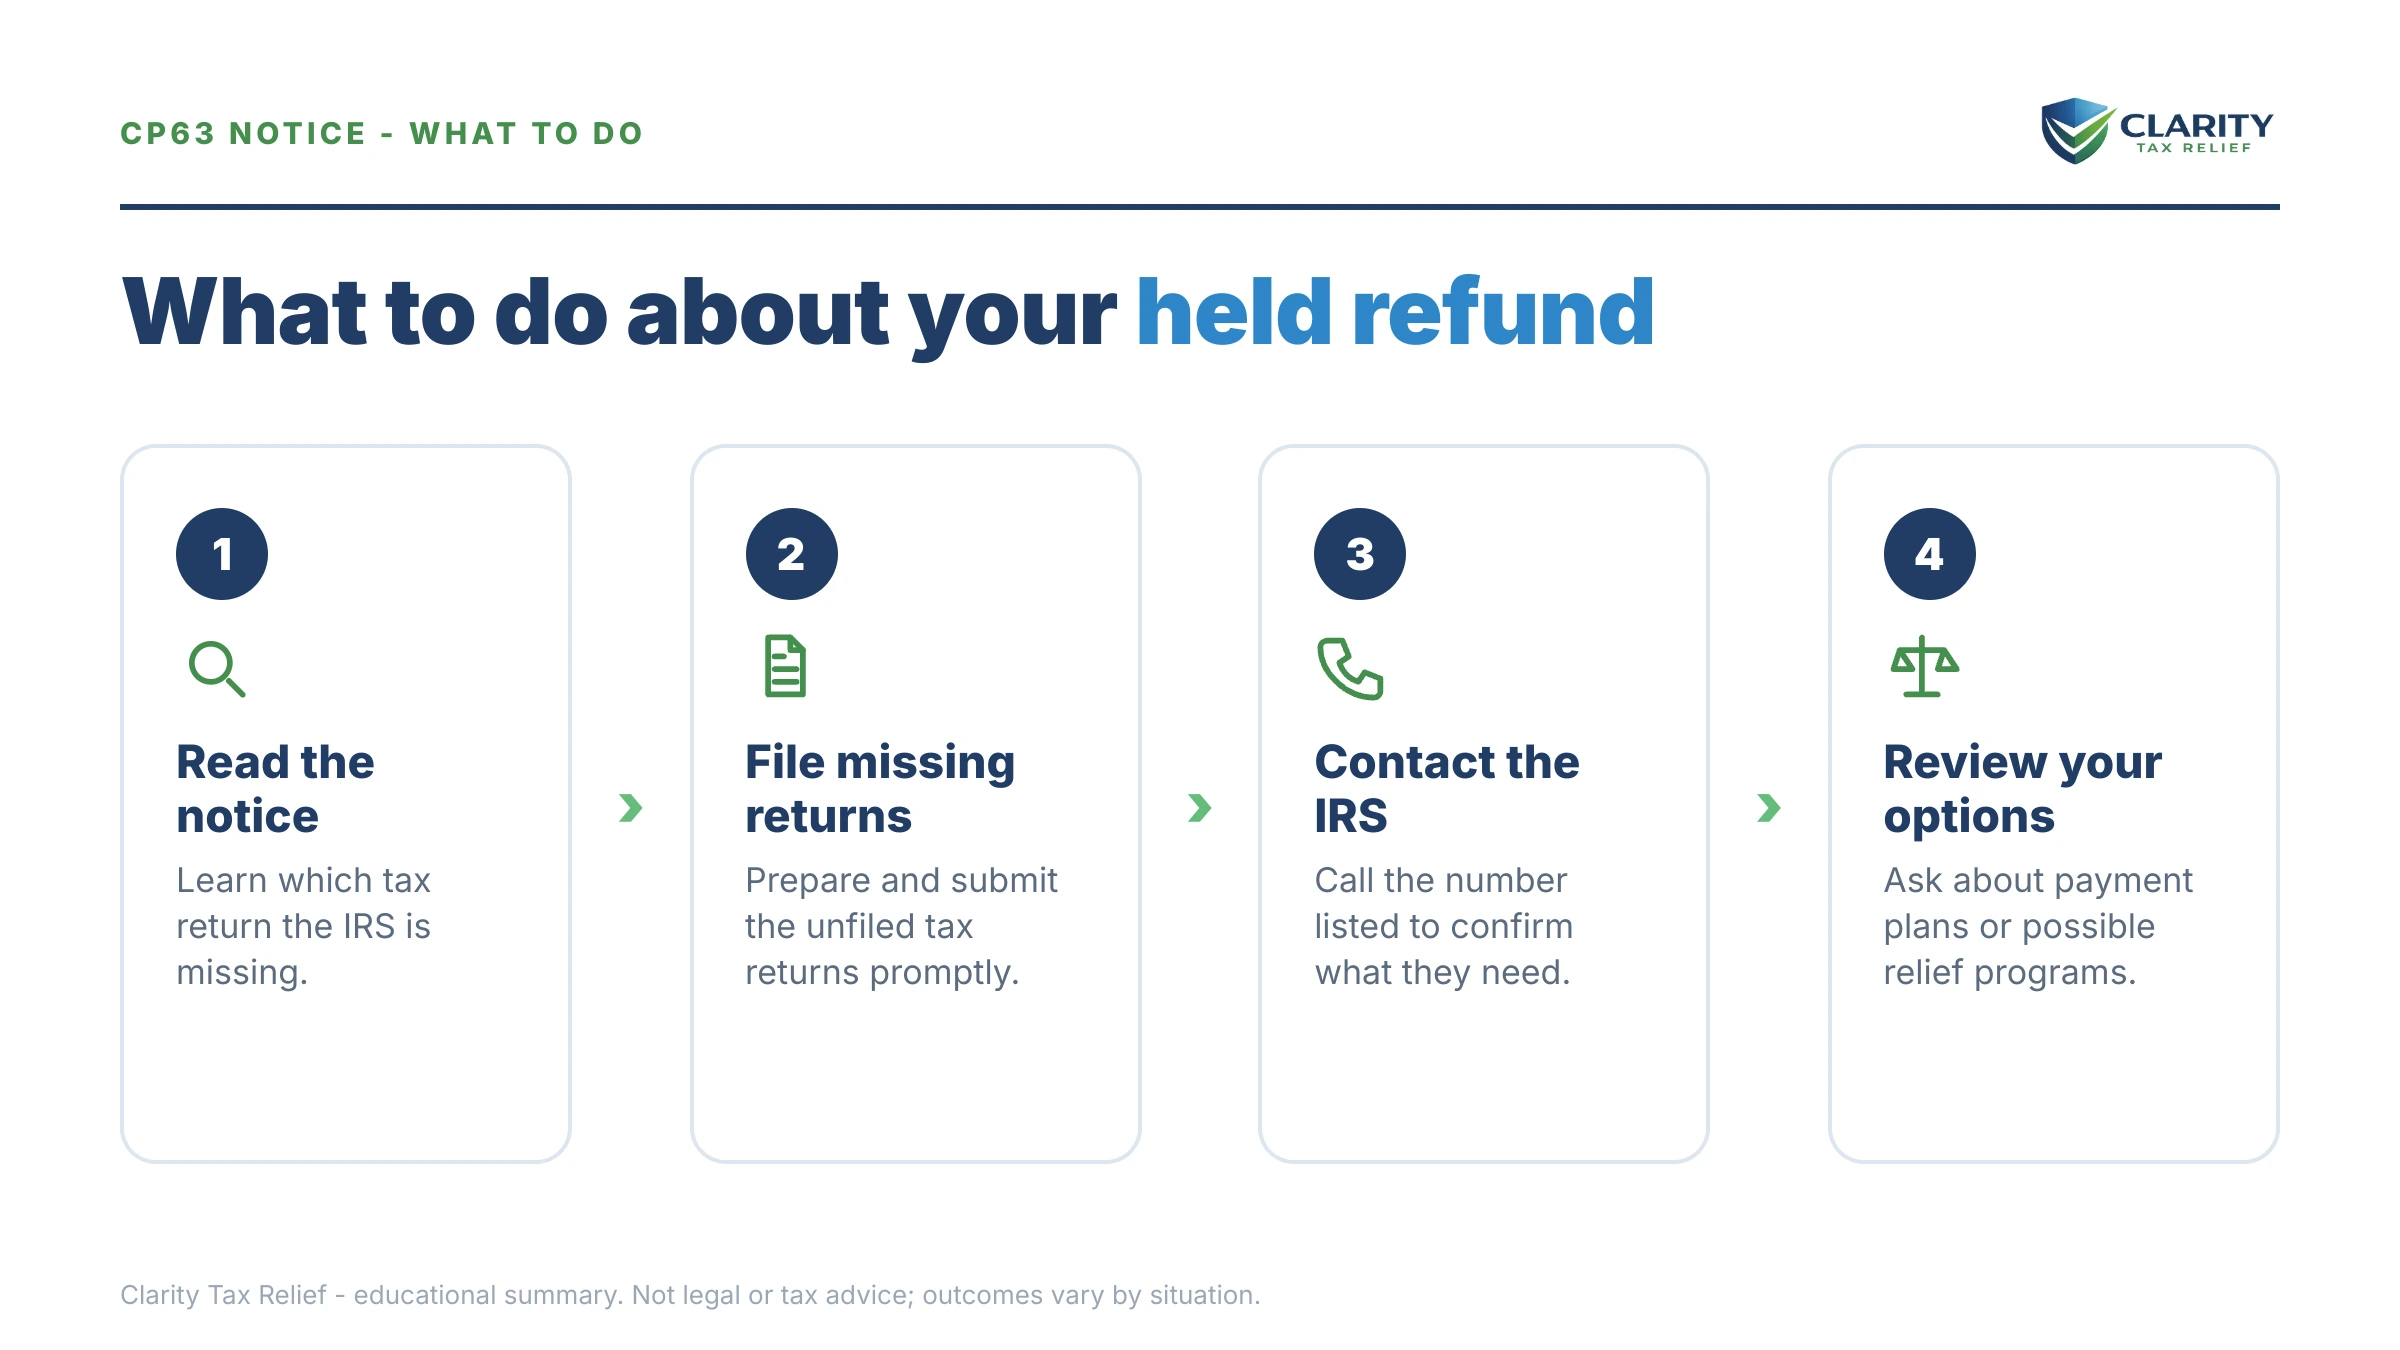
How to respond to a CP63, step by step
- Confirm which years the IRS wants. The tax years are printed on the notice. Write them down, because every step that follows is about those years, and the return you just filed is beside the point.
- Pull your IRS wage and income transcripts. They list every W-2 and 1099 the IRS has on file for the missing years, so you are building the return from the same data the IRS will check it against.
- Prepare and file the missing returns. Use that year's forms and rules, claim every deduction you are entitled to, and mail them to the address on the notice with proof of mailing.
- Respond if you already filed or weren't required to. Call the number on the notice. Send a signed copy with proof if the return was filed, or explain in writing why no filing requirement existed that year.
- Settle any balance and track the release. If the old year owes more than the held refund covers, set up a payment plan for the remainder, then watch your transcripts until the return posts and the hold lifts.
If your records for the missing years are gone, a common reason people froze in the first place, transcripts plus bank statements can rebuild most returns. Here is the full playbook for filing back taxes with no records, and a step-by-step on ordering wage and income transcripts.
Red flags: what to check before you mail the return
- The missing year is close to its 3-year refund line. If withholding ran that year, the refund dies 3 years after the return's due date. File that year first.
- A CP59 or CP518 has already arrived. The unfiled years are now their own case, and a substitute return is the next stage.
- A CP2566 or CP3219N is in the stack. The IRS has already computed your tax with no deductions. The CP3219N gives 90 days to file your own return or petition the Tax Court.
- The notice lists years you thought were filed. If you filed within the last 8 weeks, wait. Otherwise call the toll-free number on the notice with proof of the original filing.
- You are about to use this year's form for a past year. Brackets, the standard deduction and credit amounts change every year. Use that year's forms.
- The return is going out unsigned, or without proof of mailing. Both are common reasons nothing moves after week 8.
- The missing years were self-employment years. Every reconstructed expense shrinks the balance your refund gets applied to, so build the return from records, never from the 1099 totals alone.
Can you handle a CP63 yourself?
Plenty of CP63 cases are safe DIY. If the notice lists one missing year, you have (or can get) the W-2s and 1099s for it, and the income was straightforward wages, you can prepare the return, mail it with proof, and wait out the release without paying anyone. That is especially true if the missing year likely shows a refund, where you are only claiming money.
Experienced help changes the outcome when the case has layers:
- Multiple unfiled years, especially if you are unsure how many; the IRS generally wants the last six. The order and content of those filings affect penalties and payment options. See how many years of back taxes you have to file.
- Self-employment or business income in the missing years. Every legitimate expense you reconstruct directly shrinks the balance your refund gets applied to.
- An SFR already in motion. A CP2566 or CP3219N on top of your CP63 means deadlines with legal consequences. The response strategy changes.
- A big projected balance. When the old years will owe more than the held refund, the filing and the resolution plan should be designed together rather than one after the other.
Terms on your CP63, decoded
- Refund hold: the IRS keeping your refund in suspense (not applied, not paid out) until a compliance issue is resolved.
- Delinquent return: a required tax return that was never filed; the years listed on your CP63 are your delinquent returns.
- Substitute for Return (SFR): a return the IRS builds for you from third-party documents, with no deductions or credits, almost always a worse result than filing yourself.
- RSED (Refund Statute Expiration Date): the deadline, generally 3 years from a return's due date, after which a refund on that year can no longer be claimed.
- Assessment: the formal recording of a tax debt on your IRS account; before assessment nothing is legally owed, after it collection can begin.
- Wage and income transcript: the IRS's year-by-year list of every W-2 and 1099 filed under your Social Security number, the raw material for rebuilding old returns.
The bottom line on a CP63
A CP63 is a refund hold with a named cure. The IRS is keeping this year's money until the past years it lists are filed or explained. File those years on their own forms from your wage and income transcripts, mail them to the address on the notice with proof, and the hold has an end date of roughly 6 to 8 weeks after the return posts. Wait instead, and the same years come back as a substitute return with no deductions. Filing first is cheaper at every stage.
CP63 questions, answered
What is an IRS CP63 notice?
A CP63 notice means the IRS is holding your entire tax refund because its records show you haven't filed one or more prior-year returns, and it believes those returns may show tax due. The refund stays frozen until you file the missing years or prove you weren't required to file.
Do I have to go to a local IRS office to respond to a CP63?
No. The notice tells you to file the missing return, or call the toll-free number on the notice with your paperwork ready, or write to the address on it. A local Taxpayer Assistance Center can take documents in person, but only by appointment (844-545-5640), and the staff there do not prepare the missing return for you. Mailing the return to the notice address with proof of mailing produces the same result without the trip.
How do I find out which years the IRS says are missing?
The years are printed on the CP63. To check for others, sign in to your Individual Online Account at IRS.gov, where any year without a return transcript is a missing year, and pull the wage and income transcript for each one. It lists every W-2 and 1099 the IRS holds for that year and is available online for the current year and nine prior years, or by mail with Form 4506-T.
Can I e-file the missing prior-year return?
Sometimes. IRS Free File only handles the current tax year. Commercial software and paid preparers can transmit the most recent tax years electronically, but older years must be mailed on paper. For a CP63, send the return to the address printed on the notice and keep proof of mailing, whichever way you file.
How long will the IRS hold my refund after I file the missing return?
The IRS says an accurate past-due return takes about 6 weeks to process, and it asks you to take no further action on a CP63 if you filed within the last 8 weeks. So expect the release 6 to 8 weeks after the return arrives, once it posts to your account transcript. If the old year owes tax, the IRS applies the held refund to that balance first and sends you whatever is left.
What if I already filed the return the CP63 says is missing?
If you filed within the last eight weeks, the IRS says to do nothing; the return is still processing. If you filed longer ago, call the number printed on the notice and check your account transcript for that year. Be ready to send a signed copy of the return with proof of the original filing, such as a certified-mail receipt or e-file acceptance. Name or SSN mismatches can also make a filed return look missing in IRS records.
What if I wasn't required to file the year the IRS wants?
Call the number on the notice or write to the address on it and explain why, for example that your income that year was below the filing threshold. Be ready to address what the IRS sees: its records show gross figures from W-2s and 1099s, so a 1099 that overstates your true taxable picture (gross platform sales, for instance) may still need a return or a written explanation before the hold releases.
What happens if I ignore a CP63?
The refund stays frozen, and next year's refund gets held too. The IRS then sends CP59 and CP518 demands for the missing returns, and if those go unanswered it files a substitute for return from your W-2s and 1099s with no deductions or credits, assesses that tax, and applies your held refund to it. Whatever remains becomes a collection balance with its own bills and levy notices.
Your next 24 hours
- Find the tax years on the notice. They're printed on the CP63 along with the amount being held. Those years define everything you need to do.
- Gather what you have for those years: any W-2s or 1099s, your last filed return, and an IRS transcript request for whatever is missing (see Get Transcript at IRS.gov).
- Get a free case review. Your refund stays frozen, and if the missing year owes, penalties and interest keep compounding, until those returns are filed right. Call (888) 825-7779 or use the 2-minute form, and we'll map the fastest release path before you mail anything.
Primary sources: the IRS's own explainer at Understanding your CP63 notice, its page on filing past due tax returns, and payment options for any leftover balance at IRS.gov/payments.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.