IRS Notices
How to Pay a CP14 Notice Online (2026)
The short answer: the fastest free way to pay a CP14 notice online is IRS Direct Pay at irs.gov/payments. No login is needed. Choose "Balance Due" as the reason and select the exact tax year printed on your notice. If you cannot pay in full, apply for a payment plan at irs.gov/payments/online-payment-agreement-application in the same sitting. Updated October 5, 2026; every IRS path, fee and rate below was checked against irs.gov on that date.
This guide covers where on IRS.gov to pay a CP14, what each payment method costs, what happens if you don't pay, and how to set up a plan online when the full amount is out of reach.
If you typed "irs.gov/cp14" or "pay IRS CP14 online" into Google, you are probably holding the notice right now: a bill from the IRS with a pay-by date, a tear-off stub, and a return envelope that assumes you will mail a check. You would rather pay from the kitchen table and walk away with a confirmation number, and that instinct is right. This page gives you the exact IRS.gov addresses, the fees each route charges, and what to do if the balance is more than you can pay at once.
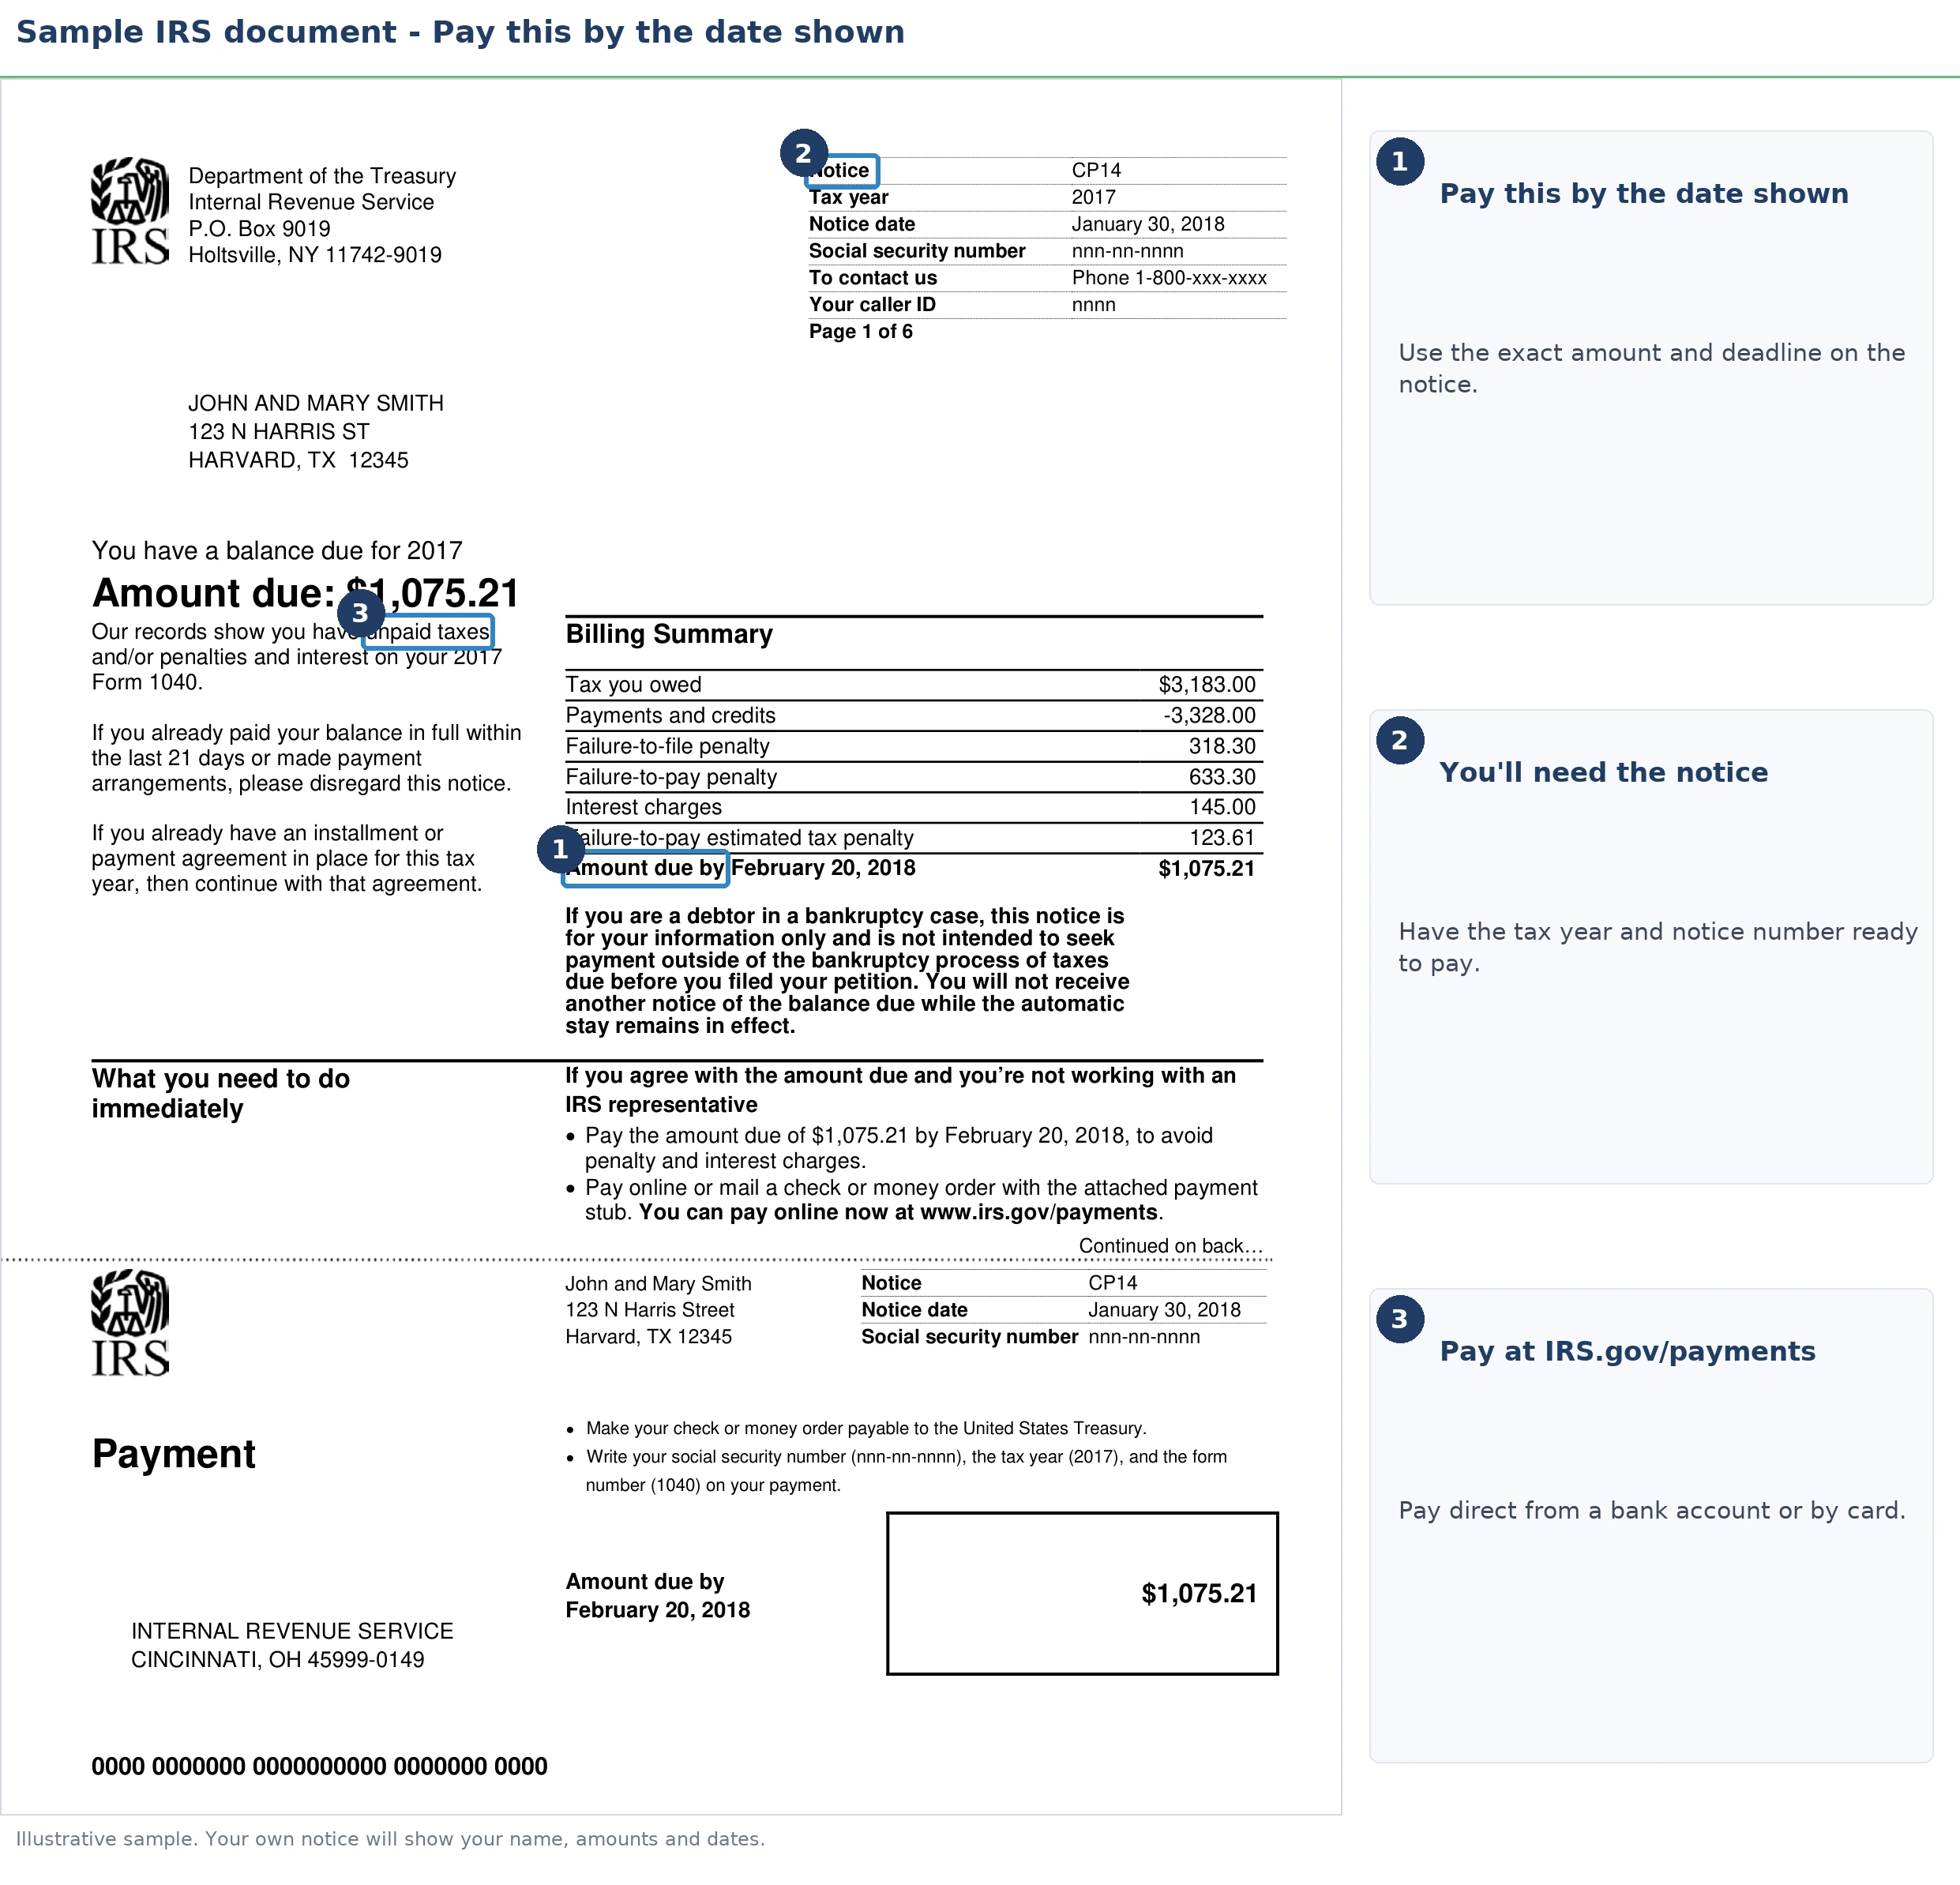
Two numbers on your CP14 control everything you are about to do online: the tax year and the amount due. The image below shows what the notice looks like and where those figures sit, so keep it handy before you type anything into IRS.gov.
⏱ Your deadline: the "pay by" date printed on your CP14. Pay online by that date and the notice amount is exact and the collection sequence stops. Pay after it and the printed figure is already too low, because the IRS says interest accrues on the unpaid amount after that date.
Why did the IRS bill you, and why does paying online beat mailing the stub?
A CP14 is the IRS's first bill for a balance due. The IRS's own explainer, Understanding your CP14 notice, says it plainly: you owe money on unpaid taxes, pay the amount by the due date on the notice, and if you cannot, apply online for a payment plan. An online payment is credited the day you submit it. A mailed check can take weeks to open, post, and match to your account. That gap matters, because the notice sequence behind a CP14 is automated: if your check sits unopened while the clock runs out, the next notice mails anyway.
In 2026 that risk is bigger. The IRS cut roughly 27% of its workforce in 2025, so paper correspondence and mailed payments move through fewer hands, while the automated notice stream never slowed down. Paying electronically, with a timestamped confirmation number, takes the mail out of the picture.
This guide assumes your CP14 is accurate and focuses on the payment itself. If you need the full decode of the notice (why it was issued, what each line means), that is covered in our CP14 notice guide, and IRS letters in general are explained in why did I get a letter from the IRS. If the balance looks wrong, read our CP14 wrong amount guide before paying anything. If you already paid, see CP14 notice but I already paid. A real share of these notices crossed in the mail with a payment.
"irs.gov cp14": which official IRS page takes your money?
There is no page at irs.gov/cp14. People type it because the notice says to visit IRS.gov, and Google fills in the rest. The pages you need are below, checked on irs.gov on October 5, 2026. Type them in yourself rather than clicking an ad.
| What you want to do | Exact IRS.gov address | What you get there |
|---|---|---|
| Understand the notice | irs.gov/individuals/understanding-your-cp14-notice | The IRS explanation of a CP14, what to do, and links to every payment tool. It is not a payment page. |
| See every payment method | irs.gov/payments | The hub: bank account (Direct Pay), Online Account, card or digital wallet, EFTPS, same-day wire, check, cash, payment plan. |
| Pay from a bank account, free | irs.gov/payments/direct-pay-with-bank-account | Direct Pay. No login. Confirmation number on every payment. Schedule up to 365 days ahead. |
| Check the live balance first | irs.gov/payments/online-account-for-individuals | Your balance with interest through today, payment history, and a pay button. Needs an ID.me login. |
| Pay by card or digital wallet | irs.gov/payments/pay-your-taxes-by-debit-or-credit-card | The two IRS-listed processors (Pay1040 and ACI Payments) and their fees. |
| Set up a payment plan | irs.gov/payments/online-payment-agreement-application | The Online Payment Agreement: short-term (180 days or less) or long-term monthly plan, with the thresholds and fees below. |
Is paying online always the first move?
No. If the balance is affordable, pay it and stop the interest. If paying it in full would create real financial hardship, do not empty an account to clear the notice. An arrangement made before the due date protects you better than a payment that leaves you unable to meet the next one.
What happens if you don't pay your CP14?
How the notice sequence escalates after CP14
An unpaid CP14 starts an automated escalation that ends in levy power. No human decides to send the next letter. The sequence runs in a fixed order, and each stage adds more interest and more enforcement authority:
- CP14: the first bill. You are here. No enforcement power yet; this is the cheapest moment in the entire sequence to resolve the balance.
- CP501 and CP503: reminder notices, typically arriving several weeks apart. Still just bills, but the failure-to-pay penalty and interest have been accruing the whole time.
- CP504 notice: Notice of Intent to Levy under IRC §6331(d). The IRS can now seize your state tax refund, and a federal tax lien becomes a live possibility. Per irs.gov, if you do not pay within 10 days of a notice of intent to levy, the failure-to-pay penalty rises to 1% per month.
- LT11 / Letter 1058: the Final Notice of Intent to Levy. It starts a 30-day clock and your Collection Due Process appeal rights; after that window, wage and bank levies are on the table.
- Levy stage: for retirees, this is where it gets personal. The Federal Payment Levy Program can take up to 15% of every Social Security check, continuously, until the debt is resolved. Our guide on whether the IRS can garnish Social Security covers how that works.
| Stage | What it can do | Your window |
|---|---|---|
| CP14 | Bills you; no enforcement yet | The due date printed on the notice |
| CP501 / CP503 | Reminders while penalties and interest accrue | Typically several weeks between notices |
| CP504 | State tax refund can be seized; lien risk rises | 30 days stated on the notice |
| LT11 / Letter 1058 | Final notice; wage and bank levies become possible | 30 days to pay, arrange, or appeal (Form 12153) |
| Levy stage | Bank levies, wage levies, up to 15% of Social Security | Continues until the balance is resolved |
Holding a CP14 and not sure how, or whether, to pay it?
Get it reviewed free before the pay-by date on your notice passes. An experienced tax professional will confirm the balance is right, tell you which online option fits your finances, and flag any penalty relief you are leaving on the table. No pressure, no obligation.
IRS CP14 payment online: what does every method cost?
The IRS accepts CP14 payments through four online channels plus a mailed check, and the bank-account routes are free. The right one depends on whether you are paying in full, whether you have a checking account, and how fast you need proof of payment. Fees below are the ones published at irs.gov/payments/pay-your-taxes-by-debit-or-credit-card as of October 5, 2026; no part of a card fee goes to the IRS.
| Method | Cost | What you need | Best for |
|---|---|---|---|
| IRS Direct Pay | Free | Bank routing/account numbers plus a prior tax return to verify identity (up to 5 to 6 years back) | Most people paying in full. No login, up to five payments per 24 hours, schedule up to 365 days ahead. |
| IRS Online Account | Free (bank payment) | ID.me login | Verifying the balance first, then paying the live payoff figure |
| Debit card | Flat fee: $2.15 at Pay1040, $2.10 at ACI Payments | A debit card; both processors are linked from irs.gov | People without a checking account who want same-day proof of payment |
| Credit card or digital wallet (PayPal, Venmo, Click-to-Pay) | 1.75% at Pay1040 or 1.85% at ACI Payments ($2.50 minimum); commercial cards 2.89% to 2.95% | A card or wallet account | Rarely the right call: on a $10,000 balance the fee is $175 to $185, and card interest usually exceeds the IRS rate |
| EFTPS | Free | Enrollment at eftps.gov; the IRS says new enrollments can take up to five business days to process, then a PIN arrives by mail | Recurring or business payments, schedulable 365 days ahead. Too slow to start for a tight CP14 deadline. |
| Online Payment Agreement | $0 for a short-term plan (180 days or less); $29 for a long-term plan with direct debit, $69 without; low-income fee waived or $43 | Under $100,000 for short-term; $50,000 or less for long-term; all required returns filed | Anyone who cannot pay the full balance by the notice date |
| Check or money order by mail | Free, plus postage | The payment stub from the notice; payable to United States Treasury | Only if you have no online option. Credited when processed, not when mailed, so it is the slowest route. |
IRS Direct Pay: the default choice
Direct Pay is free, requires no account, and credits your payment the day you submit it. You pick "Balance Due" as the reason, choose the tax year from your notice, and verify your identity using details from a past return: filing status, name, address, SSN, and date of birth. The IRS lets you pick any prior-year return going back 5 to 6 years, depending on the time of year, and if you have never filed or it has been more than 6 years you will need another method. One trap for anyone who has moved since filing: verification checks the address on the return for the year you select. If it rejects you, try an older year whose return still shows your previous address.
You can also schedule the payment up to 365 days ahead, which helps if your Social Security deposit lands just before the pay-by date and you want the money in the account first. You can change or cancel a scheduled payment up to 2 days before it runs, and the system is offline from 11:45 p.m. to midnight Eastern. Print or screenshot the confirmation number before you close the window; it is your receipt if a follow-up notice crosses in the mail.
IRS Online Account: verify first, then pay
Your Online Account shows the live balance including interest through today, while the CP14 figure is only exact through the printed due date. If you are paying late, even a week late, pay the account figure rather than the notice figure, or a small residual balance survives and generates another notice. Setting up the login takes an ID.me identity check; our IRS online account setup walkthrough covers the process and its common snags.
Card payments and digital wallets: legal, but you pay extra
The IRS itself never touches your card. Two listed processors handle these payments and charge for it. As of October 2026 irs.gov lists Pay1040 ($2.15 flat on debit, 1.75% on consumer credit, $2.50 minimum) and ACI Payments ($2.10 flat on debit, 1.85% on consumer credit, $2.50 minimum). Commercial cards run 2.89% to 2.95%. On a $23,800 balance the consumer credit fee is $417 to $440, and card interest usually exceeds the IRS rate of 7%. Use a card only if you have no bank account. For a fuller comparison of every channel, see the best way to pay the IRS.
EFTPS: skip it for a one-time CP14 payment
The Electronic Federal Tax Payment System is free and good for recurring payments, but the IRS says a new enrollment can take up to five business days to process, and the PIN then comes by mail. If your CP14 deadline is close, that lag makes EFTPS the wrong tool for this job.
irs.gov/cp14 payment plan: what if you cannot pay in full?
Applying for a payment plan online
The CP14 page on irs.gov points you to the Online Payment Agreement. Checked October 5, 2026, the thresholds there are: a short-term plan of 180 days or less if you owe less than $100,000 in combined tax, penalties and interest ($0 setup fee), and a long-term monthly plan if you owe $50,000 or less and have filed all required returns. The long-term setup fee is $29 online with direct debit or $69 without; low-income applicants get the direct-debit fee waived or pay $43 for the other, which may be reimbursed. Business accounts cannot apply online and must call. The application takes minutes, and the thresholds break down like this:
| You owe | Online option | What to know |
|---|---|---|
| Under $10,000 | Guaranteed Installment Agreement or short-term plan | The IRS generally must accept if your filing history is clean and you can pay within 3 years; $0 setup for the short-term option |
| $10,000 to $25,000 | Long-term plan, up to 72 months | No financial disclosure; set up online for $29 (direct debit) or $69 |
| $25,000 to $50,000 | Long-term plan with direct debit | Payments come automatically from your bank account; still within the $50,000 online limit |
| $50,000 to under $100,000 | Short-term plan online only (180 days or less) | Long-term plans need Form 9465 plus financial disclosure, or a call to the IRS |
| $100,000 or more | No online plan | Pay by Direct Pay in full, or work out a plan by phone or mail with a financial statement; the pay-by date on the notice still controls |
Interest and the failure-to-pay penalty keep accruing on every plan. A payment arrangement stops enforcement while the meter keeps running. If paying anything at all would leave you unable to cover rent, medication, and food, the IRS can temporarily delay collection until your situation improves (Currently Not Collectible status). Run your own numbers through our IRS payment plan calculator before you commit to a monthly amount online, and if the balance is large enough that a plan will not clear it, read how an offer in compromise is evaluated before anyone pitches you one.
A worked example: $23,800 on a fixed income
Say you are retired, living mainly on Social Security, and your CP14 shows $23,800, maybe from a retirement-account withdrawal that had no withholding. Here is the math on each online path:
- Pay in full via Direct Pay: free, done, and the notice sequence stops that day. If you have the savings, this is the cheapest outcome by far.
- 180-day short-term plan: $0 to set up. But the failure-to-pay penalty runs 0.5% per month, about $119 a month on $23,800, so six months costs roughly $714 in penalty alone, plus interest at 7% a year (the IRS rate for the quarter beginning October 1, 2026), compounded daily.
- 72-month installment agreement: $23,800 divided by 72 is about $331 a month before interest. Because $23,800 is under the $50,000 online limit, you can set this up at irs.gov for $29 with direct debit. A detail most people miss: for an individual who filed on time, the failure-to-pay penalty drops from 0.5% to 0.25% per month during an approved plan, roughly $59.50 a month instead of $119 at the start, declining as you pay down.
- If $331 a month is not survivable on your benefit checks, Currently Not Collectible or a lower partial-payment arrangement may fit better than forcing a plan you will default on. Have that conversation before you commit online.
Want to see how the penalty and interest math runs on your own numbers? You can estimate it with our IRS Penalty & Interest Calculator.
One more lever: if this is your first penalty after three clean years, first-time penalty abatement can remove the failure-to-pay penalty. Our first-time penalty abatement guide covers the request. Starting in summer 2026, the new Automatic Exemption from Penalty applies similar relief automatically, with no request needed, so do not assume the penalty on your notice is permanent.
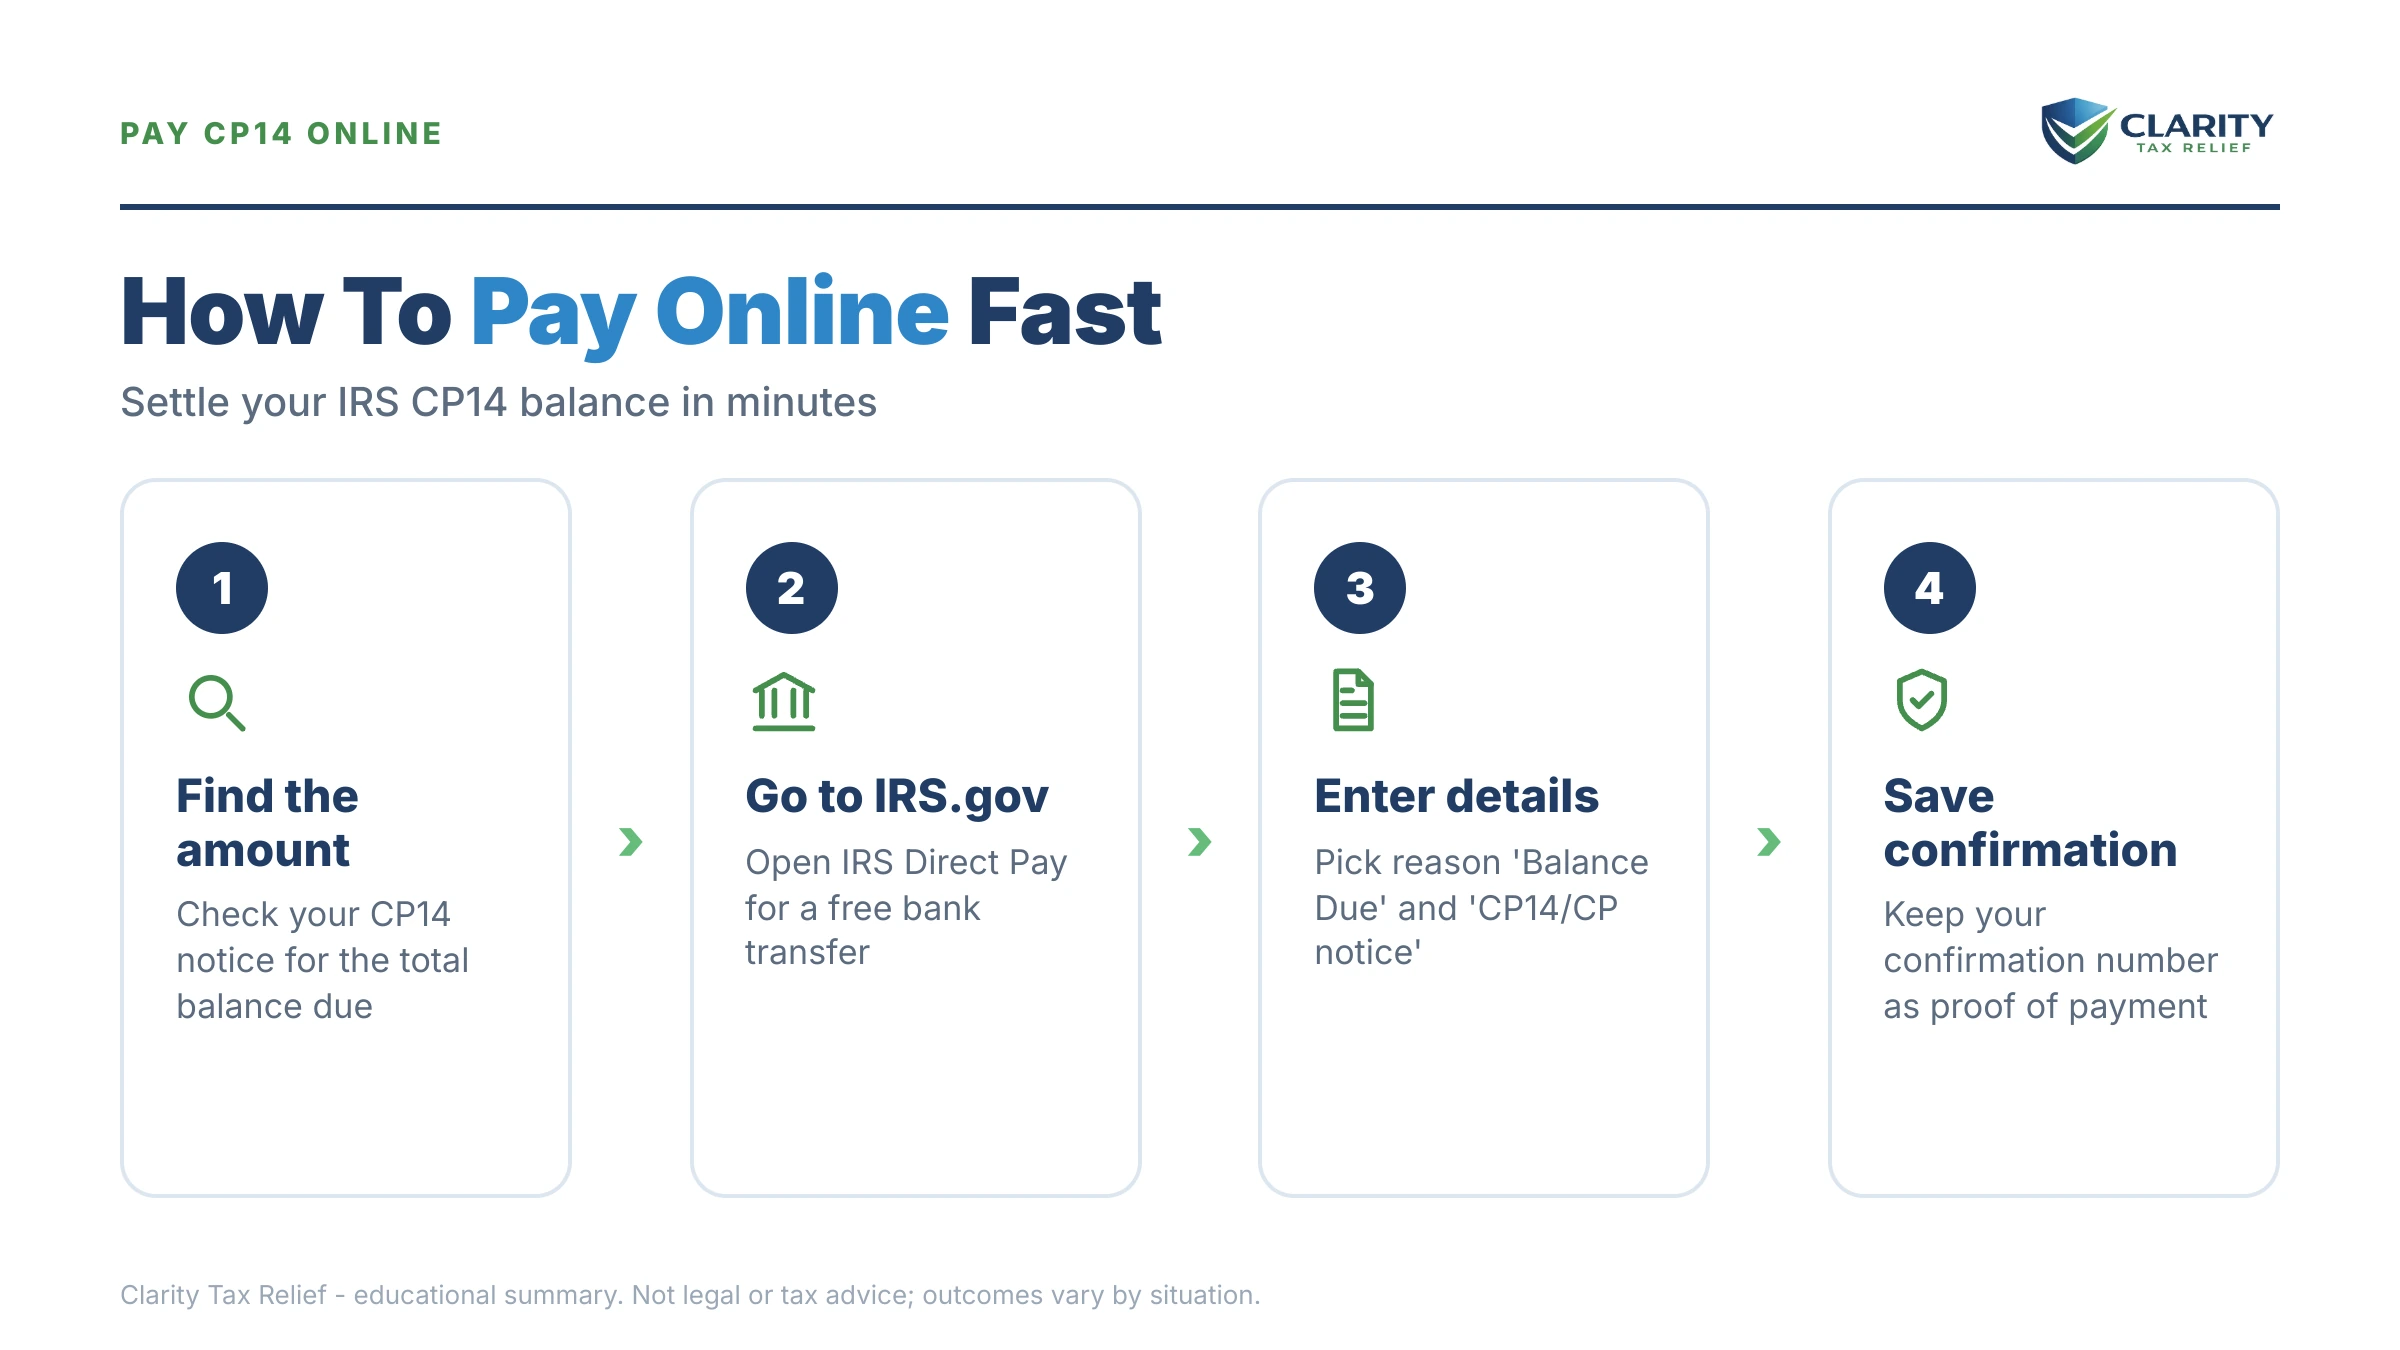
How to pay IRS CP14 online, step by step
| Step | What you need | Where to click | What you get |
|---|---|---|---|
| 1. Check the balance | ID.me login (or the notice alone if paying on time) | irs.gov/payments/online-account-for-individuals | The live payoff figure and confirmation the tax year matches your CP14 |
| 2. Open Direct Pay | Nothing yet | irs.gov/payments, then "Pay from your bank account" | The Direct Pay form |
| 3. Set the reason and year | The tax year printed on the CP14 | Reason: Balance Due; Apply payment to: Income Tax, Form 1040; Tax period: the notice year | The payment aimed at the right account |
| 4. Verify identity | A prior-year return (filing status, name, address, SSN, date of birth) | Pick the return year, enter the details as filed | Access to the payment screen |
| 5. Enter and submit | Bank routing and account numbers, amount, payment date | Review, then Submit | A confirmation number; save it |
| 6. Confirm it posted | The confirmation number | Online Account, Payment Activity, about a week later | The balance reduced on the correct year |
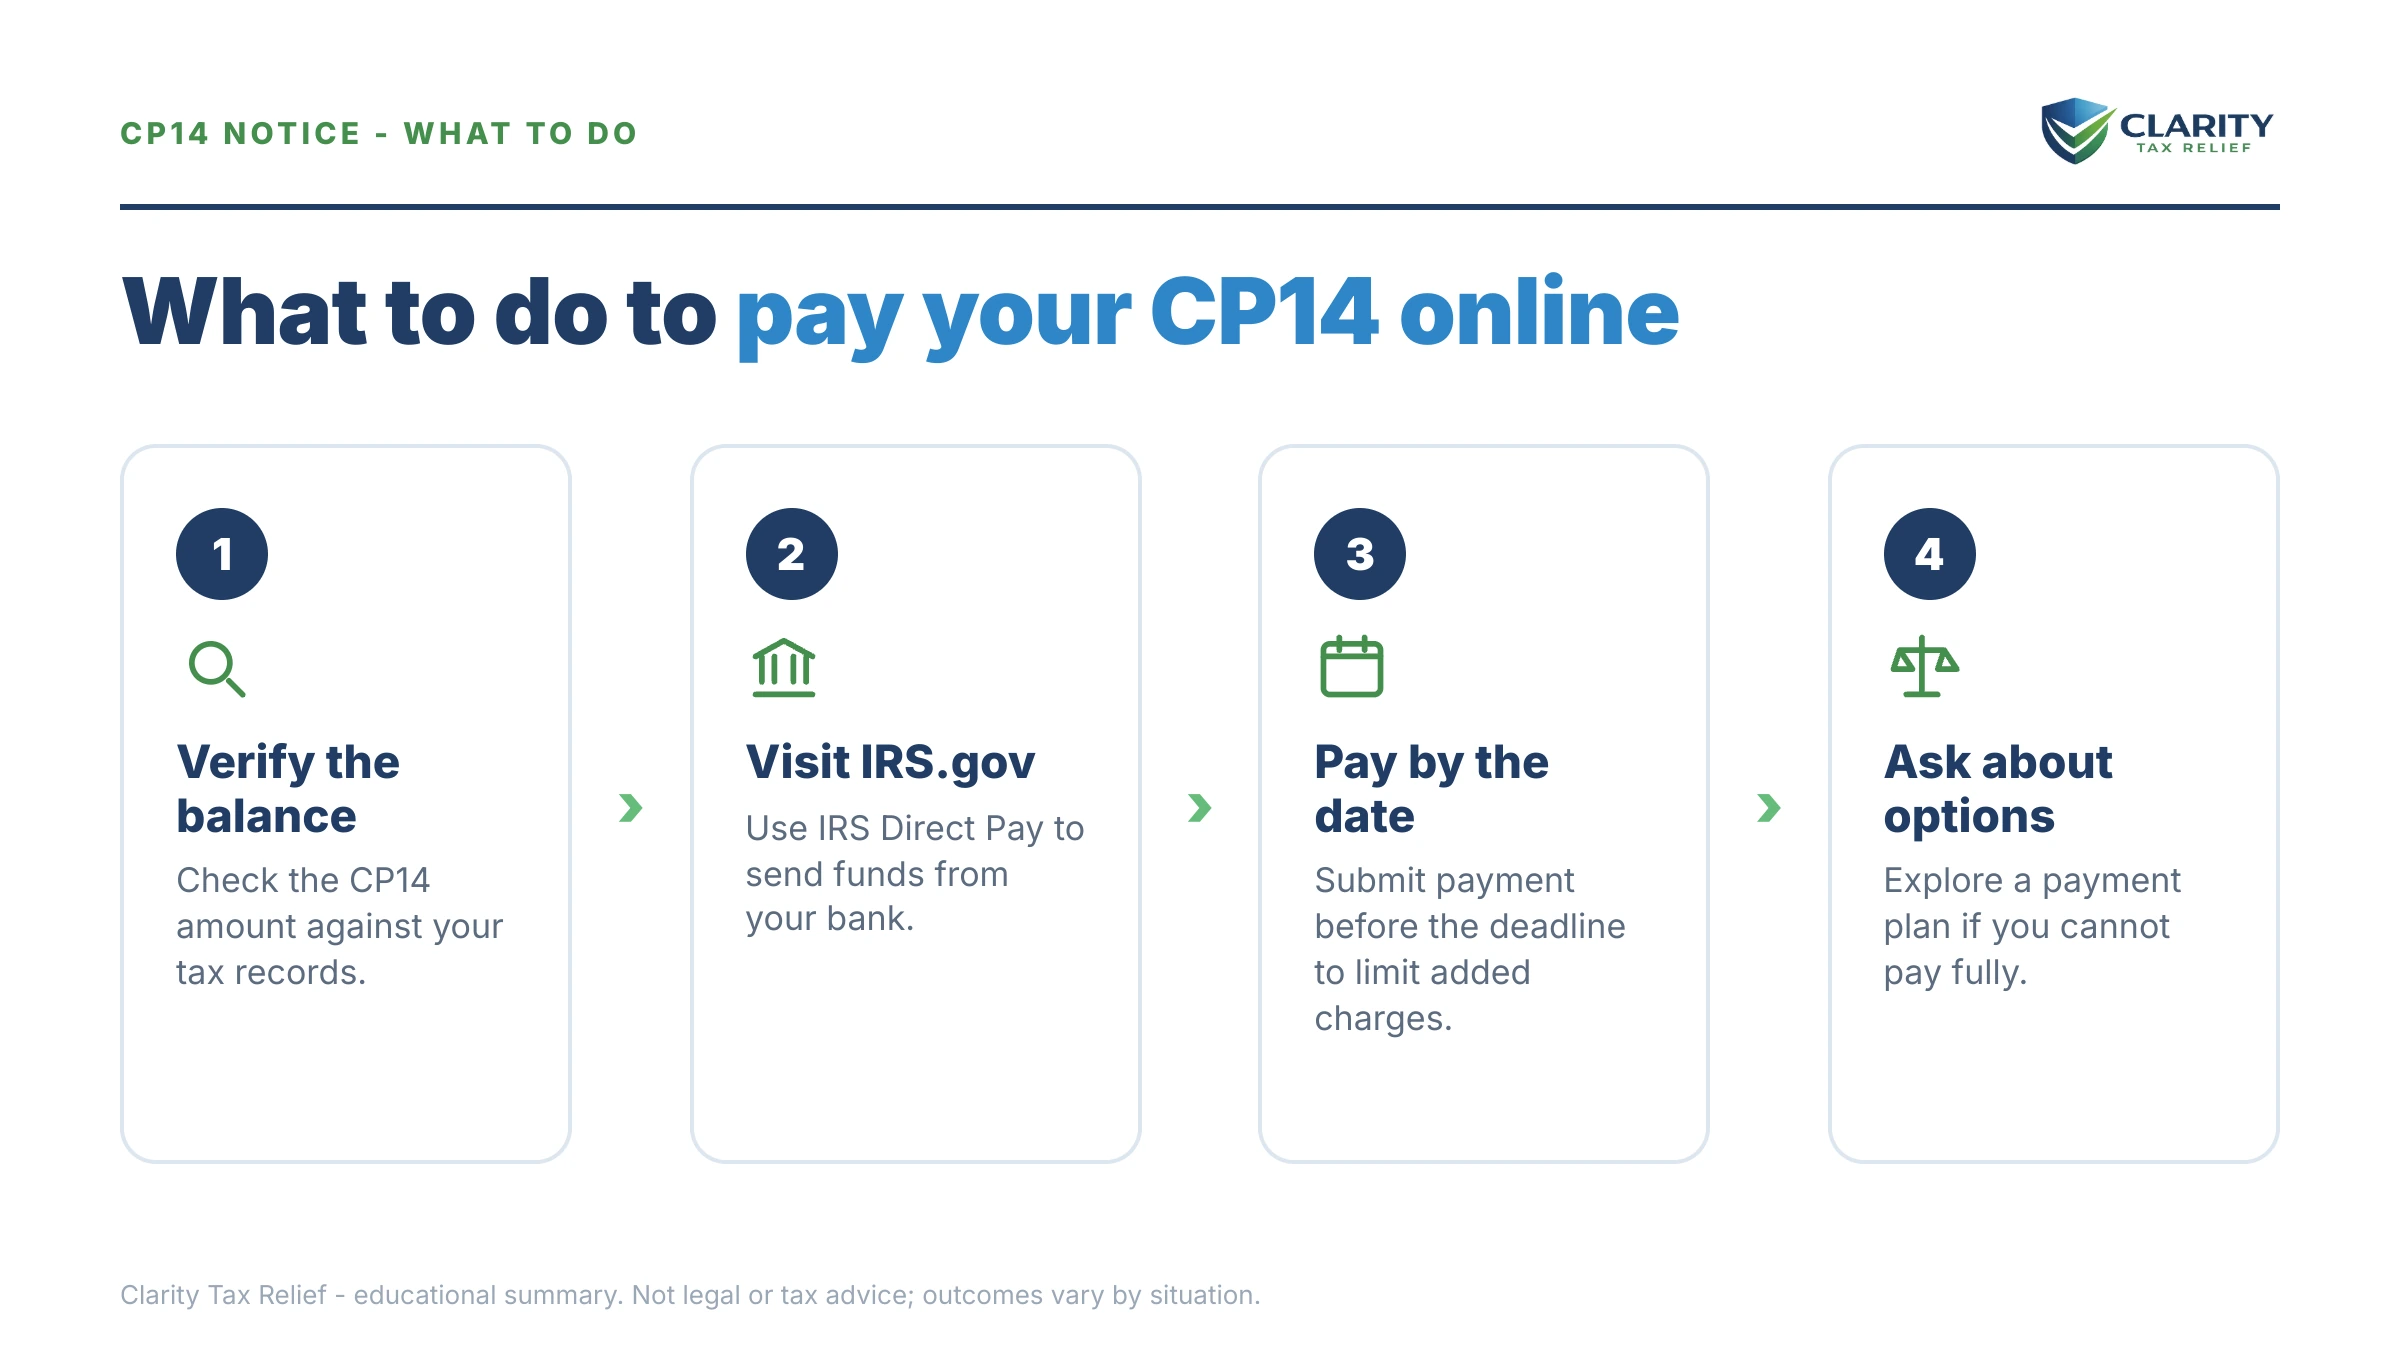
- Verify the balance. Log into your IRS Online Account and compare the balance there against the amount printed on your CP14. Confirm the tax year matches and any payments you have made have posted.
- Choose your payment method. Use IRS Direct Pay at irs.gov/payments (free, from a bank account) to pay in full, or start an Online Payment Agreement application if you need a short-term or monthly plan instead.
- Select the right reason and tax year. In Direct Pay, choose "Balance Due" as the reason for payment and select the exact tax year printed on your CP14. A payment applied to the wrong year will not stop the notices.
- Verify your identity with a prior return. Direct Pay confirms who you are using details from a past tax return (filing status, name, address, SSN, and date of birth). If you have moved recently, use the year whose return shows your old address.
- Save your confirmation number. Print or screenshot the confirmation page before closing the browser. It is your proof of payment if the CP14 crosses in the mail with a follow-up notice.
- Confirm the payment posted. Recheck your IRS Online Account within about a week to see the payment reflected against the right year. If the balance does not move, call the number on your notice with the confirmation number in hand.
The IRS's own explainer for this notice lives at Understanding your CP14 notice. Bookmark it alongside this page. If you are weighing whether to pay a firm to handle this instead of doing it yourself, our tax relief cost comparison lays out what the help costs, and the IRS hold times study shows why the online tools beat the phone for a simple payment.
When can you handle this yourself, and when should you get help first?
Most CP14s do not need professional help, and it would be dishonest to tell you otherwise. Handle it yourself if:
- The balance matches your return and you can pay in full. Direct Pay takes ten minutes.
- You can pay within 180 days and owe less than $100,000. The short-term plan is free to set up and self-explanatory.
- You owe $50,000 or less and the monthly payment fits your budget comfortably.
Experienced help matters when:
- The plan payment would break your budget. Committing online to $331 a month you cannot sustain sets up a default. A defaulted agreement puts you back in the collection stream with less goodwill. Hardship status or a partial-payment plan may fit better, but both take financial documentation done right.
- You have unfiled years. Payment plans require all returns filed. The order you fix things (returns, penalties, then the balance) changes what you ultimately pay.
- The CP14 covers multiple years or a disputed amount. Paying the wrong year, or paying a balance you could have contested, is money you don't get back easily.
- Enforcement is already in motion. If this CP14 arrived alongside a CP504 or LT11 for another year, the clock you are on is shorter than this notice suggests.
What should you check before and after you pay?
- Is it the real IRS? Type irs.gov directly into your browser. Never follow a link from an email, text, or search ad, because the IRS does not initiate contact that way. Real IRS payments go only to the United States Treasury through irs.gov, EFTPS, or the two card processors the IRS lists. Anyone directing you to gift cards, wire transfers, or payment apps is a scammer.
- Notice amount or live balance? Pay the notice amount if you pay by the printed due date. After that date, pay the current balance from your IRS Online Account. Underpaying by even a few dollars leaves the account open and generates another notice.
- What paying stops. Paying in full stops new penalties and interest from accruing as of your payment date. It does not erase the ones already charged, and first-time penalty abatement may remove the failure-to-pay penalty even after you have paid.
What do the terms on your CP14 mean?
- Notice date: the issue date in the top-right corner. Your response window and the interest math both run from here.
- Amount due: the total that is accurate only through the pay-by date; interest accrues daily after it.
- Failure-to-pay penalty: 0.5% of the unpaid tax per month or part of a month (capped at 25%), reduced to 0.25% for an individual who filed on time while an approved payment plan is in effect, and raised to 1% if you do not pay within 10 days of a notice of intent to levy.
- Interest: 7% a year on underpayments for the quarter beginning October 1, 2026, set each quarter by the IRS and compounded daily.
- Direct Pay: the IRS's free bank-transfer tool. No registration, and a confirmation number for every payment.
- Installment agreement: an official IRS monthly payment plan; enforcement stops while it stays in good standing.
- Levy: the actual seizure of money or property (wages, bank funds, Social Security), available to the IRS only at the far end of the notice sequence, not at CP14.
If your CP14 balance is large, disputed, or stacked on top of other tax years, a free review of the notice before you pay online can keep you from locking in the wrong move. Request a free CP14 review here or call (888) 825-7779. The investigation fee, if you go further, is $495 for individuals and $695 for businesses, and the pricing page lists it in full.
Bottom line
For most people, paying a CP14 online means IRS Direct Pay at irs.gov/payments: free, no login, "Balance Due," and the exact tax year from the notice. Pay by the printed date and the notice figure is exact. If the full amount is out of reach, the Online Payment Agreement handles short-term plans under $100,000 and long-term plans at $50,000 or less. Save the confirmation number, then check about a week later that the payment landed on the right year.
Your next 24 hours
- Find the two numbers that control everything: the notice date and pay-by date in the top-right corner of your CP14, and the exact amount due. Write them down.
- Gather what any online payment or plan needs: last year's tax return (for identity verification), your bank routing and account numbers, and the notice itself.
- Act before the pay-by date: if the balance is right and affordable, pay or set up your plan today at irs.gov/payments. If it is wrong, bigger than your budget can absorb, or stacked on other tax years, get a free case review first (the 2-minute form or (888) 825-7779) before the due date on your notice.
Pay a CP14 notice online: common questions
Can I pay a CP14 notice online?
Yes. Go to irs.gov/payments and pick a method. IRS Direct Pay is free, needs no login, and pays straight from a bank account. Your IRS Online Account, a debit or credit card through an IRS-listed processor, and EFTPS also work. Whichever you use, select the exact tax year printed on your notice.
What is the irs.gov/cp14 page, and is that where I pay?
The IRS explains the notice at irs.gov/individuals/understanding-your-cp14-notice. That page tells you what the notice means and links to the payment tools, but it is not the payment page itself. Payments are made at irs.gov/payments (Direct Pay, card, EFTPS) or through your IRS Online Account.
Can I set up an irs.gov/cp14 payment plan online instead of paying in full?
Yes. The Online Payment Agreement at irs.gov/payments/online-payment-agreement-application offers a short-term plan (180 days or less) if you owe less than $100,000, and a long-term plan if you owe $50,000 or less in combined tax, penalties, and interest and have filed all required returns. Short-term plans have a $0 setup fee. Long-term plans cost $29 online with direct debit or $69 without, and low-income applicants can have the fee waived or reduced to $43.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.
Read the transcript
Host: So you've got a CP14 sitting in front of you. It's a bill from the IRS, there's a pay-by date on it, and there's a tear-off stub and an envelope like it's still 1995. And you'd rather just pay it from your kitchen table and get a confirmation number.
Tax specialist: That instinct's right, honestly. And the reason isn't just convenience. An online payment gets credited the day you submit it. A mailed check has to get opened, posted, and matched to your account, and that can take weeks.
Host: And the notice machine doesn't wait for the mail.
Tax specialist: It doesn't. The sequence behind a CP14 is automated. Nobody's deciding to send the next letter. So if your check is sitting in a pile unopened while the clock runs out, the next notice mails anyway. And in 2026 that's a bigger risk, not a smaller one, the IRS cut roughly 27% of its workforce in 2025. Fewer hands on paper. Same automated notice stream.
Host: Okay. So the fastest free route?
Tax specialist: IRS Direct Pay at IRS dot gov. No login, no registration. You pick "Balance Due" as the reason for payment, and then you select the exact tax year printed on your notice.
Host: Wait, how much does the tax year actually matter? Because I feel like people just,
Tax specialist: It matters completely. A payment applied to the wrong year won't stop the notices. The money's not lost, but the account for that year still shows a balance, and the sequence keeps running. So the tax year on the notice is one of the two numbers that controls everything you're about to do.
Host: What's the second?
Tax specialist: The amount due. And here's the wrinkle. That amount is only exact through the pay-by date printed on the notice. Interest compounds daily after that.
Host: So if I'm already past the date, I'm underpaying?
Tax specialist: Right. Even a week late, if you pay the notice figure, a small residual balance survives, and that generates another notice. So if you're paying late, log into your IRS Online Account and pay the live balance there instead. That figure includes interest through today.
Host: Say that simpler for me.
Tax specialist: On time, pay the notice. Late, pay the number in your online account.
Host: Got it. And the deadline itself is what, 21 days?
Tax specialist: Typically 21 days from the notice date. But if the balance is $100,000 or more, it's 10 business days.
Host: 10 business days. That's tight.
Tax specialist: It is. Both dates are in the top-right corner of the notice, notice date and pay-by date. Write them down before you do anything else.
Host: Okay, let's talk about what's on the other side of that date. Because I think that's the part causing the anxiety.
Tax specialist: Sure. At CP14 there's no enforcement power. It's a bill. That's actually the cheapest point in the whole sequence to deal with it. Then you get CP501 and CP503, reminders, usually several weeks apart, while the failure-to-pay penalty and interest compound the whole time.
Host: Still just letters.
Tax specialist: Still just letters. CP504 is where it turns. That's the Notice of Intent to Levy under IRC 6331(d). At that point the IRS can take your state tax refund, and a federal tax lien becomes a live possibility. Then LT11, also issued as Letter 1058, that's the final notice. It starts a 30-day clock and it opens your Collection Due Process appeal rights, Form 12153. After that window, wage and bank levies are on the table.
Host: And for someone on Social Security?
Tax specialist: That's the far end. The Federal Payment Levy Program can take up to 15% of every benefit payment, continuously, until the balance is resolved. Not at CP14. But that's where the road goes if nothing happens.
Host: Okay. So, the person who can't write the check today. What are they actually looking at online?
Tax specialist: Depends on the number. Under $50,000 in combined tax, penalties, and interest, you can generally apply online for a long-term installment agreement, up to 72 months, with no financial disclosure. Between $25,000 and $50,000, direct debit is required, the payment has to come out of your bank account automatically.
Host: And under $10,000?
Tax specialist: There's a program actually named the Guaranteed Installment Agreement, that's IRC 6159(c). The name is the statute's, not a promise about your case. It's for smaller balances with a clean filing history where you can pay within three years.
Host: And over $50,000?
Tax specialist: Online long-term plans aren't available. Expect Form 9465 plus financial disclosure. Form 9465.
Host: There's also the short-term option, right?
Tax specialist: Up to 180 days, zero setup fee, any balance. But understand what a plan does and doesn't do. A payment arrangement stops enforcement. It does not stop the meter. Interest and the failure-to-pay penalty keep accruing.
Host: Hm. So what's the actual benefit besides breathing room?
Tax specialist: One real mechanical benefit, on an approved installment agreement, the failure-to-pay penalty drops from 0.5% of the unpaid tax per month to 0.25%. Half. That's built into the statute, not a favor someone does for you.
Host: Okay, that's the part people miss.
Tax specialist: The article runs the math on a $23,800 balance. On a 180-day short-term plan, that penalty's around $119 a month, roughly $714 over six months in penalty alone, plus daily compounding interest. On a 72-month agreement, that's about $331 a month before interest, and the penalty starts around $59.50 instead of $119.
Host: $331 a month. On a fixed income that could be,
Tax specialist: That's the hard part, yeah. And I want to name it honestly. If $331 isn't survivable, committing to it online sets up a default. A defaulted agreement puts you back in the collection stream with less goodwill than you had. Currently Not Collectible status, or a lower partial-payment arrangement, may fit better, but both take financial documentation done properly. That's a conversation to have before you click submit, not after.
Host: What else should make someone pause before paying?
Tax specialist: Unfiled years, payment plans require all required returns filed, and the order you fix things changes what you end up paying. A balance you think is wrong, don't pay it assuming the IRS sorts it out later. And if this CP14 showed up alongside a CP504 or an LT11 for a different year, your real clock is shorter than this notice suggests.
Host: And the penalty on the notice isn't necessarily permanent.
Tax specialist: Correct. If it's your first penalty after three clean years, first-time penalty abatement can remove the failure-to-pay penalty, even after you've paid. And starting summer 2026 there's the Automatic Exemption from Penalty, which applies similar relief with no request needed.
Host: Two quick ones. Card payments?
Tax specialist: Legal, through processors linked from IRS dot gov. Flat fee on debit, roughly 2% on credit. On a five-figure balance that's real money, and card interest usually beats the IRS rate. Use it only if you have no bank account.
Host: EFTPS?
Tax specialist: Free, but enrollment needs a PIN mailed to you, about a week. Too slow for a CP14 deadline. Wrong tool.
Host: So what does the listener do in the next hour?
Tax specialist: Find the notice date, the pay-by date, and the exact amount. Pull last year's return for identity verification, Direct Pay checks filing status, name, address, Social, date of birth. If you've moved, use a year whose return shows your old address. Have your routing and account numbers ready. Then type IRS dot gov straight into the browser, never a link from an email or a text.
Host: And save the confirmation.
Tax specialist: Print it or screenshot it before you close the window. Then check your Online Account in about a week to see it posted against the right year. If the balance doesn't move, call the number on the notice with that confirmation number in hand.
Host: And if the balance looks wrong, or it's bigger than your budget, or it's stacked on other years, get it reviewed before the pay-by date. That's Clarity Tax Relief, 888-825-7779. Enrolled Agents will look at the notice and tell you which route fits. No cost for the review.
Tax specialist: Just don't let the date pass while you think about it. That window is the cheapest advantage you have.