IRS Notices
What a CP14 Notice Means and What to Do (October 2026)
The short answer: a CP14 notice is the IRS's first bill for unpaid tax. The IRS says you owe money on a tax account, the notice prints the amount with penalties and interest, and you generally have about three weeks from the notice date to pay or set up a payment arrangement before the next notice goes out.
This guide explains what a CP14 is, what the amount on it covers, what happens if it sits unanswered, and how to check, dispute, pay or set up a plan for it, step by step.
Holding a CP14 right now?
Send us a photo of it. An experienced tax professional will decode exactly where you stand and what your options are. Free, confidential, no pressure.
⏱ Your deadline: the "pay by" date printed on the notice. Interest and a monthly late-payment penalty keep accruing after that date, and the IRS's automated system queues up the next notice.
What is a CP14 notice?
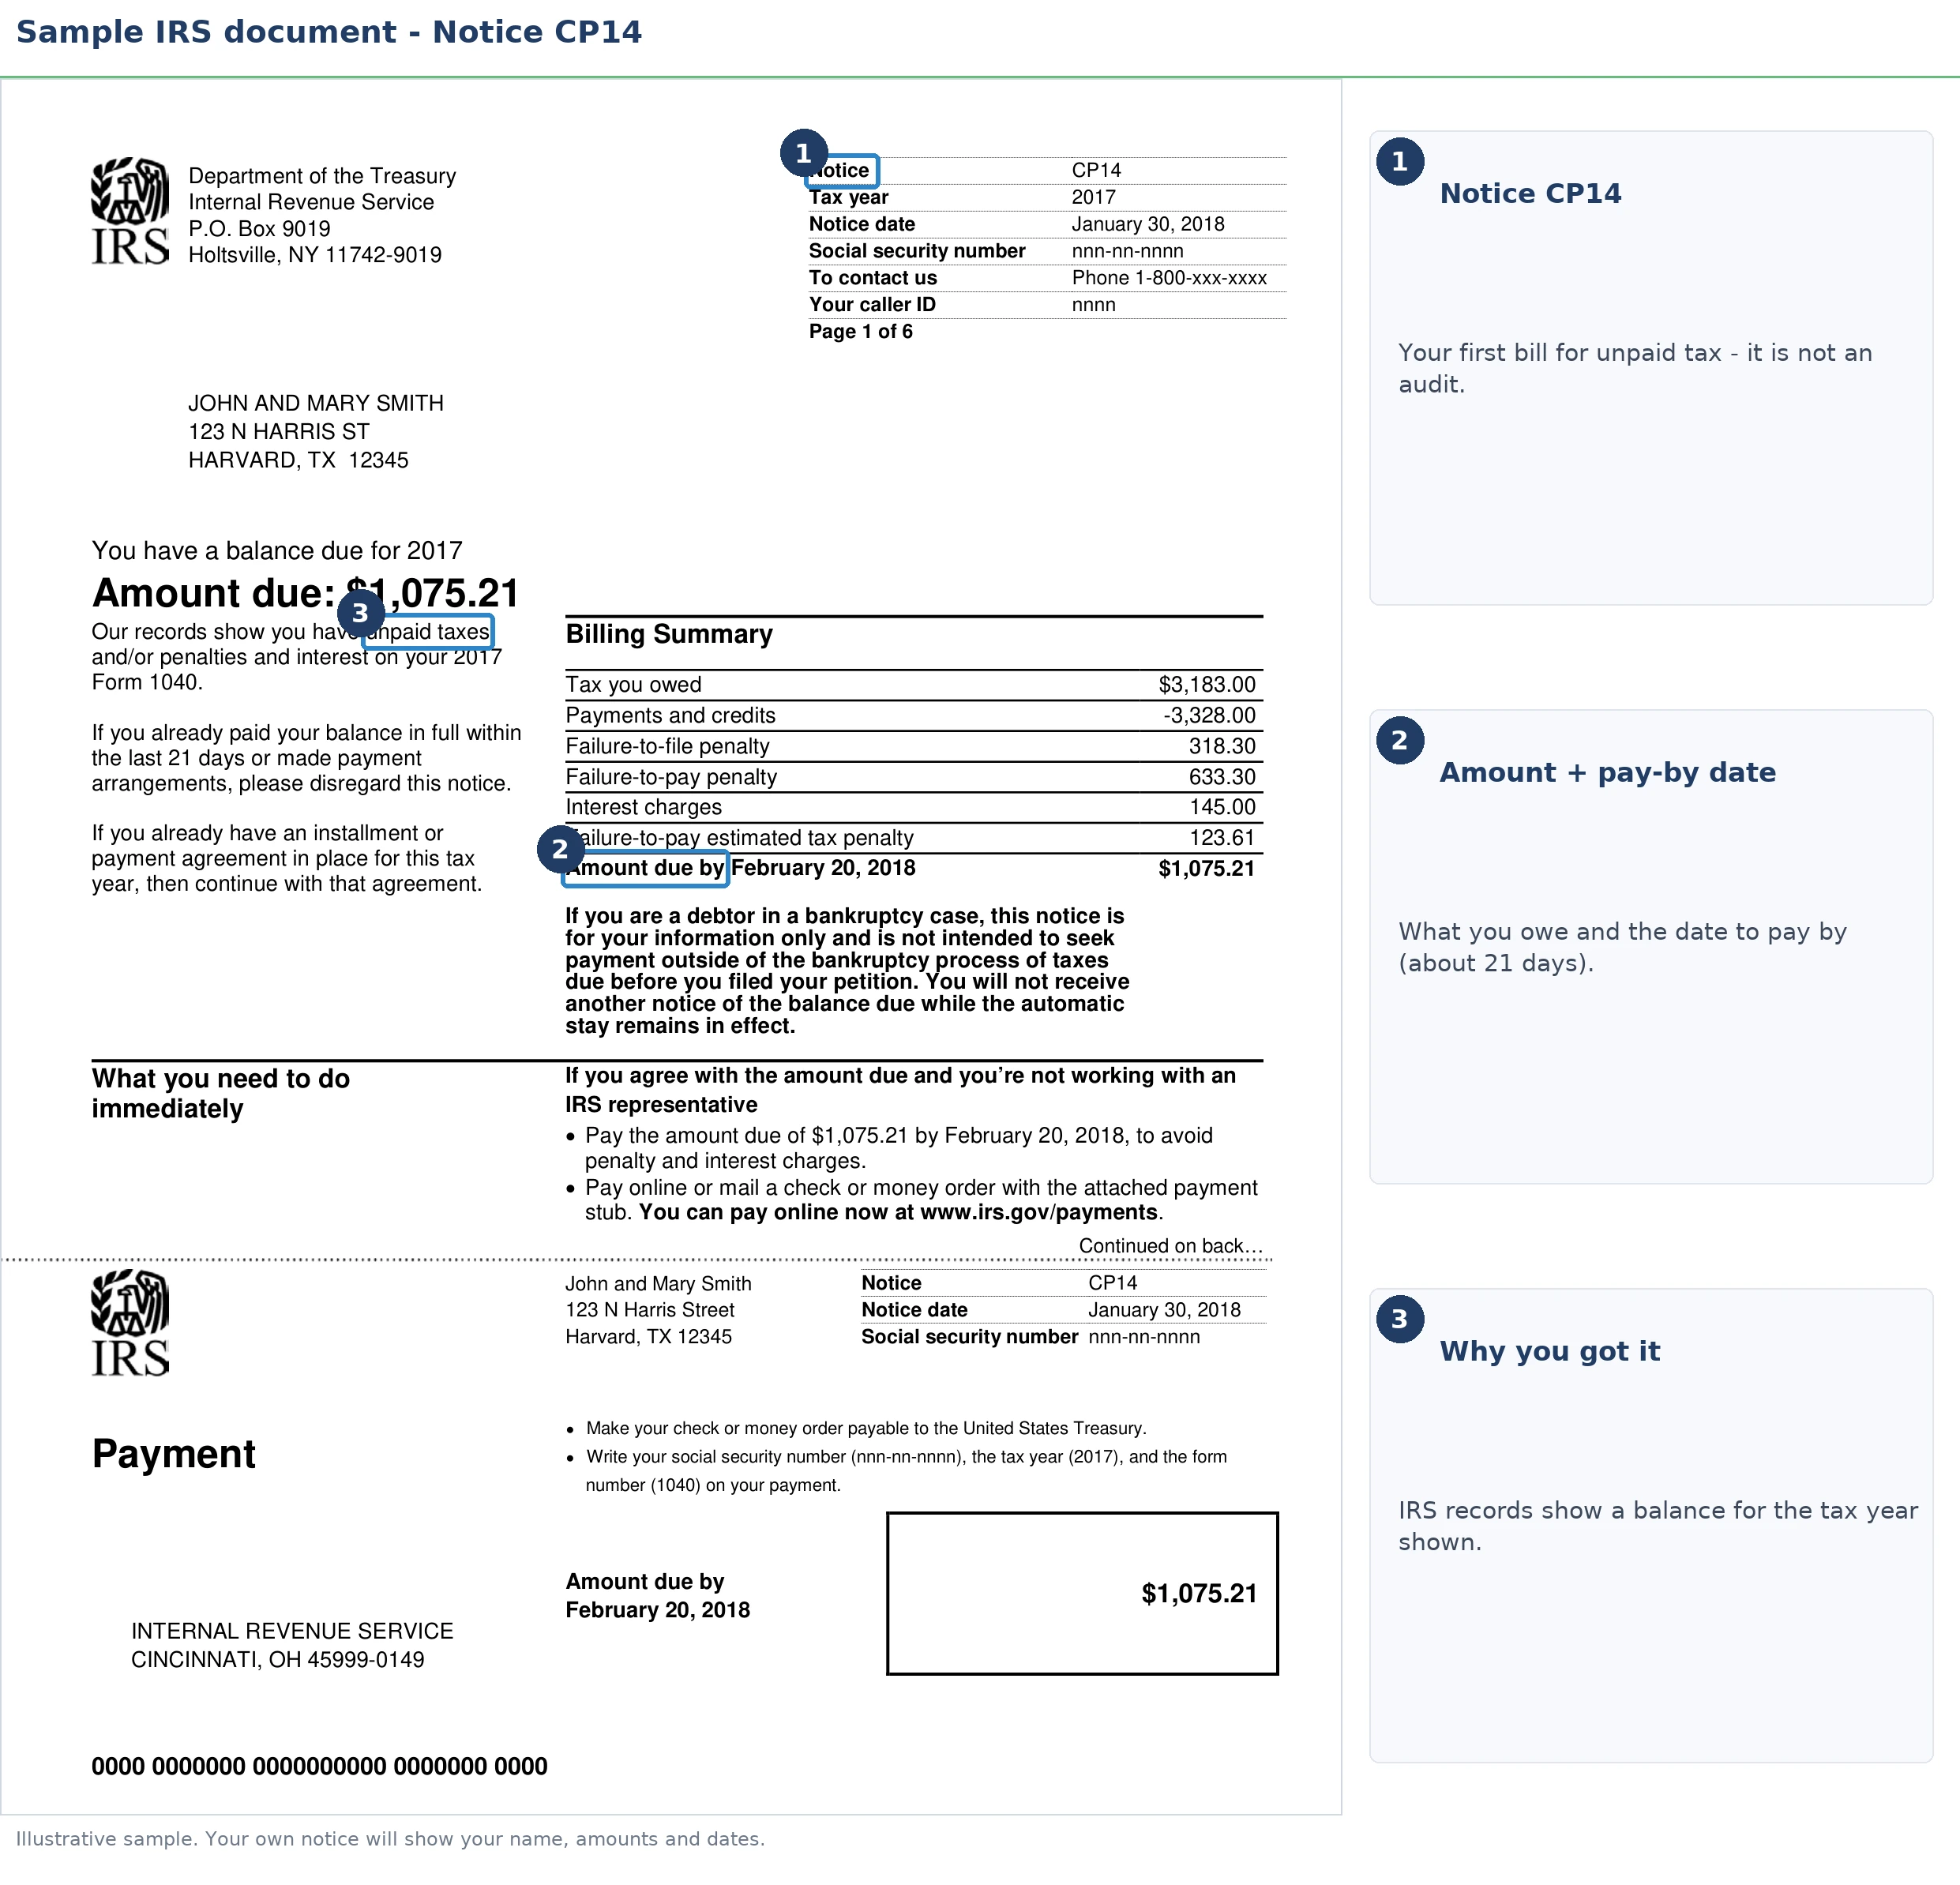
A CP14 is a balance due notice. In the IRS's own words, it goes out "because you owe money on unpaid taxes," and it is the first bill the IRS sends on that tax account. The IRS explains the notice at Understanding your CP14 notice (the short address irs.gov/cp14 lands on the same page). Nothing has been garnished or levied at this stage. It is a bill, and like most bills, it is cheapest to deal with early.
It usually arrives a few weeks after the IRS processes a return that shows tax owed. That covers three common situations: you filed and did not pay in full, you paid and the payment was not applied the way you expected, or penalties and interest were added to a balance you thought was closed.
One thing a CP14 is not: an audit. Nobody is questioning your deductions. An audit comes with different letters and a different process.
What does the amount on a CP14 include?
The figure on the notice is rarely just the tax. It is the tax the IRS says is unpaid for that year, plus any penalty already assessed, plus interest calculated to the notice date. The IRS says the notice "will explain how much you owe and how to pay it," and the breakdown between those three pieces is printed on the notice itself.
Two things follow from that. First, the number is only good until the pay-by date. The IRS states that interest does not apply if you pay the full amount by the date on the notice, and that interest accrues on the unpaid amount after that date. Second, the penalty piece may be removable. Interest on the tax cannot be removed. The failure-to-pay penalty can be abated in the right circumstances, and that is covered below.
For the quarter that began October 1, 2026, the IRS underpayment interest rate is 7% a year, compounded daily (IRS quarterly interest rates). The rate resets every quarter, so the interest line on a CP14 you receive in December is calculated at a rate that may differ from one issued in April.
What happens if you ignore a CP14?
CP14s do not expire and they do not get lost in the system. The sequence that follows is automated. Ignore each notice and the next one arrives, with more interest attached and more enforcement power behind it. Here is the sequence, using the IRS's own description of each notice.
| Notice | What the IRS calls it | What the IRS can do at this stage |
|---|---|---|
| CP14 | First bill: "you owe money on unpaid taxes" | No enforcement. Pay, set up a plan, or call the number on the notice if you disagree. |
| CP501 | "A reminder that you owe a balance on one of your tax accounts" | Still a bill. The IRS warns it can file a Notice of Federal Tax Lien and that interest and additional penalties accrue. |
| CP503 | "Your second reminder that you still owe a balance" | The IRS says it may file a Notice of Federal Tax Lien if it has not already done so. |
| CP504 | Notice of Intent to Levy, IRC section 6331(d), "your final reminder" | The IRS can seize your state income tax refund and file a federal tax lien. Pay-by language is "immediately." |
| LT11 / Letter 1058 | Final Notice of Intent to Levy: "we intend to seize your property or rights to property" | After 30 days the IRS can levy wages, bank accounts, business and personal assets, and Social Security benefits. You have 30 days from receipt to request a Collection Due Process hearing on Form 12153. |
The sources for each row are the IRS pages for the CP501, CP503, CP504 and LT11, plus the IRS Collection Due Process FAQs for the 30-day appeal window. The notices, liens and levies in this sequence are issued by automated systems. The machine keeps escalating whether or not a human ever looks at your file, which is why the cheapest moment to act is the one you are in now.
Is your CP14 right? What to check first
A meaningful share of CP14s are wrong or already resolved. Before paying anything, spend ten minutes checking:
- Log into your IRS online account and compare the balance shown there with the notice. Recent payments can cross in the mail with the CP14.
- Match the notice against your return. Same tax year? Same amounts? If you paid electronically, find the confirmation and check whether it posted to the right year. If the account transcript shows codes you do not recognize, our IRS transcript code guide decodes them.
- Screen for scams: a real CP14 arrives by postal mail, never email or text. Real IRS payments go only to the United States Treasury or through IRS.gov. Anyone asking for gift cards, wire transfers or payment apps is a criminal, and the IRS is never on the other end.
If the notice is wrong, respond with documentation, meaning proof of payment or the corrected figures. Do not pay a balance you do not owe on the assumption the IRS will sort it out later.
How do you dispute a CP14?
The IRS instruction for disagreements is short: call the phone number in the IRS Help section of the notice, and have your paperwork ready, which it describes as "cancelled checks, amended return, etc." That number reaches the function that issued the notice rather than the general switchboard. Have the notice and the return in front of you before you dial, because the first thing you will be asked is which figure you dispute and why.
Expect a wait. We placed 188 calls to IRS lines and timed every one. The results are in our IRS hold times study. If the dispute is about a payment that was applied to the wrong year, a written response with a copy of the payment confirmation is often cleaner than a phone call, and it leaves a paper trail. Keep copies of everything you send.
Disputing does not pause the clock. The pay-by date on the notice stands while you argue, and interest runs on whatever balance survives the dispute. If part of the amount is clearly right, paying that part by the date limits what accrues.
What does the penalty cost while you decide?
The failure-to-pay penalty has three rates, and which one you pay is mostly in your hands. That is the part the notice does not spell out. All three come from the IRS failure to pay penalty page.
| Situation | Monthly rate | What triggers it |
|---|---|---|
| Standard | 0.5% of the unpaid tax per month or part of a month, capped at 25% | Tax unpaid after the due date and no approved plan. |
| Approved payment plan | 0.25% per month or part of a month | An approved installment agreement, for an individual who filed on time. The balance does not have to be paid off, only the plan approved. |
| After intent to levy | 1% per month or part of a month | Tax still unpaid 10 days after the IRS sends a notice of intent to levy. |
So the spread between the best and worst rate is four to one, and what moves you between them is paperwork rather than money. Setting up a plan you can afford halves the rate, before you have paid a cent of the balance.
One detail that changes the timing of a payment: the IRS applies full monthly charges even if you pay in full before the month ends. There is no proration. Paying on the 2nd and paying on the 28th of the same month cost the same in penalty, which is an argument for paying early in a month rather than waiting for a paycheck late in it. The IRS also charges interest on penalties, so the penalty line grows on its own until it is paid.
On the pay-by date, the date that counts is the one printed on your notice. Count from the notice date printed on the letter, and not the day it reached you. Penalty and interest figures on this page were checked against IRS.gov on October 5, 2026.
How do you pay a CP14 or set up a payment plan?
If the balance is right and you can pay it, pay by the notice date at IRS.gov/payments. Whichever method you use, pick the tax year shown on the notice so the money lands against the right account. That stops interest and ends the notice sequence.
If you cannot pay in full, the notice offers two choices, pay or else. In practice the IRS has several programs, and which one fits depends on your finances:
- Short-term payment plan. Up to 180 days to pay in full, for a combined balance under $100,000 in tax, penalties and interest. No setup fee. Interest and penalties continue, but enforcement stops.
- Installment agreement. A monthly payment plan (details on the IRS payment plans page). For $50,000 or less in combined tax, penalties and interest, with every required return filed, it can usually be set up online without detailed financial disclosure, spread over up to 72 months.
- Currently Not Collectible status. If paying anything would create real hardship, collection can be paused while your situation improves. The debt remains, but garnishments and levies stop.
- Offer in Compromise. An agreement to pay less than the full balance. It exists, but only when your assets and income cannot cover the debt by the IRS's own formula, and the IRS runs the math. An experienced tax professional can tell you whether you are a candidate before you spend anything pursuing it.
- Penalty relief. First-time abatement or reasonable cause can remove the failure-to-pay penalty. Details in the next section but one.
Not sure which plan you qualify for or what the monthly figure would look like? Run your balance through our free IRS payment plan calculator before you apply. It takes about a minute and shows the payment at each term length.
Which IRS payment plan do you qualify for, and what does it cost?
The CP14 tells you to pay or set up a plan without saying which plan you can actually get. The thresholds are published, and they are simpler than most people expect. What the long-term plan costs depends entirely on how you apply and how you pay, and the gap is large. These are the IRS's current fees.
| Plan | Who qualifies | Setup fee |
|---|---|---|
| Short-term, 180 days or less | Less than $100,000 in combined tax, penalties and interest | $0 |
| Long-term, online, direct debit | $50,000 or less combined, all required returns filed | $29 |
| Long-term, online, other payment method | Same | $69 |
| Long-term, by phone, mail or in person, direct debit | Same | $107 |
| Long-term, by phone, mail or in person, other method | Same | $178 |
| Long-term, low-income applicant | Same, income test applies | $0 with direct debit; $43 otherwise, which may be reimbursed |
| Revising an existing plan | Any approved plan | $6 online; $89 by phone, mail or in person |
So the whole fee question comes down to two clicks: apply online, pay by direct debit. That is a $149 difference on the same agreement, before you count what the approved plan does to the penalty rate described above. The filing condition is the one that catches people: an unfiled year blocks the online plan no matter how affordable the payment is.
Over $50,000, or with returns still missing, the online route closes and the IRS wants financial detail on Form 433-F before it agrees to anything. That is a different conversation. If the balance is large enough that you are weighing professional help, our tax relief cost comparison shows what the national firms charge against doing it yourself, and the IRS Fresh Start program page explains what that marketing term actually covers.
Can the penalties on a CP14 be abated?
Often, yes, and the easiest route is one the notice never mentions. The IRS's First Time Abate waiver removes the failure-to-file, failure-to-pay and failure-to-deposit penalties, in any amount, when your recent compliance record is clean. The conditions are on the IRS first time abate page:
- The same type of return was filed on time for the prior three years.
- No penalties were assessed in those three years, or any that were assessed were later removed for reasonable cause or IRS error.
- You have filed every required return and have paid, or arranged to pay, the tax that is due.
You request it by calling the toll-free number in the top right corner of the notice, or in writing with a statement or Form 843. You do not have to name the program or send documents. The IRS checks your account against the requirements. Interest on the tax itself is not abated.
If you do not qualify for First Time Abate, reasonable cause relief covers illness, disaster, death in the family and other circumstances outside your control, with documentation. No outcome is guaranteed in either route. The IRS decides on the facts.
What does the IRS say about this notice?
The IRS puts it plainly: this notice goes out because you owe money on unpaid taxes. It is the first of the balance due notices on that tax account. The instruction is to read the notice carefully, pay the amount you owe by the due date on the notice, make a payment plan if you cannot pay the full amount, and contact the IRS if you disagree. Those four sentences are the whole of the IRS's own guidance, which is why the rest of this page exists.
How to respond to a CP14, step by step
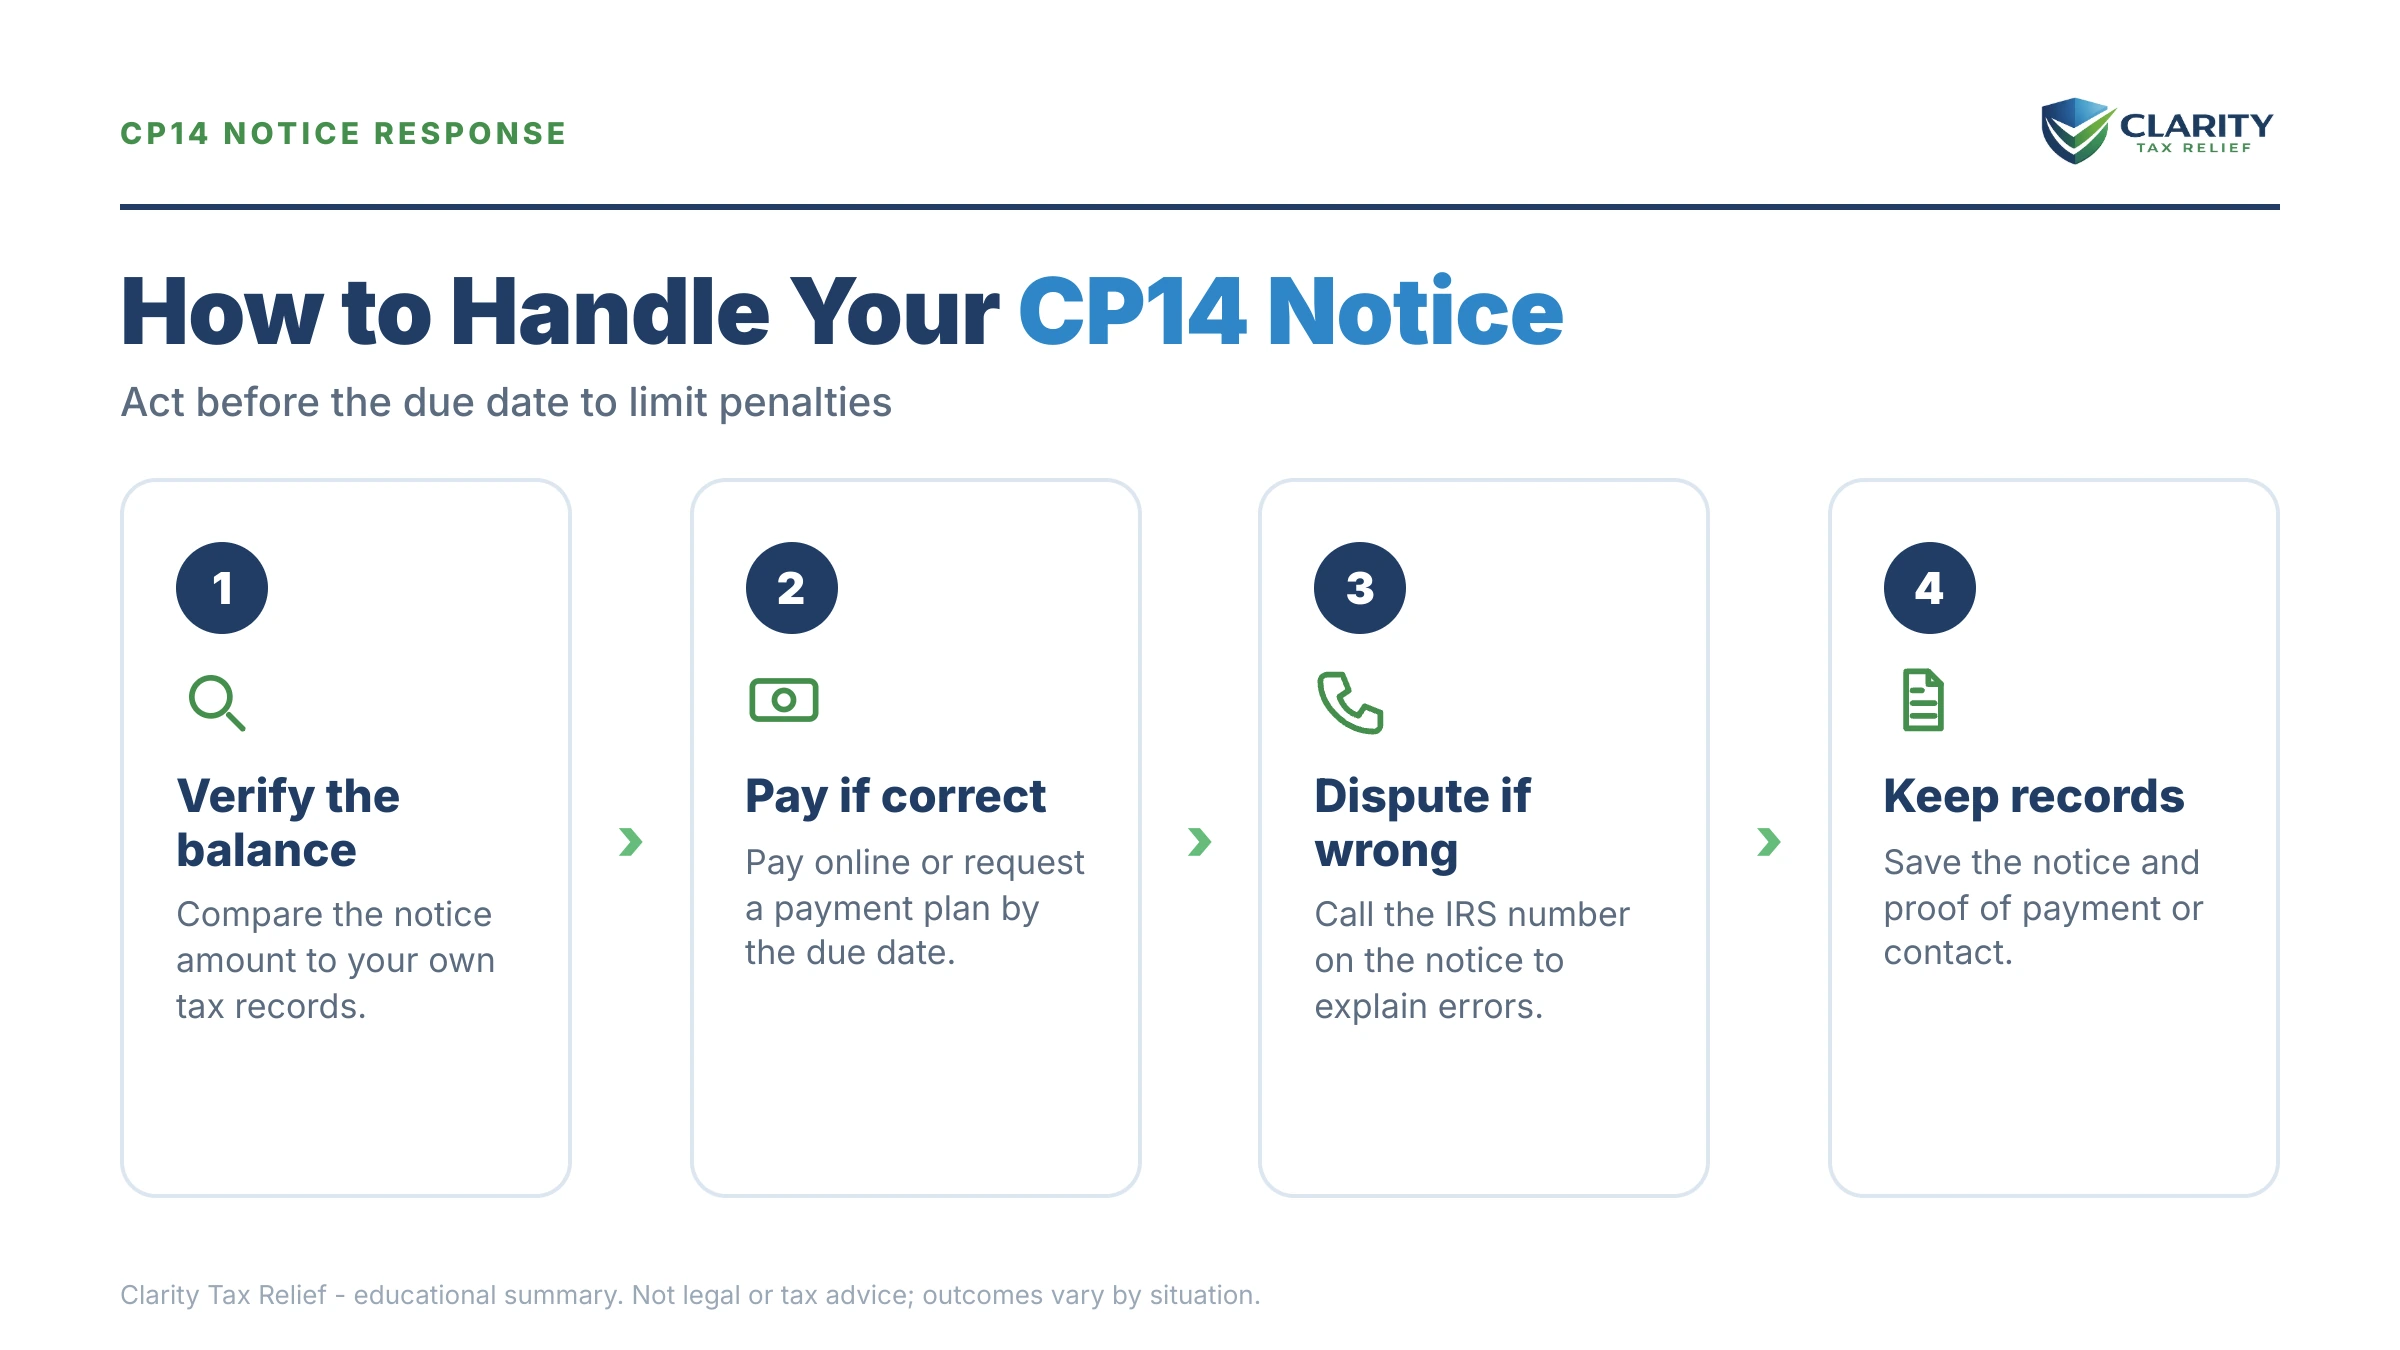
- Verify the balance against your IRS online account and your records (see above).
- If it is correct and you can pay: pay by the notice date at IRS.gov/payments. That stops interest and the notice sequence.
- If you cannot pay in full: pick the plan above that fits and set it up before the deadline. Even a payment plan you start today prevents everything that follows, and halves the penalty rate.
- Ask about penalty abatement once the tax is paid or a plan is approved. First Time Abate is a phone call.
- If the notice is wrong: respond in writing with proof, and keep copies of everything.
- If you owe more than $10,000, have unfiled years, or just want it handled: get a professional review first. The order you fix things in (returns, penalties, then the balance) changes what you end up paying.
Common questions
How long do I have to pay a CP14?
Pay by the date printed on the notice. Count from the date on the letter, and not the day it reached you. Miss it and interest plus the monthly late-payment penalty keep running, and the next notice is queued automatically.
What if I can't pay the amount on my CP14?
You have options the notice does not advertise: a short-term plan of up to 180 days with no setup fee, a monthly installment agreement (from $29 to set up online with direct debit), hardship status that pauses collection, or, when your finances qualify under the IRS formula, an Offer in Compromise. An approved plan also halves the failure-to-pay penalty rate to 0.25% a month.
Does a CP14 mean I'm being audited?
No. A CP14 is a bill, and an audit is a different process with different letters. It means the IRS processed your return and shows a balance due, from tax you reported but did not fully pay, a penalty, or interest. Nobody is questioning your deductions.
Bottom line
A CP14 is a first bill, and it is the cheapest point to deal with the balance. Check it against your online account, pay by the printed date if you can, and set up a plan before that date if you cannot. Once that is done, ask about First Time Abate.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.