
IRS Transcript Codes
Code 290 on an IRS Transcript: What "Additional Tax Assessed" Means in 2026
What this episode covers
- What does IRS code 290 with $0.00 mean on a tax transcript?
- What does IRS code 290 with a dollar amount mean on a tax transcript?
- Why is the date next to IRS code 290 in the future?
- How do I dispute an incorrect IRS code 290 assessment?
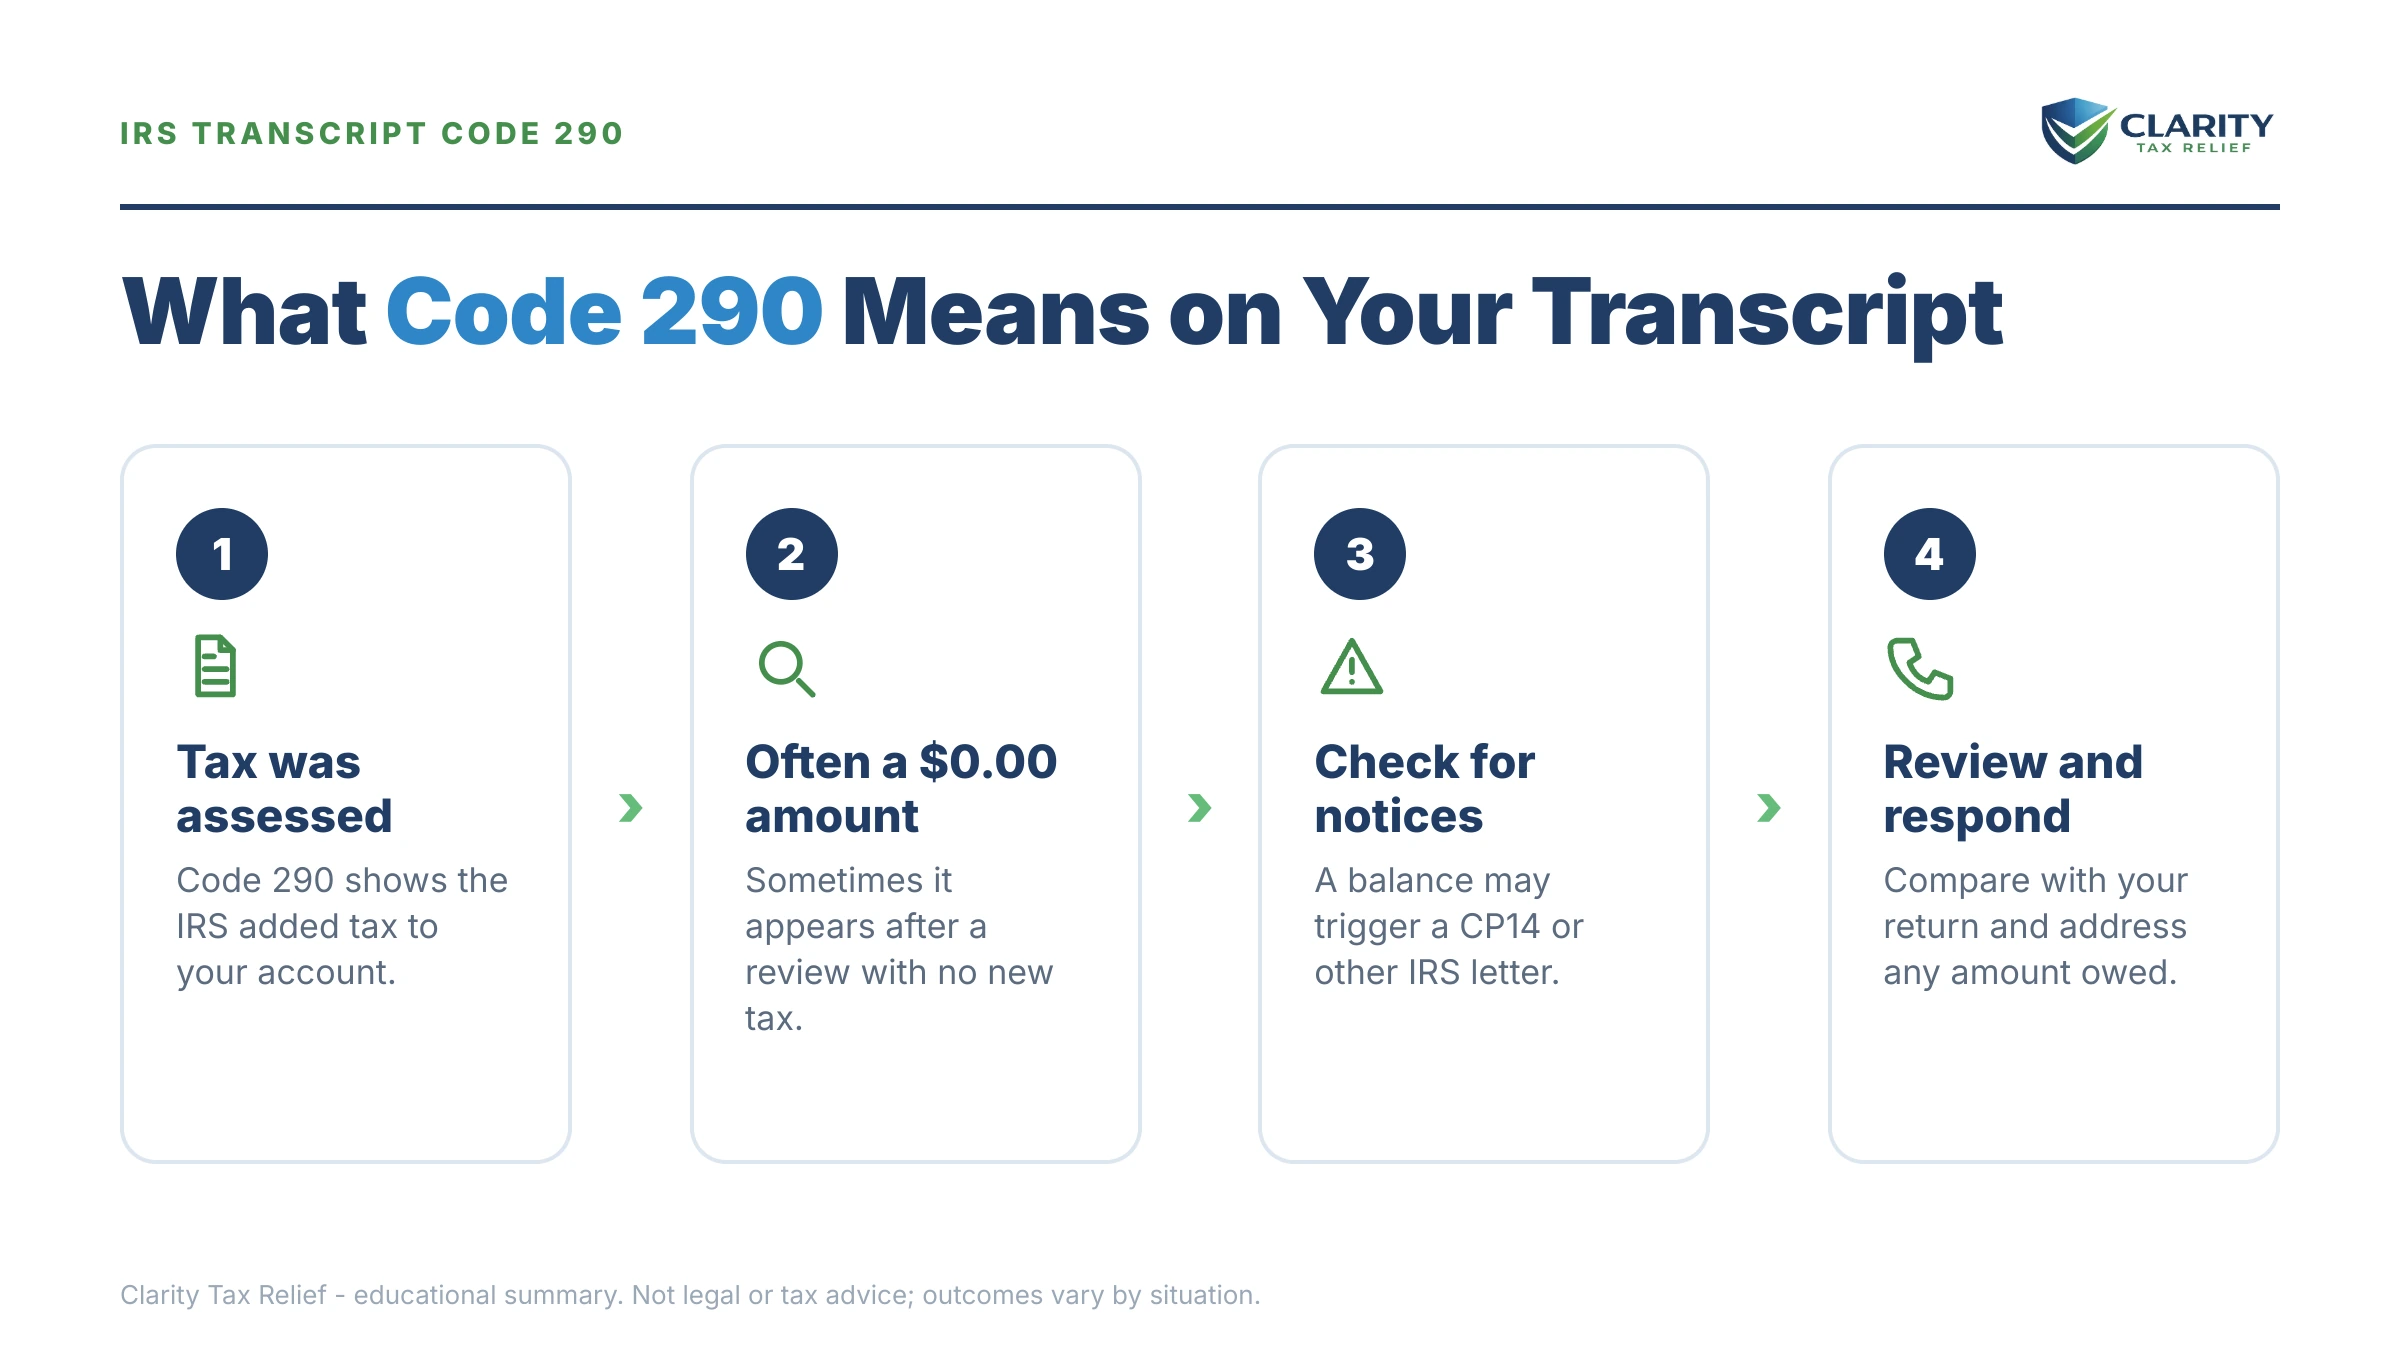
The short answer: code 290 on an IRS transcript means "Additional Tax Assessed." With a dollar amount, the IRS added that tax to your account, usually after a CP2000, audit, or amended return. With $0.00, a review closed with no tax added. The date beside it is the assessment date. Clarity Tax Relief reads every 290 by its amount first, because the amount decides whether you have a bill or a closed review.
You were scrolling your account transcript, checking on a delayed refund or a CP2000 you answered months ago. A new line appeared: "290 Additional tax assessed." That line is the moment an IRS review stops being a question and becomes an official number. It is either the best line on the page ($0.00) or the start of a bill, and which one you are looking at changes everything you do next.
This guide covers both versions, what the date beside the code controls, whether a 290 is bad news, when a refund follows it, and how to challenge one that is wrong. The image below shows where the 290 line sits on a real account transcript and how to read the amount and date beside it.
⏱ The real clock: a transcript never prints your deadline. A code 290 with a dollar amount starts interest running from the assessment date and queues a mailed notice with its own pay-by date. The date printed on that notice is the one that controls. The assessment date also starts the 10-year collection statute for that amount.
What does code 290 mean on an IRS transcript?
Clarity Tax Relief explains code 290 to clients as the IRS making an assessment official. Code 290 means the IRS posted an additional tax assessment to your account for that tax year. IRS Document 6209, Section 8A, the manual that defines every transcript code, titles TC 290 "Additional Tax Assessment" and describes it as "additional tax as a result of an adjustment to a module which contains a TC 150 transaction" (your filed return). When the amount is $0.00, the same entry is used to close a case or release a hold with no tax added. The dollar figure beside it, and the codes around it, tell you which of those happened.
People search this as "290 code IRS," "290 tax code," or "tax code 290," and the wording trips some readers up: there is no Section 290 of the Internal Revenue Code at work here. It is a three-digit transaction code on the account transcript, the same family as code 150 and code 570. Our IRS transcript codes reference lists the full set.
Code 290 is the transaction code the IRS uses to make an assessment official. Your account transcript is a ledger: code 150 records the tax from the return you filed, and a 290 records tax the IRS added after that. "Additional" is relative to the return, not to anything you owed before. (If transcript layout is new to you, our guide on how to read an IRS account transcript covers the full ledger. This page stays on the 290 line itself.)
Code 290 has a mirror image. Code 291 is "tax reduced," the entry that posts when an assessment is abated, which is why a wrong 290 is worth disputing rather than absorbing.
What is the difference between a code 290 for $0.00 and one with a dollar amount?
A 290 for $0.00 is a closing entry. The IRS opened some kind of review, a refund hold, an underreporter screen, an identity or income check, and needed a formal transaction to close it. Zero dollars means the review ended with no change to your tax. If your refund was stuck behind a code 570 hold, a $0.00 290 is frequently the entry that releases it. Document 6209 lists the freezes a TC 290 releases, and the list includes the refund hold (-K), the 570 hold (-R), the duplicate return freeze (-A) and the math error freeze (-G). That is why a 290 with no money attached so often shows up right before a refund moves.
“A 290 for zero dollars usually means the IRS looked and walked away. A 290 with a number is a bill, and interest on it runs from the date printed beside it,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
One narrower case: if you asked for penalty relief and a $0.00 290 appeared with no refund involved, the IRS may have used the entry to close that request. The letter that follows, marked by a 971, says whether the penalty was removed; if it was, a code 277 (penalty abated) posts too. If no 277 appears, read the letter for the denial and your appeal rights.
A 290 with a dollar amount is a new debt. The IRS has formally assessed that much additional tax against you, interest began accruing as of the date on the line, and collection treats it like any unpaid balance. You will usually see companion entries nearby: code 196 for interest assessed, code 276 for the failure-to-pay penalty, and a 971 marking the letter that explains it.
Is code 290 on a transcript bad?
It depends entirely on the amount. A $0.00 290 is neutral to good: the IRS looked at something and changed nothing, and if a refund was frozen this is often the entry right before it moves. A 290 with a dollar amount is a bill, and one that is already accruing interest. It is not an audit indicator (a full examination shows as code 420). It is not a penalty by itself. The penalties post as their own codes. The one case where a $0.00 290 deserves attention is when a 971 sits beside it, because that means an explanation letter is on its way and it is worth reading.
“The income or payment information we received from third parties, such as employers or financial institutions, doesn't match what you reported on your tax return. This difference may increase or decrease your tax or may not change it at all.”
Source: Understanding your CP2000 series notice (IRS.gov)
Why did a code 290 post to your account?
Clarity Tax Relief starts every 290 review with the codes posted around it. Most dollar-amount 290s come from a document-matching or correction process, not from a person deciding to bill you. The codes around the 290 usually tell you which process it was. The image further down shows what these entries look like in sequence on an actual transcript.
Three IRS programs produce nearly all of them: the math error unit that corrects arithmetic and missing forms during processing, the Automated Underreporter program that matches W-2s and 1099s against your return and sends the CP2000, and Examination. Each closes hundreds of thousands of cases a year, and each ends in the same transaction code when tax is added.
A 290 can come from any of those, which is the reason the code on its own tells you so little. It records that an assessment posted, not why.
| 290 amount | Companion codes | What it means | What to do |
|---|---|---|---|
| $0.00 | None nearby | A review closed with no tax added | Nothing required; if a refund is pending, watch for code 846 on upcoming updates |
| $0.00 | 570 earlier, sometimes 571 | The account hold was resolved without change and the refund freeze is released | Refund processing typically resumes on the next weekly cycles |
| $0.00 | 971 on the same or a nearby date | No tax added, but the IRS mailed a letter explaining what it reviewed | Read the letter; it may be a CP2000 closed with no change or a penalty decision |
| $0.00 | 420 or 424 still open | An exam is in progress; Document 6209 allows a zero 290 to post while a 420 is unreversed | Wait for the exam result (code 300 or 421); nothing has been assessed yet |
| Dollar amount | 922, then 971, often 196 and 276 | An underreporter (CP2000) case was finalized as an assessment, with interest and the failure-to-pay penalty | Pull the CP2000 and compare line by line; request reconsideration if the income was reported or nontaxable |
| Dollar amount | 420 or 424, then 421 | An examination adjustment was assessed (a field or office audit usually posts as 300 instead) | Check the audit letters for your appeal window; audit reconsideration is possible after assessment |
| Dollar amount | 976 or 977 earlier | Your amended return processed with additional tax | Confirm the amount matches the 1040-X you filed; question anything you did not report yourself |
| Dollar amount | 971 only, no 922 or 420 | A math error or clerical correction was assessed and a CP21A or CP22A was mailed | Match the 971 date to the letter, verify the math, then pay by the notice date or dispute |
| Dollar amount | Later 291 | Part or all of the assessment was abated after a dispute or amended return | Confirm the related 197 (interest abated) and 277 (penalty abated) posted too |
The single most common source of a surprise dollar-amount 290 is the Automated Underreporter program, the computer that matches W-2s and 1099s against your return. If a code 922 underreporter review appears earlier in the year's history and you never resolved the CP2000 notice that followed, the 290 is that proposed amount becoming real.
The IRS says a CP2000 that goes unanswered leads to "another notice and a bill"; in practice that is the CP3219A, a Statutory Notice of Deficiency with a 90-day window to petition the Tax Court, and the 290 posts once that window closes without a petition. On a joint return this often traces to one spouse's income, a side 1099, a brokerage form, a retirement distribution, that the other spouse never saw. The assessment binds you both: each spouse is fully liable for the whole amount, though innocent spouse relief may exist where one spouse hid the income.
Which codes travel with a 290, and what does Document 6209 say each one means?
Document 6209 Section 8A is the IRS's own dictionary of transaction codes. The entries below are the ones that most often sit near a 290. Reading them together is how you tell a closed review from a new bill.
| Code | IRS title (Document 6209) | What it tells you about the 290 |
|---|---|---|
| 150 | Return Filed & Tax Liability Assessed | The original return the 290 adjusts; a 290 can only post to a module that already has a 150 |
| 196 | Interest Assessed | Computer-generated interest triggered by the 290; Document 6209 says a 290 "generates assessment of interest if applicable" |
| 276 | Failure to Pay Tax Penalty | The 0.5%-per-month penalty on any part of the assessment not paid by the notice date |
| 291 | Abatement Prior Tax Assessment | Reverses a 150 or 290 "in whole or in part"; the entry you want after a successful dispute |
| 420 / 424 | Examination Indicator / Examination Request Indicator | The return went to Exam or Appeals; a dollar-amount 290 normally will not post while a 420 is open unless a priority code is used |
| 570 / 571 | Additional Liability Pending and/or Credit Hold / Reversal of TC 570 | The refund freeze and its release; a 290 also releases the 570 hold |
| 922 | IRP Underreporter | The document-matching review behind a CP2000; a 290 after a 922 is that case closing |
| 971 | Miscellaneous Transaction | With the right action code, the notice that explains the 290 was mailed on that date |
| 976 / 977 | Posted Duplicate Return / Posted Amended Return | An amended or duplicate return was received; the 290 after it is the adjustment from that return |
| 846 | Refund of Overpayment | The refund going out; after a $0.00 290 this is the entry to watch for. Code 300 is the Exam version of a 290: "Additional Tax Assessment by Examination or Appeals" |
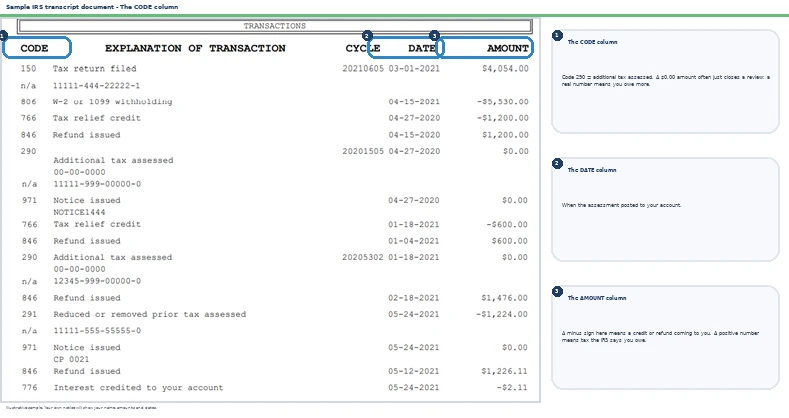
Why does code 290 show a future date, and what does the date control?
Do not panic if the date is in the future. Transcripts post on weekly cycles, and a 290's date is routinely one to three weeks ahead of the day it first appears. It is the effective date of the assessment, not a deadline you are already missing.
That date is the legal assessment date, the day the debt officially exists, and three separate clocks hang on it. First, interest is computed to that date and compounds daily after it, so the transcript figure is a snapshot that grows. The IRS underpayment rate for the quarter beginning October 1, 2026 is 7%, the same as the prior quarter. Second, the failure-to-pay penalty (0.5% of the unpaid tax per month or part of a month, capped at 25%) starts stacking on any unpaid portion; it drops to 0.25% per month while an approved payment plan is in place. Third, the assessment date starts the 10-year collection statute (CSED) for that specific amount, separate from the CSED on the original code 150 tax. A 2022 tax year with a 290 assessed in 2026 is collectible on that added amount until roughly 2036, longer if tolling events pause the clock.
How long after code 290 will I get my refund?
If the 290 is $0.00 and it closed the hold on your refund, the next entry to watch for is code 846, refund issued. The date beside the 846 is the date the money is sent. The IRS does not publish a day count between the two entries. In practice the 846 tends to post within the next one or two weekly cycles. There is nothing you need to send to make it happen. If the 290 carries a dollar amount, it is applied against any refund on the account first. When the assessment is smaller than the refund, the reduced refund still issues. When it is larger, the refund disappears and a balance-due notice follows for the difference.
What notice follows a code 290, and what clock does each one set?
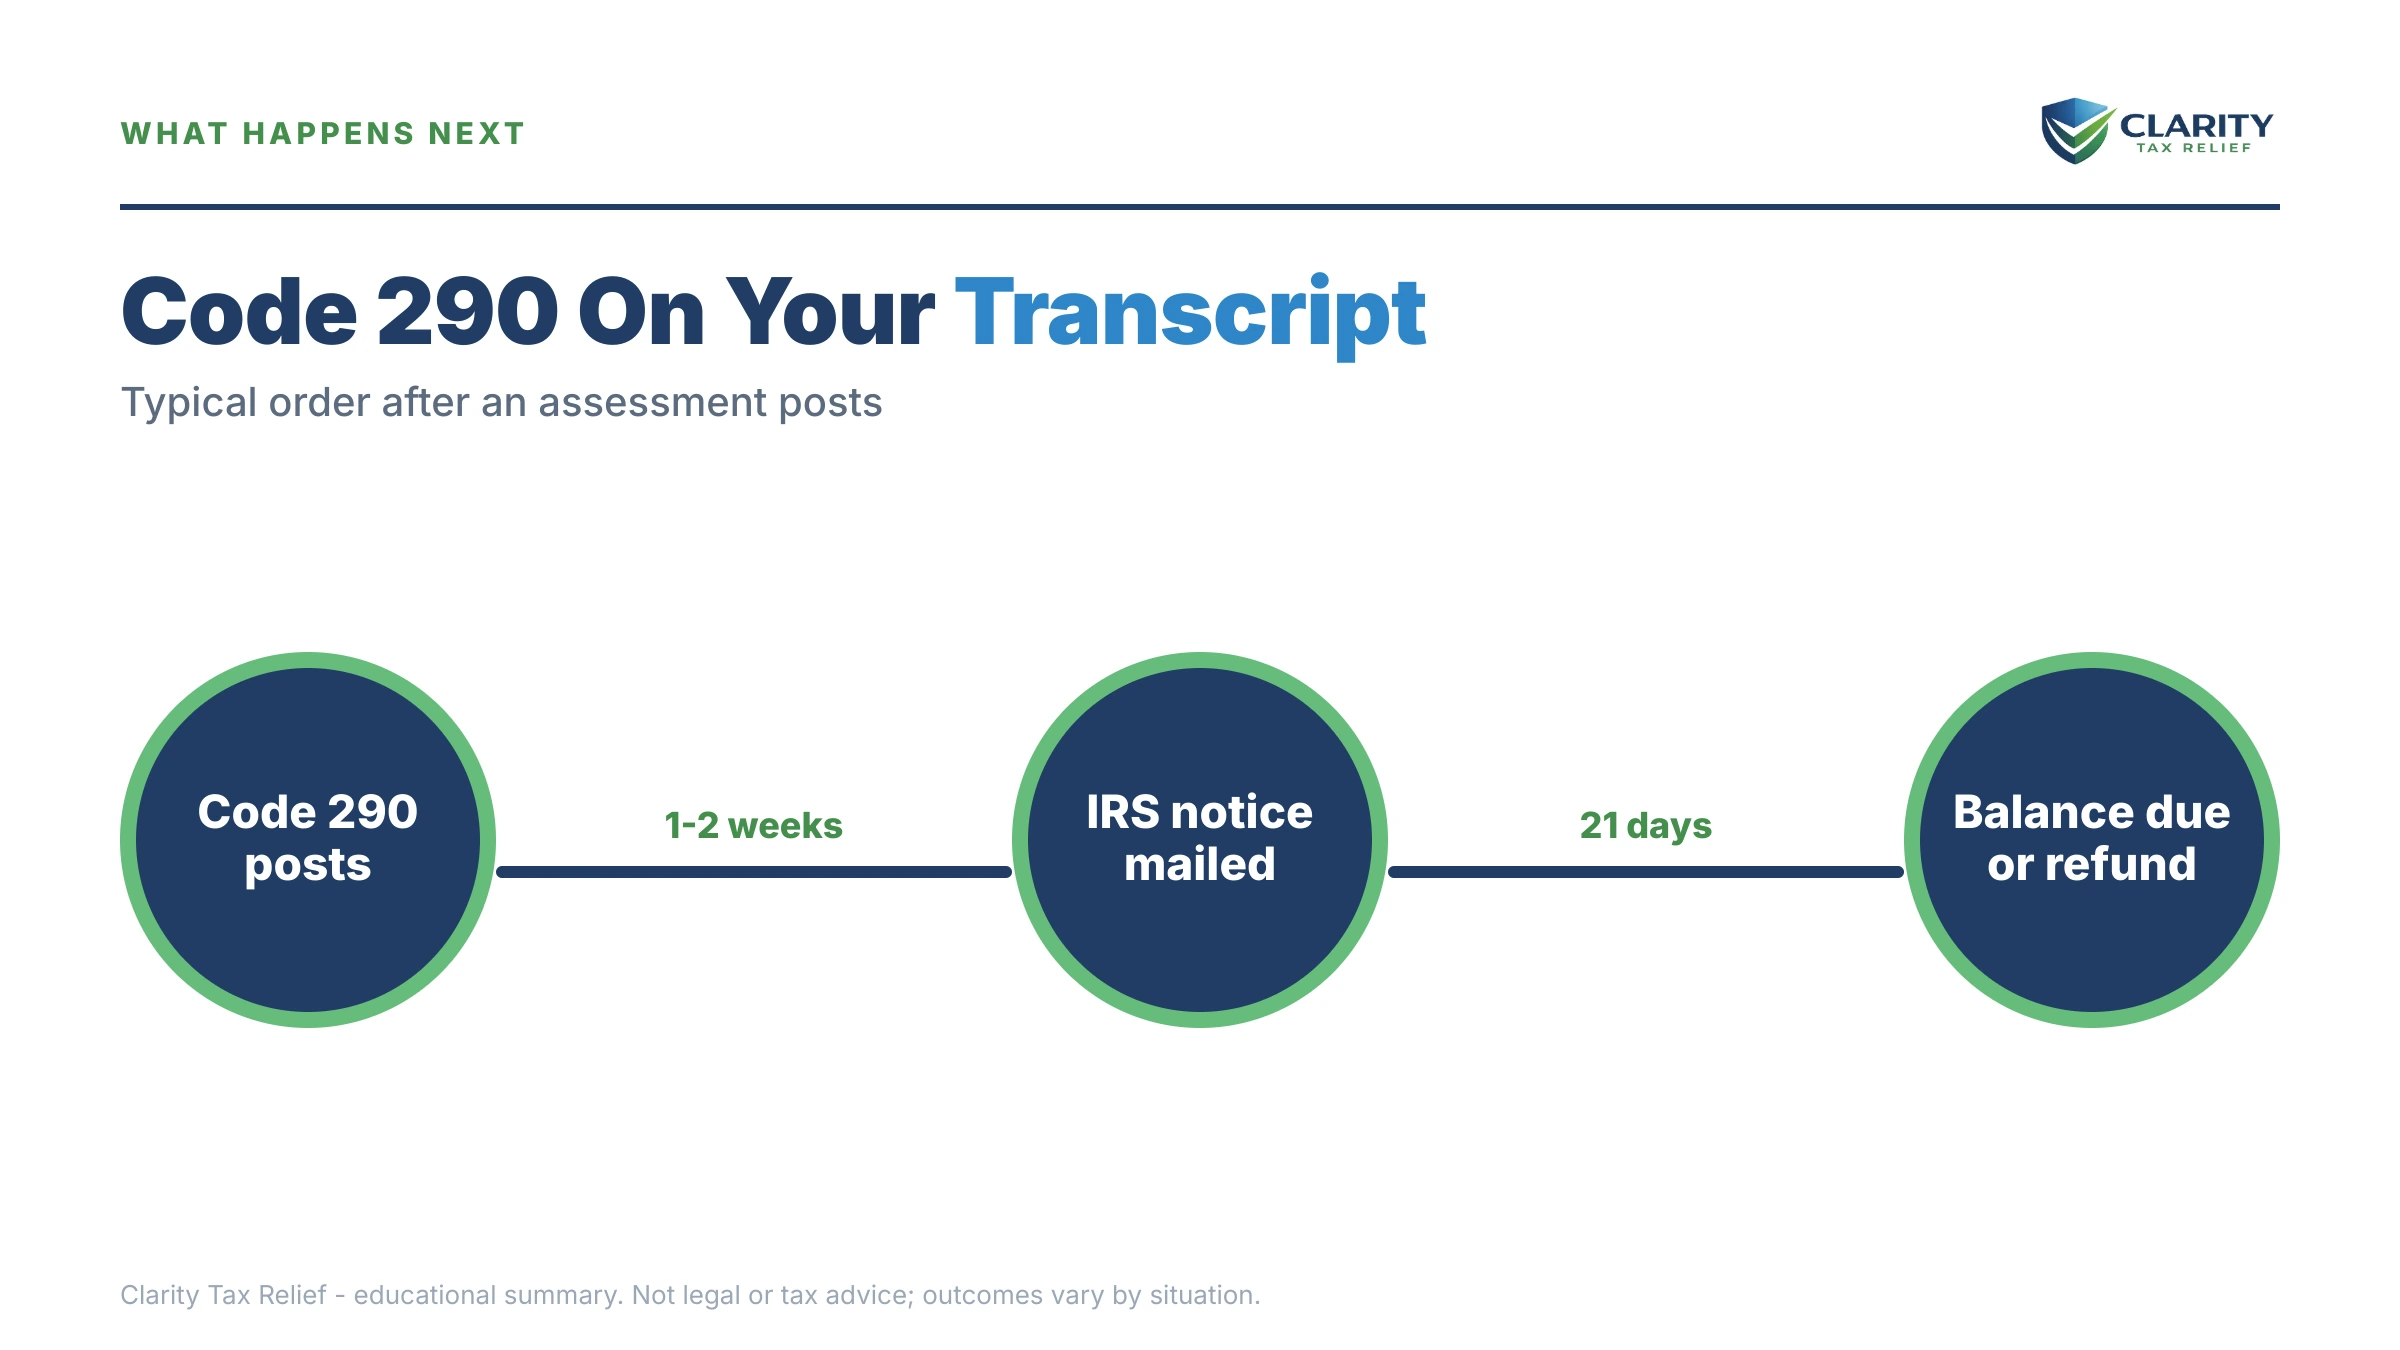
Every dollar-amount 290 produces mail, and the transcript's code 971, notice issued entry tells you when it went out. A balance you ignore enters the same automated collection sequence as any unpaid tax bill. The interest meter started on the assessment date, not the day you noticed the entry:
| Stage | What it says | The clock it sets |
|---|---|---|
| 971 posts on transcript | A notice was mailed on that date | The mailed letter's printed date starts its response window |
| CP3219A (CP2000 cases only) | Statutory Notice of Deficiency: the proposed CP2000 amount will be assessed unless you petition | The petition date printed on the notice; the IRS says the Tax Court cannot consider a petition filed late. The 290 posts after this window closes |
| CP21A / CP22A notice | The IRS changed your return; balance due | The pay-by date printed on the notice: pay or arrange by then. This is the cheapest moment to act |
| CP14, then CP501 / CP503 | The first bill and the reminder bills for the unpaid assessment | No enforcement yet, but interest plus the 0.5%/month penalty accrue |
| CP504 | Intent to levy under IRC §6331(d) | State tax refund can be seized; despite the name, not the final notice |
| LT11 / Letter 1058 | Final Notice of Intent to Levy | 30 days to request a Collection Due Process hearing (Form 12153) before the IRS can levy bank accounts or wages; a bank levy holds funds 21 days before they are sent |
None of this needs a person to touch your file. The practical point cuts both ways: act early if the 290 is right, and start the paper trail early if it is wrong, because a correction takes longer than an escalation does.
A code 290 just added tax you didn't expect?
Send us your transcript. An experienced tax professional will confirm whether the assessment is even correct, then map the cheapest way to resolve it while the interest on it is still small. Free, confidential, no pressure.
How do you dispute a code 290 assessment that is wrong?
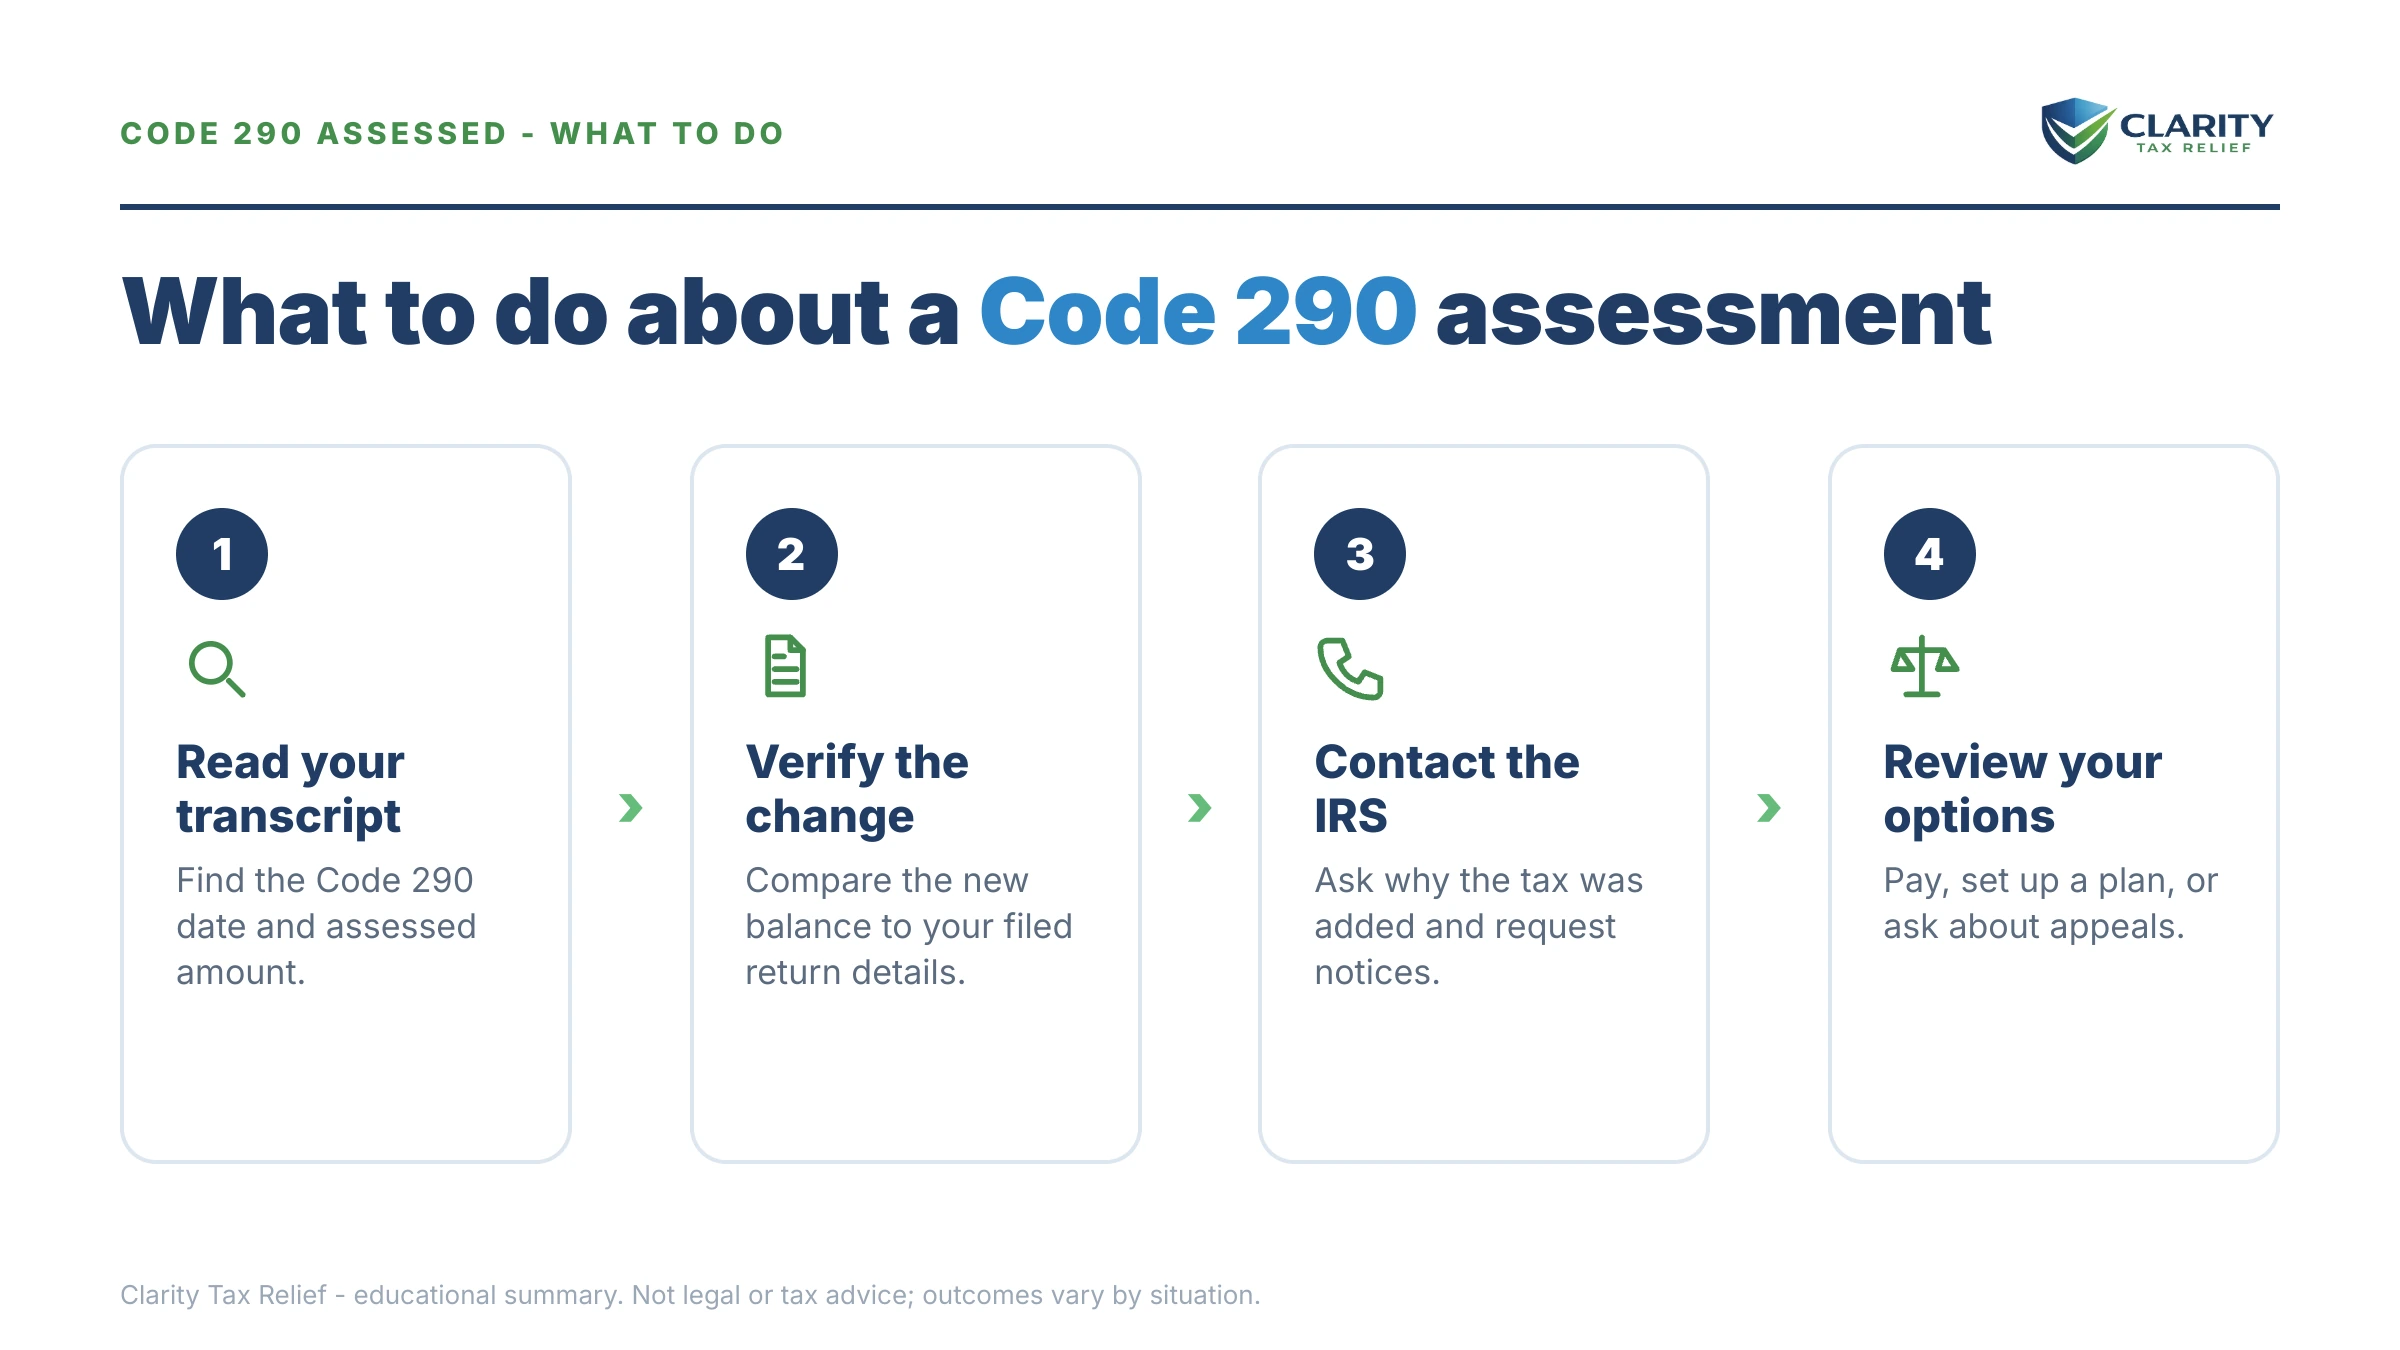
Clarity Tax Relief sorts a disputed 290 by how it was assessed before picking a route. The route depends on how it was assessed, and the codes around the 290 tell you which. A CP2000-based 290 (after a 922) can be reopened through underreporter reconsideration if you can document that the matched income was already reported, was nontaxable, or belongs to someone else. An exam-based 290 (after a 420 or 424) goes through audit reconsideration. A plain error, wrong year, doubled income, missed cost basis, is fixed with Form 1040-X. A win posts as code 291 reducing the balance, and the related interest and penalty come off with it. Keep making arrangements on the balance while you dispute; interest does not pause for a pending reconsideration.
Say a joint return left off one spouse's consulting 1099, the CP2000 went unanswered during a move. The transcript now shows a 290 for $22,000 of tax plus a 20% accuracy-related penalty of $4,400 and about $1,100 of interest, $27,500 in all. Both spouses owe the full amount. Before agreeing to any of it, check the return: if $8,000 of that 1099 income was actually reported on a Schedule C under the business name, reconsideration with the matching records takes the tax on it, the penalty on that tax and the related interest off the account with a code 291. That is the anatomy of most 290 cases we see: part payable, part disputable.
What are your options when code 290 adds tax you can't pay?
- Pay in full. Stops interest and penalty accrual immediately. If you can raise the money within six months, a short-term plan (up to 180 days, $0 setup fee, available when you owe under $100,000 in combined tax, penalties and interest) buys the time without a formal agreement.
- Monthly installment agreement. Balances of $50,000 or less in combined tax, penalties and interest qualify for an online long-term agreement without financial statements; the setup fee is $29 by direct debit or $69 otherwise. Interest and the failure-to-pay penalty continue while you pay (the penalty rate drops to 0.25% a month on an approved plan), so faster is cheaper. Run your own numbers in the IRS payment plan calculator to see what a monthly amount does to the total. On the $27,500 example above, $27,500 ÷ 72 is about $382 a month as a base figure, and paying $500 to $600 a month retires it years sooner. Here is how to set up an IRS payment plan online.
- Penalty relief. If the 290 dragged failure-to-pay penalties with it and your prior three years are clean, first-time penalty abatement can remove qualifying penalties. The accuracy-related penalty is not covered by it and has to be contested on reasonable cause. Estimate what penalties and interest are adding with the IRS penalty & interest calculator.
- Hardship. If paying anything would leave you unable to cover basic living expenses, Currently Not Collectible status pauses collection while the debt and interest remain. An Offer in Compromise is means-tested and fits only when your income and assets cannot cover the debt before the CSED.
How to respond to a code 290, step by step
- Read the amount. A $0.00 290 closed a review with no tax added. A dollar amount is a new assessment, with interest running from the date beside it.
- Read the codes around it. A 922 earlier means a CP2000 case; a 420 or 424 means an exam; a 976 or 977 means your own amended return; a 971 marks the letter that explains it.
- Match the 971 date to the letter in your mail. The pay-by or petition date printed on that notice is the one that controls.
- Compare the assessment to your return and your W-2s and 1099s. If the matched income was already reported, nontaxable, or someone else's, start underreporter reconsideration, audit reconsideration, or Form 1040-X, depending on how it was assessed.
- Arrange the balance while any dispute runs. Pay in full, take a short-term plan, or set up an installment agreement. Interest does not pause for a pending reconsideration.
- Watch for a 291. A successful dispute posts as code 291, with the related 197 and 277 taking the interest and penalty off.
Common code 290 mistakes
- Panicking over a future date. A 290's date routinely sits one to three weeks ahead of the day it appears. It is the effective assessment date, not a deadline you missed.
- Treating a $0.00 290 as a bill. It is a closing entry, and if a refund was on hold it is often the line right before the 846.
- Absorbing a wrong assessment. Part payable, part disputable is the usual shape. A win posts as a 291.
- Pausing payments during a dispute. Interest and the 0.5%-per-month penalty keep accruing while reconsideration is pending, and the penalty rises to 1% per month if you do not pay within 10 days of a notice of intent to levy.
Can you handle a code 290 yourself, or does help change the outcome?
Clarity Tax Relief will tell you when a 290 needs no help at all, and plenty of them don't. One number is worth having before anyone pitches you a settlement: Clarity Tax Relief's analysis of the 2025 IRS Data Book found the IRS accepted 5,464 of 38,797 offers in compromise in fiscal 2025, about 1 in 7 (see the full breakdown). A $0.00 290 requires nothing from you; it is the IRS closing its own file. A dollar-amount 290 you recognize and agree with, your own amended return posting or 1099 income you forgot, paired with a balance you can pay within 180 days or cover on a simple online plan, is a do-it-yourself fix, and so is a first-time abatement request on a clean three-year history.
Experienced help changes the outcome in a narrower set of cases: you do not recognize the income behind the assessment, the 290 sits on top of multiple unresolved years, exam codes and appeal deadlines are in play, the assessment traces to a spouse's hidden income on a joint return, or a CP504 or LT11 has already arrived and the dispute has to run alongside a levy defense. In those cases the order of operations, dispute, then penalties, then payment terms, determines what you ultimately pay. If a dispute stalls and it is causing hardship, the Taxpayer Advocate Service is a free, independent escalation path inside the IRS.
Terms on your transcript, decoded
- Transaction code: the three-digit number that identifies each entry on an account transcript. 150 is the return, 290 is additional tax assessed, 291 is tax reduced, 971 is a notice issued.
- Assessment date: the date beside the 290. Interest is computed to it and the collection statute runs from it.
- CSED: Collection Statute Expiration Date, generally 10 years after each assessment, pausable by offers, bankruptcy and appeals.
- Cycle date: the weekly IRS processing batch a transaction posted in, which is why 290 dates often sit a couple of weeks in the future.
Code 290 questions, answered
What does code 290 mean on an IRS transcript?
Code 290 on an IRS transcript means "Additional Tax Assessed." With a dollar amount, the IRS added tax to your account, usually after a CP2000, an audit, or an amended return. With $0.00, no tax was added; the IRS closed a review or released a hold. The date beside it is the assessment date.
What does "additional tax assessed" mean if the amount is $0.00?
It means a review closed with nothing added. The IRS needed a formal transaction to end a refund hold, an underreporter screen or an identity check, and a $0.00 code 290 is that transaction. If a refund was frozen behind a code 570, watch for code 846 in the following weekly updates. The one exception: a $0.00 290 paired with a 971 means an explanation letter is coming, so read it when it arrives.
Is code 290 on a transcript bad, and does it mean an audit?
A $0.00 code 290 is neutral to good news: the IRS reviewed something and changed nothing. A code 290 with a dollar amount is a new balance that is already accruing interest from the date beside it, and a notice with a pay-by date will follow. It is not an audit indicator; a full examination shows as code 420 or 424, and most dollar-amount 290s come from a CP2000 mismatch, a math-error correction or an amended return.
Why does my code 290 have a future date?
Transcript dates run on the IRS's weekly processing cycles, so the date beside a 290 is often one to three weeks ahead of the day you first see the entry. That date is the official assessment date: interest is computed to it, and the balance becomes legally collectible on it. It is not a deadline for you; the deadline that matters is the pay-by date on the notice that follows.
How long after code 290 will I get my refund?
If the 290 is $0.00 and it closed the hold on your refund, look for code 846, refund issued, on the next weekly updates; the date beside the 846 is the date the refund is sent. The IRS publishes no day count between the two entries, and in practice the 846 tends to post within a cycle or two. A 290 with a dollar amount is applied against the refund first, and only the remainder, if any, is issued.
What codes usually appear with code 290?
Code 196 (interest assessed) and 276 (failure-to-pay penalty) post alongside a dollar-amount 290. Code 971 marks the notice that explains it. A 922 before the 290 means a CP2000 case; a 420 or 424 means an exam; a 976 or 977 means an amended return. Code 291 after it means part of the assessment was abated, and code 846 after a $0.00 290 is the refund going out.
Can I dispute a code 290 assessment?
Yes, and the route depends on how it was assessed. A CP2000 assessment can be reopened through underreporter reconsideration with documents proving the income was reported or nontaxable; an audit assessment goes through audit reconsideration; a plain error can be fixed with an amended return. A successful challenge posts to your transcript as code 291, tax reduced. Keep making arrangements on the balance while you dispute, because interest does not pause.
How long does the IRS have to collect a code 290 assessment?
Generally 10 years from the assessment date printed beside the 290, which is a separate clock from the one on your original code 150 tax. A 290 assessed in 2026 on a 2022 return is collectible until about 2036, and events like an Offer in Compromise, bankruptcy, or a Collection Due Process appeal pause the clock and push the date out. Our CSED calculator estimates the expiration date for each assessment on your transcript.
What notice comes after code 290 posts?
Look for a code 971 entry near the 290; that is the notice going out. If the IRS changed your return, expect a CP21A or CP22A explaining the adjustment and showing a pay-by date. If the 290 finalizes a CP2000 you did not answer, a CP3219A Statutory Notice of Deficiency came first. If nothing is paid by the notice date, the standard balance-due sequence (CP14, CP501, CP503, CP504, LT11) follows.
The bottom line on code 290
Code 290 is the IRS making an assessment official. For $0.00 it means a review closed with nothing added; with a dollar amount it is a new debt accruing interest from the date beside it, and the letter marked by the nearby 971 carries the deadline that counts. Read the companion codes to learn where it came from, dispute the part that is wrong through the matching route, and put the rest on a payment path before the notice sequence moves toward a levy.
Your next 24 hours
- Pin down the 290. On your transcript (pull a fresh one at IRS.gov Get Transcript), write down the 290's amount and date, and note any 971, 196 or 276 entries around it.
- Gather the paper. The IRS letter that matches the 971 date, your filed return for that year, and every W-2 and 1099 you received. That is everything needed to verify or dispute the assessment.
- Call the IRS only with a plan. If you need to reach the IRS about the notice, our 188-call hold-time study shows which hours get answered fastest.
- Get it reviewed free. Interest on a 290 accrues daily from the assessment date, so the balance only moves one direction while you wait. Use the 2-minute form or call (888) 825-7779 and an experienced tax professional will tell you whether yours is a pay-it, plan-it, or fight-it case.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.