
Refund Offsets & Hardship Relief
Offset Bypass Refund: How to Get One Approved (2026)
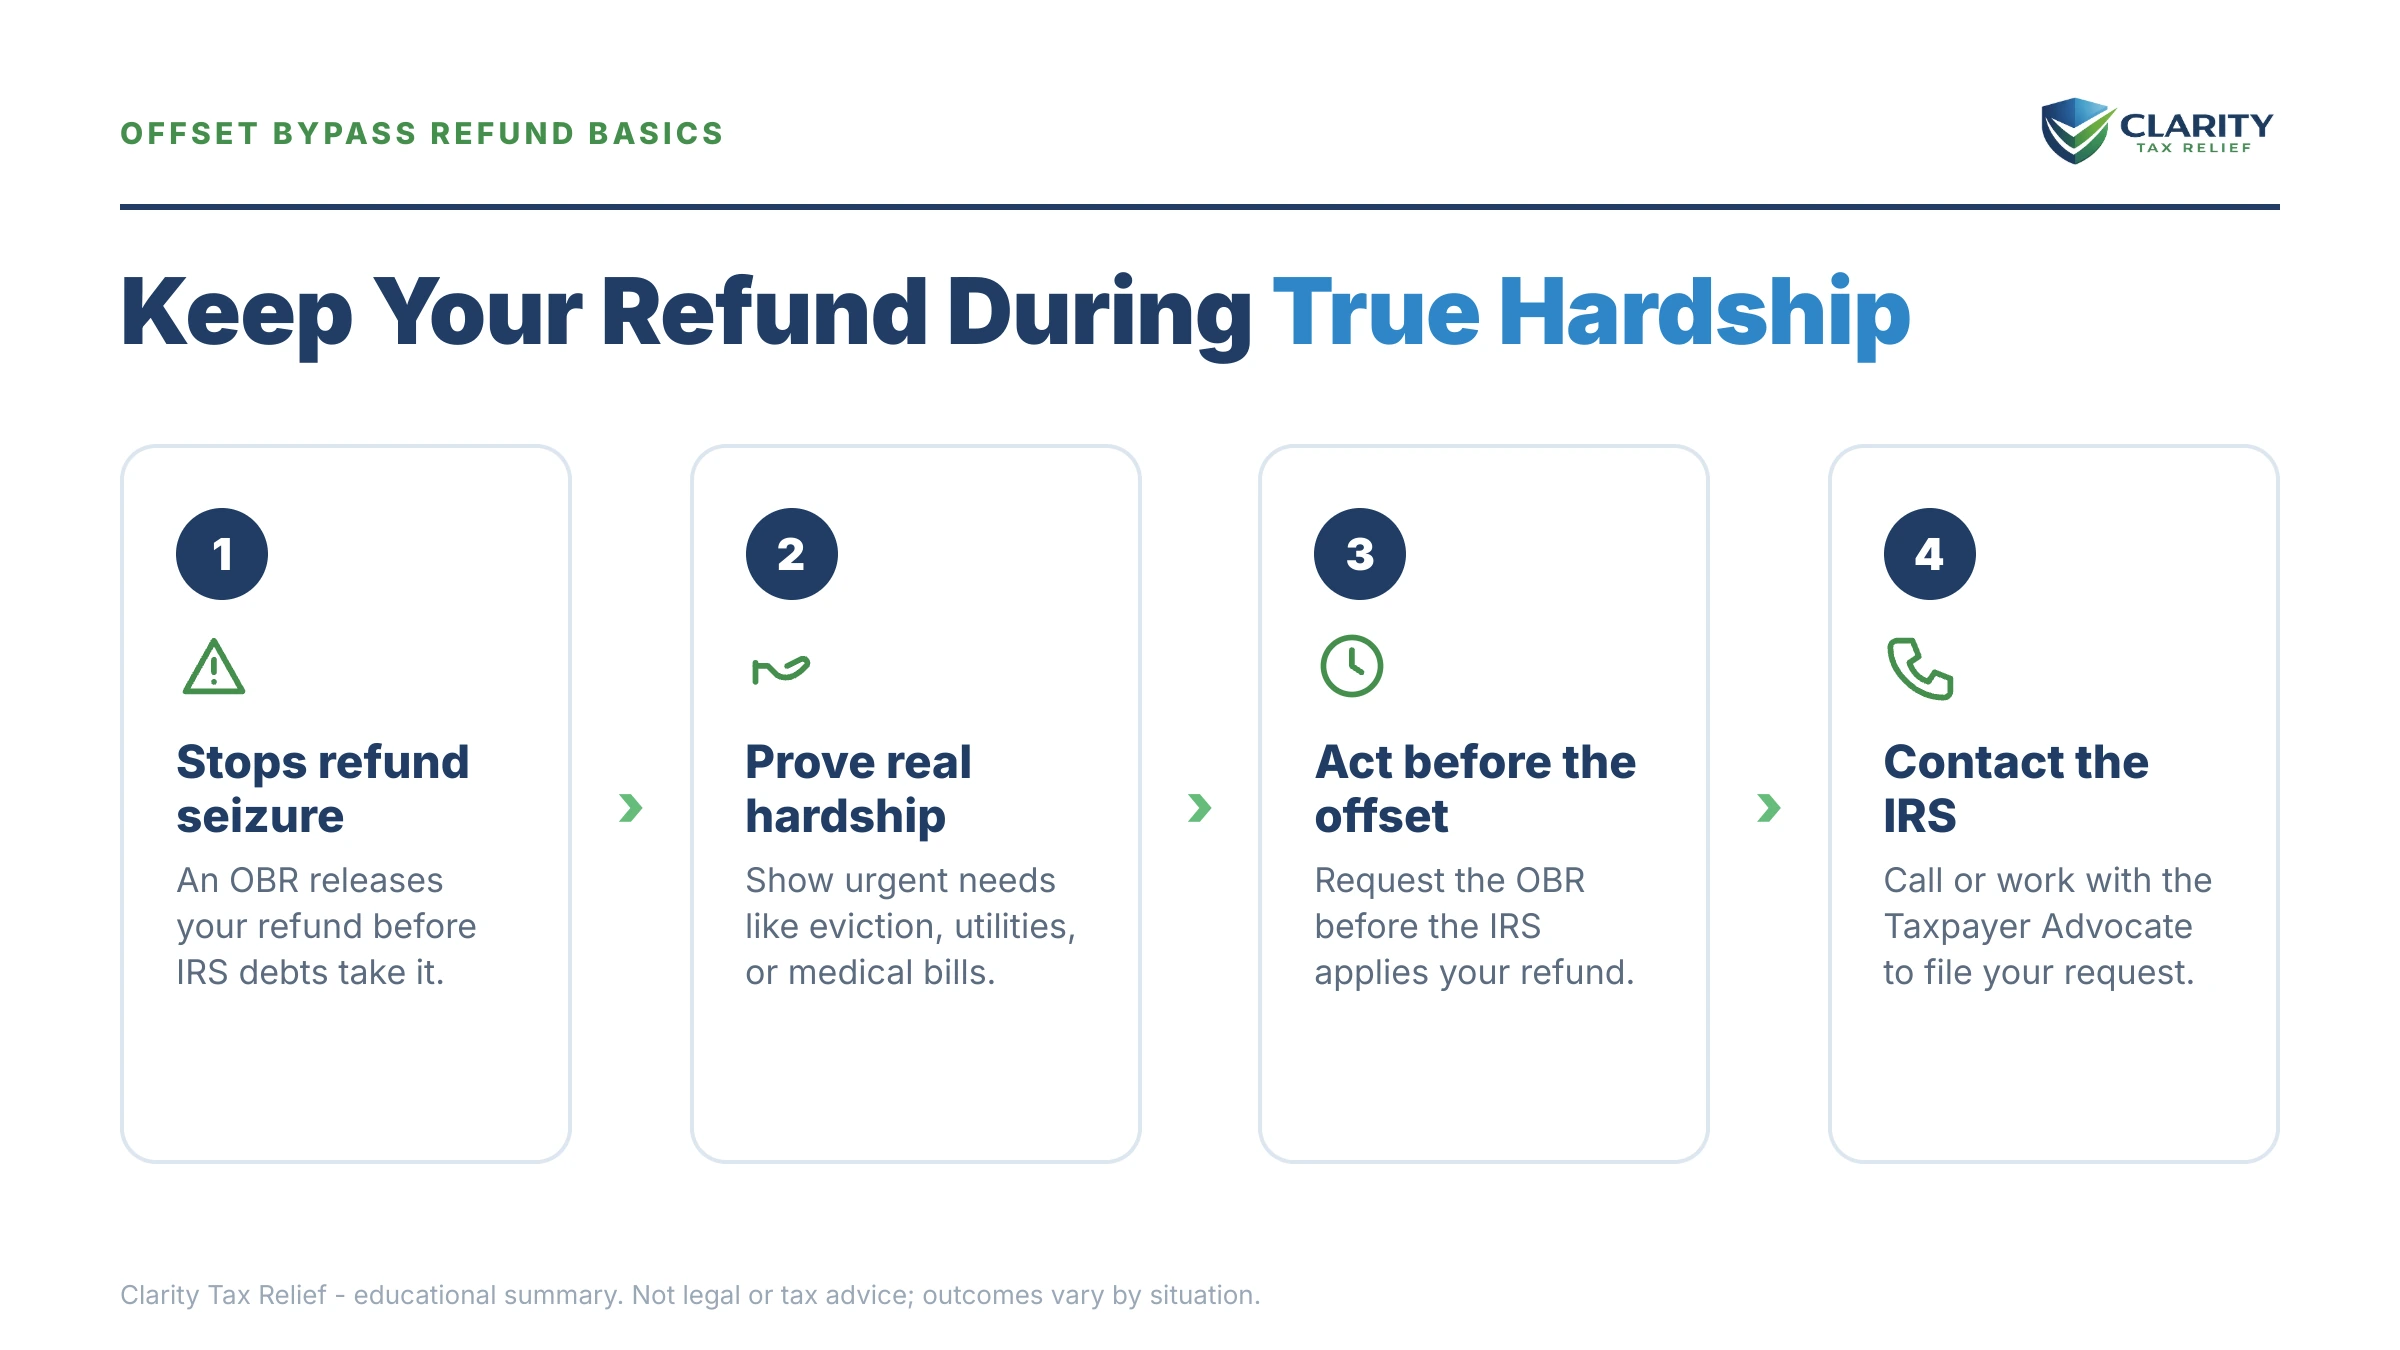
The short answer: an offset bypass refund (OBR) is a manual refund the IRS can issue when applying your refund to your own back taxes would leave you unable to pay basic living expenses. There is no form. You request it by phone, or through the Taxpayer Advocate Service, before the refund is applied to your balance. It never applies to child support, student loan or other Treasury Offset Program debts. Clarity Tax Relief makes the request the week the return is filed, before the assessment date.
This guide covers the offset bypass refund: what it is in the IRS's own words, which offsets it can and cannot bypass, the timing rule that decides whether a request is even possible, the hardship proof that moves a request from denied to issued, and what is left to do when the refund has already been applied. You owe the IRS, a refund is finally coming, and you already know what happens next. The IRS keeps it, while the pay-or-quit notice on your counter gives you days. An offset bypass refund is the one narrow exception written into the IRS's own procedures (Internal Revenue Manual 21.4.6.5.7.1, revised May 7, 2026), and almost nobody at the IRS will volunteer that it exists.
Three facts define this remedy. It has no form. It only works against your own federal tax debt, never child support or student loans. And it dies the moment your refund is applied to your balance, which makes it one of the most time-sensitive requests in tax resolution. Read straight through if the term is new to you. If you already know you qualify and the return is about to post, skip to the step-by-step table and the hardship proof section.
⏱ Your real deadline: the assessment date of your return, which the IRS calls the 23C date. That is when the overpayment is created and the offset happens, with no advance notice. The IRS says most e-filed refunds arrive within about three weeks of filing, so the safest time to request an OBR is before you file or the same week you do.
What is an offset bypass refund?
The Internal Revenue Manual puts it plainly: under certain hardship circumstances, the IRS may issue a manual refund of excess credits without first satisfying the taxpayer's outstanding balance. That manual refund is the offset bypass refund. Hardship for this purpose means economic hardship within the meaning of IRC Section 6343, the same standard the IRS uses to release a levy, and it comes down to one question. Would losing the refund leave you unable to pay basic living expenses?
Two features of the IRM wording matter in practice. The IRS handles each OBR case by case, and it keeps no exclusive list of expenses that qualify. So the request is won or lost on specifics: a named expense, a dollar figure and a due date, backed by paper.
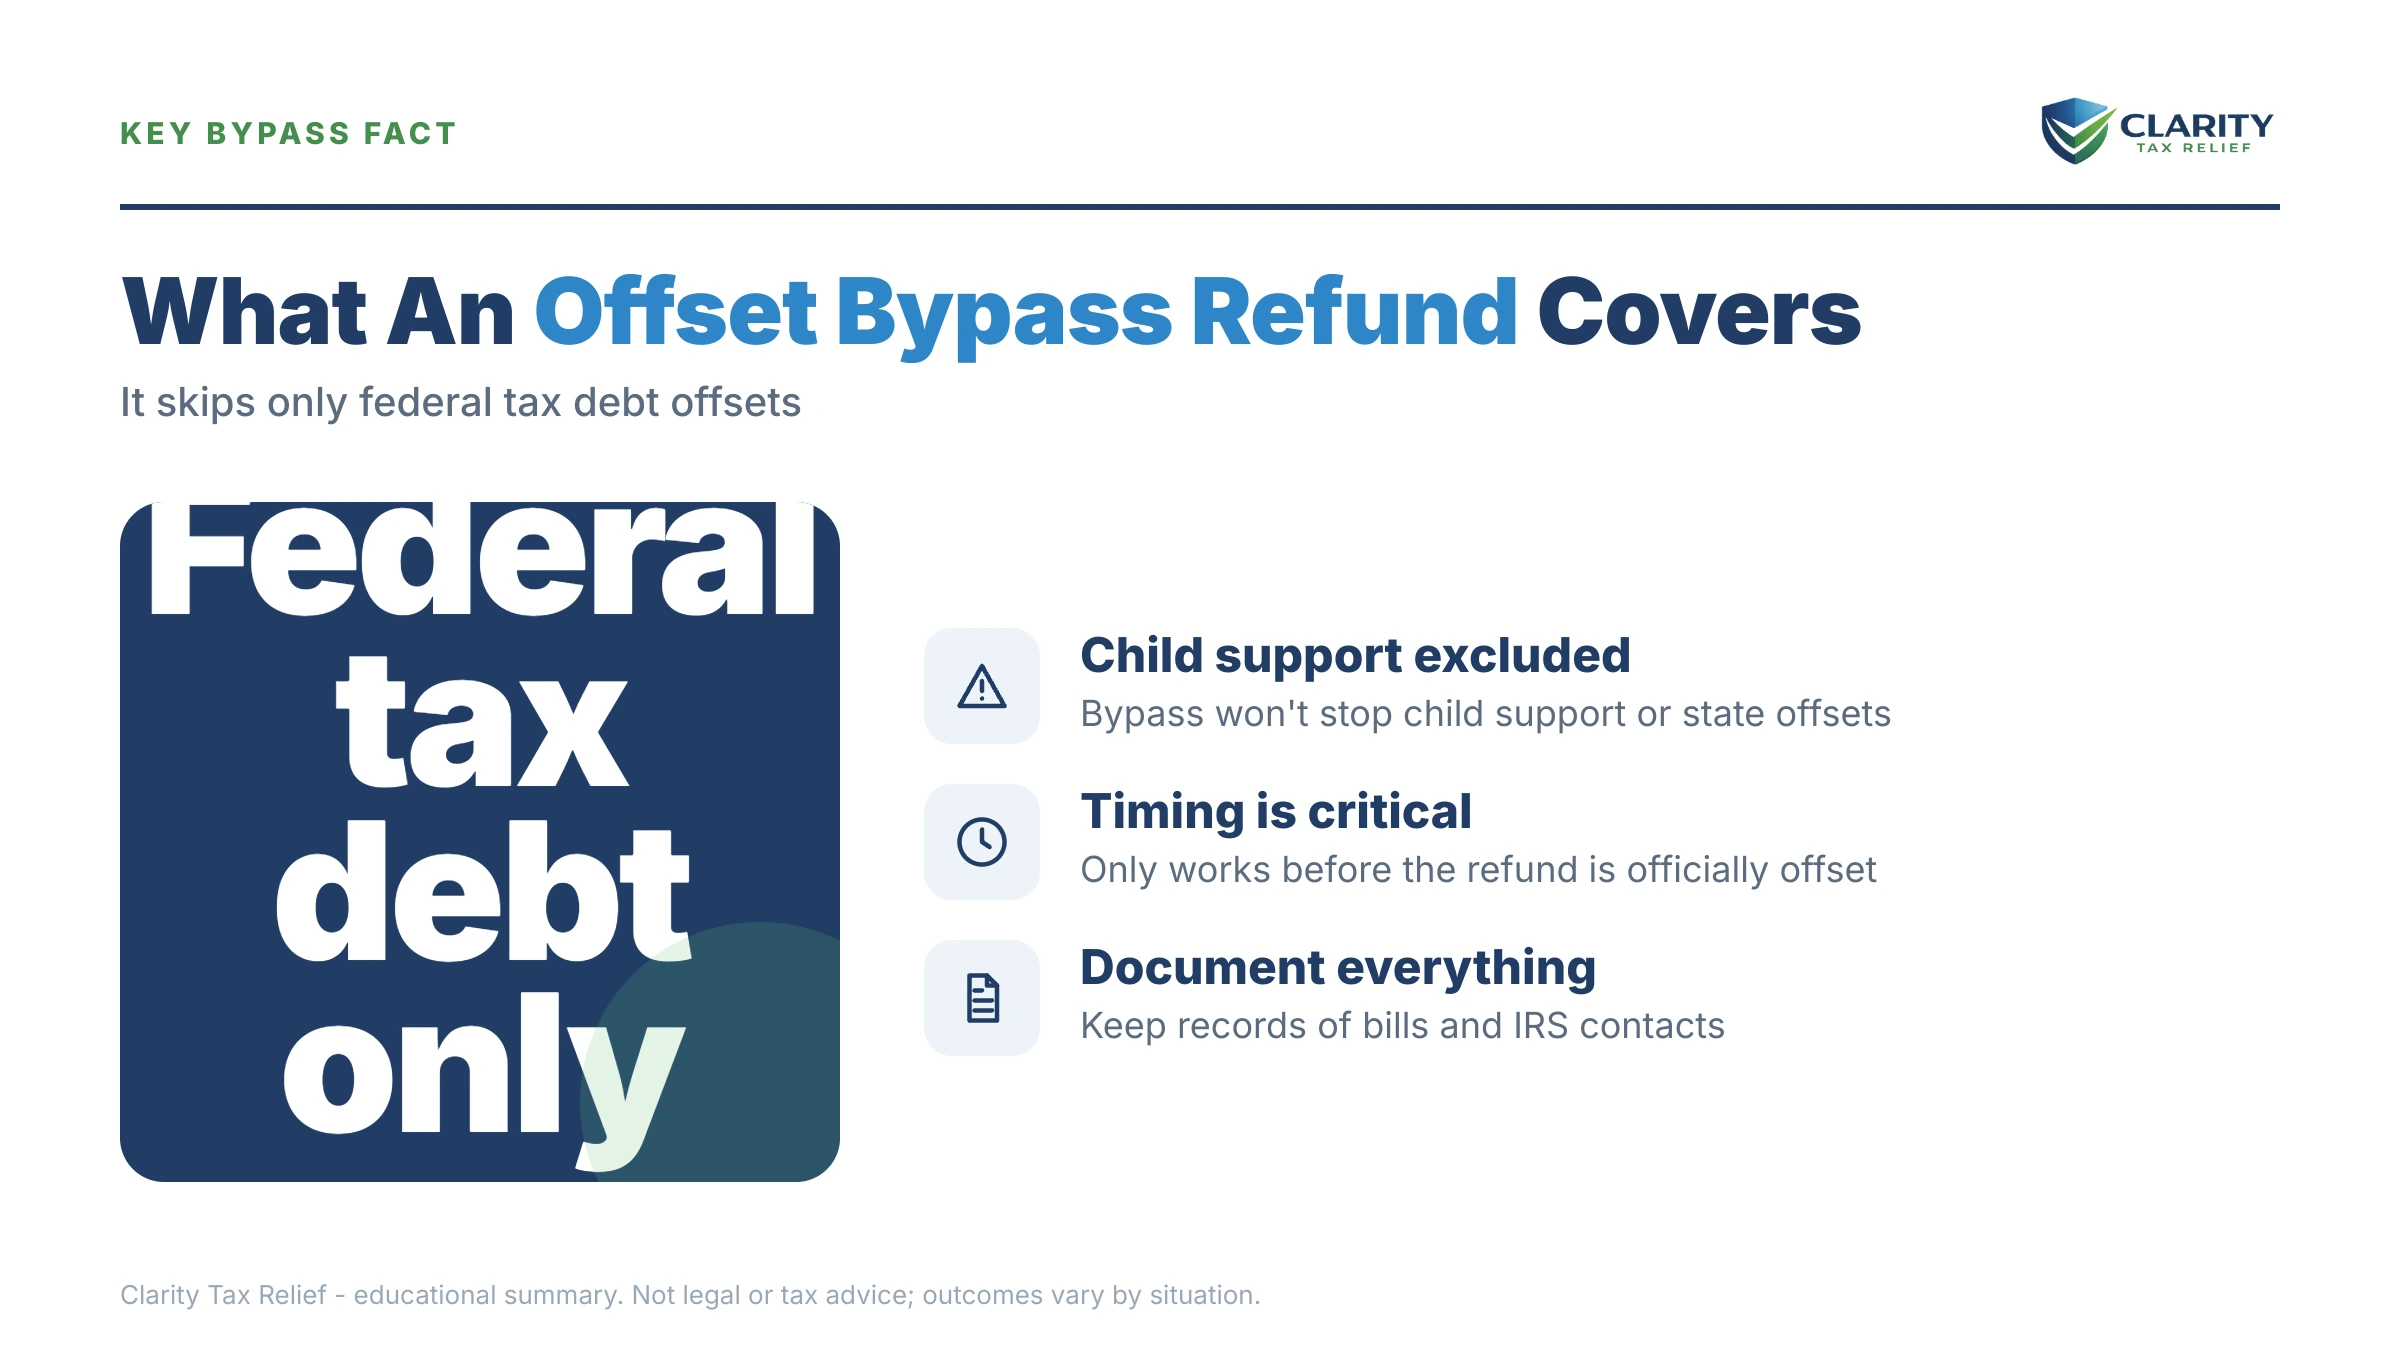
Your federal refund is applied to your back taxes automatically under IRC Section 6402(a). The statute says the IRS "may" apply an overpayment to your tax debt, and that word is where the discretion lives. The Treasury Offset Program, which takes refunds for child support, defaulted student loans and other non-tax debts, is a different system with no discretion in it. The IRM is blunt about that. If a TOP debt exists, the IRS has no authority to issue an OBR.
“Debt offsets are conducted by the Department of Treasury's Bureau of the Fiscal Service (BFS). The BFS issues IRS refunds and is authorized by Congress to conduct the Treasury Offset Program (TOP).”
, Reduced refund (IRS.gov)
Is there an offset bypass refund form?
Clarity Tax Relief handles an OBR as a phone or written request for that reason. No. The IRS publishes no form for an offset bypass refund, and the IRM procedure for one is built around a phone or correspondence request rather than a filing. You call the IRS at 800-829-1040, say you are requesting an offset bypass refund for economic hardship, and give the dollar amount you need. The employee is instructed to work the request immediately and to ask for documents that validate both the hardship and the specific amount.
The paperwork is on the IRS side. The employee prepares the manual refund voucher, notes the hardship, inputs a transaction code marking the offset as bypassed, and hand-carries the case to the office's Taxpayer Advocate liaison for review before Accounting issues the refund. If the liaison disagrees, the case goes to the Taxpayer Advocate Service for resolution. The only form you might file is Form 911, which opens a TAS case; our Form 911 walkthrough shows what to put in the hardship description.
Which offsets can an OBR bypass?
Before you spend a morning on hold, confirm whose debt is taking the refund. The IRM requires the IRS employee to call the Bureau of the Fiscal Service to check for a TOP debt before issuing any OBR, and a federal tax debt must not be bypassed if a TOP offset will occur. Pull your account transcript and call the TOP hotline yourself first so you know the answer before the IRS does.
| Situation | OBR available? | Why, per IRM 21.4.6.5.7.1 |
|---|---|---|
| Refund going to your own federal income tax balance, and you cannot pay rent, a utility bill or medical care without it | Yes | Federal tax offsets under IRC 6402(a) are discretionary; hardship under IRC 6343 is the test |
| You have a pending Offer in Compromise and the refund would otherwise be kept | Yes | The IRM says a pending offer freeze does not preclude an OBR, as long as the offset has not yet taken place |
| A later amended return, audit adjustment or credit transfer creates a new overpayment | Yes | Subsequent adjustments can produce an overpayment that is eligible for an OBR |
| Refund going to past-due child support, a federal student loan, state income tax or state unemployment debt | No | Treasury Offset Program debts are mandatory; the IRS has no authority to issue an OBR when a TOP debt exists |
| You have both a federal tax debt and a TOP debt, and your refund is larger than both combined | Partly | Only the amount above both debts can be refunded manually; the rest offsets to the tax debt first, then the agency debt |
| You want the refund for ordinary bills with no immediate consequence | No | Economic hardship means an inability to pay basic, necessary living expenses; wanting to keep the money does not meet that test |
| The refund already offset and your CP49 notice arrived more than 30 days ago | No, unless IRS clerical error | After the overpayment is applied there is nothing left to refund; a clerical error by the IRS is the only route to a reversal |
When do you request an OBR?
The deadline is the assessment date of your return, which the IRS calls the 23C date and which always falls on a Monday. Once the tax is assessed the overpayment is created and the offset happens in the same breath. The IRM states that after that point there is no overpayment left to refund and an OBR cannot be initiated. The manual refund paperwork must reach IRS Accounting by the Friday cutoff before that Monday, so the real window is the processing period between filing and assessment.
“The deadline is the assessment date, the 23C date, and it always falls on a Monday. After that the refund is applied and the request is too late,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
Three exceptions exist, and they are narrow. If a freeze code is holding the overpayment on your account, the money is still available and an OBR can be issued after the 23C date, provided the request is received and approved before the freeze is released. If you asked in time and an IRS clerical error stopped the request from being processed, the IRS can reverse the offset and issue the refund. And if a later adjustment such as an amended return creates a new overpayment, that overpayment can be refunded as an OBR. Outside those three, an employee who finds you more than 30 days past the 23C date is told to inform you the overpayment has been applied and the IRS cannot undo it.
Check your own account before you call. Our IRS transcript codes guide shows how to read the account transcript. No code 826 or code 898 yet means the money has not moved and your window is still open.
What happens if you do nothing?
If you do nothing, the IRS applies your entire refund to your oldest balance and tells you about it only after the money is gone. There is no pre-offset notice for a federal tax offset, so the sequence runs silently:
- You file your return showing an overpayment. The IRS processes it normally, and Where's My Refund may even show progress.
- The offset posts internally. Transcript code 826 appears on your account, meaning the overpayment moved to another tax year. (An offset to a non-tax debt posts as code 898 instead, a signal an OBR was never possible.)
- A CP49 notice arrives by mail confirming the refund was applied to back taxes. By the time you are reading it, the OBR window has closed. See our CP49 refund applied guide for what that notice means.
- The hardship goes unfunded. The eviction, shutoff or medical bill you needed the refund for is still due. The applied refund cannot be clawed back except in the clerical-error case above.
- It repeats every filing season until the underlying balance is resolved. Offset is annual and automatic, even for accounts in hardship status.
Reaching a person is the slow part. The automated offset runs on schedule regardless of how long the phone queue is, which is why the request has to start the week you file. Our study of 188 IRS calls shows which hours get through fastest.
Refund about to be offset, and you need that money to keep the lights on?
An offset bypass refund only works before your refund is applied to your balance, and most e-filed refunds move in about three weeks. Get your situation reviewed free today so the request lands while the window is still open. Call (888) 825-7779 or use the 2-minute form.
How to complete an offset bypass refund, step by step
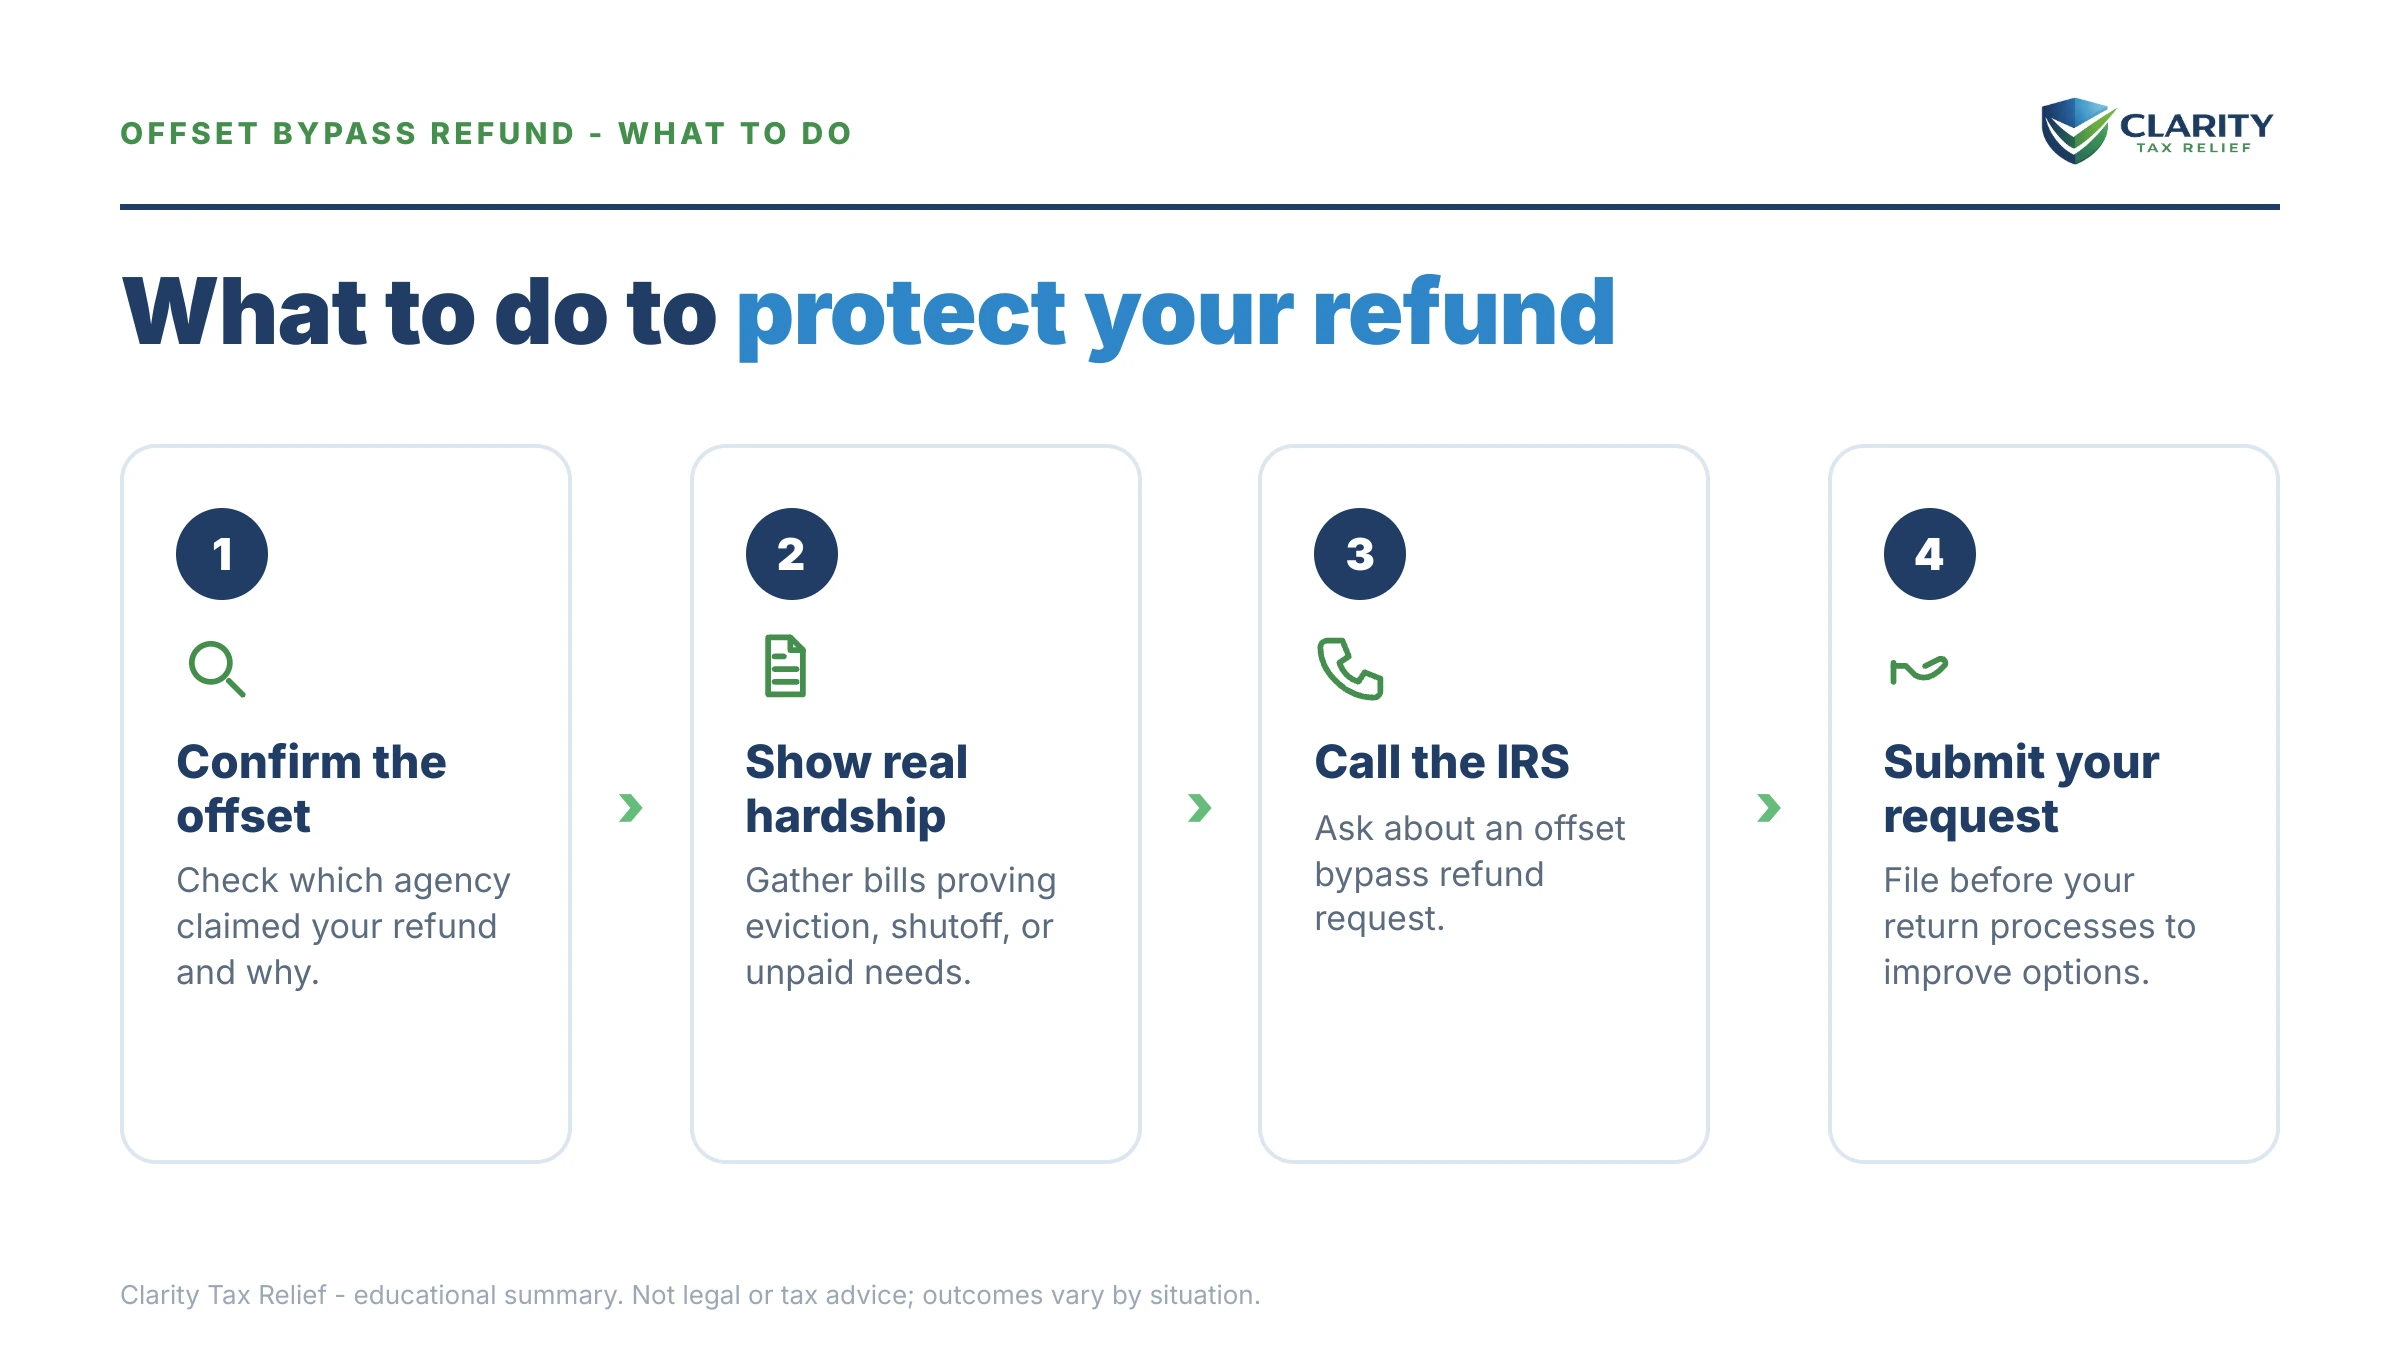
The request succeeds on three things: it reaches the IRS before the assessment date, it names a specific dollar amount, and the paper behind that amount arrives the same day. Here is the sequence, with the timing for each step.
| Step | What to do | When |
|---|---|---|
| 1. Confirm the debt type | Call the Treasury Offset Program hotline at 800-304-3107 and pull your IRS account transcript. If a TOP debt (child support, student loan, state tax) exists, an OBR is off the table and your dispute goes to that agency. | Before you file, or the day you do |
| 2. Gather the hardship proof | Eviction or foreclosure notice, utility disconnection notice, medical bill or provider letter, with the amount due and the due date on it. Write down the single dollar figure you will request. | Same day as step 1 |
| 3. File the return | E-file if you can. The IRS says most e-filed refunds arrive within about three weeks, and paper returns take six weeks or more, so the window is short either way. | Day 0 |
| 4. Call the IRS and request the OBR | Call 800-829-1040, ask for an offset bypass refund for economic hardship, state the amount, and fax or upload the documents the same day. The IRM tells the employee to work the request immediately. | Day 0 to day 3, before the 23C date |
| 5. Escalate to TAS if it stalls | If the IRS cannot resolve the request within 24 hours and the refund has not posted, ask for a Taxpayer Advocate Service referral, or call TAS at 877-777-4778 or file Form 911. | Within 24 hours of step 4 |
| 6. Follow up until the refund issues | Ask for the approved amount and how it will be paid. Watch the transcript; a manual refund posts as code 840 rather than the usual code 846. | Daily until the money arrives |
| 7. Fix the underlying balance | Set up an installment agreement, request currently not collectible status, or evaluate an Offer in Compromise. Offsets repeat every year until the debt itself is resolved. | After the refund, before next filing season |
A note on the TAS route, because the advice online gets it backwards. The IRM says OBR requests should generally not be referred to the Taxpayer Advocate Service, and that the IRS itself must work them immediately. TAS comes in when you ask for it or meet its economic-burden criteria, the request cannot be resolved within 24 hours, and the 23C date has not passed (or a clerical error stopped the IRS from processing a timely request). So call the main line first, then use TAS as the escalation, and do both inside the same week.
What hardship proof does the IRS accept?
Clarity Tax Relief ties the requested amount to a dated bill. The OBR is issued for the dollar amount you document, and the IRM instructs employees not to exceed the amount of the hardship request. Your evidence sets your ceiling. Vague statements about being broke get nothing released. A dated notice with a dollar figure on it gets that dollar figure considered.
| Hardship type | Documentation to gather | What it establishes |
|---|---|---|
| Eviction or foreclosure | Landlord's pay-or-quit notice, foreclosure letter, past-due amount and deadline | The exact dollar amount needed to keep your housing, and by when |
| Utility shutoff | Disconnection notice with account number, balance, and cutoff date | An essential service ends on a specific date without a specific payment |
| Medical necessity | Bills, prescription costs, or a provider letter tying treatment to payment | Care you or a dependent will lose access to without the funds |
| Vehicle needed for work | Repair estimate plus proof the vehicle produces your income (common for 1099 drivers and contractors) | The offset would cut off your ability to earn at all |
How much will the IRS release?
The IRM's own illustration is worth reading closely because it shows how the math is done. A taxpayer has a $1,000 overpayment, requests a $600 hardship refund to avoid eviction, and owes $500 for a prior year. If the request is honored, the taxpayer receives $600. Of that, $100 is treated as the OBR (the part that would otherwise have offset) and the remaining $400 of the overpayment is applied to the tax debt. The refund is the hardship amount, never the whole overpayment.
Now a case closer to what we see. Say you are a 1099 contractor who owes the IRS $76,400 across three years of unpaid self-employment tax. This year you finally overpaid: your fourth-quarter estimated payment plus a refundable credit produced a $4,900 overpayment. Then your landlord posted a pay-or-quit notice, $2,300 past due, ten days to cure.
Without an OBR the math is automatic. The full $4,900 offsets, your balance drops from $76,400 to $71,500, and you are facing eviction with nothing in hand. The IRS treats the offset as a payment. The eviction is not its problem.
With a timely request backed by the pay-or-quit notice, the IRS can release up to $2,300, the documented hardship amount, as an actual refund to you. The remaining $2,600 still offsets, so the balance falls from $76,400 to $73,800. You do not keep the whole refund. You keep the roof.
Two side notes for this contractor. At $76,400 the debt sits above the $66,000 threshold the IRS uses in 2026 to certify seriously delinquent tax debt to the State Department for passport action, so this account has bigger exposure than a lost refund. And hardship status is available to the self-employed, although the financial test works differently when your income is business income.
What are your options when a refund offset would cause hardship?
An offset bypass refund is the only remedy that releases refund money the IRS would otherwise keep for your own tax debt. It is the wrong tool for every other kind of offset. Which remedy applies depends on whose debt is taking the refund and what kind of debt it is:
| Your situation | The right remedy | Key eligibility rule |
|---|---|---|
| Refund going to your own federal tax debt, and you face an immediate hardship | Offset bypass refund (OBR) | No form; request by phone or via TAS before the refund posts; release capped at the documented hardship amount |
| Joint refund taken for your spouse's separate debt | Injured spouse, Form 8379 | You must have your own income, withholding or credits on the joint return; recovers only your share |
| Refund taken for child support, student loans or state debt | Dispute with the agency that certified the debt | OBR cannot bypass Treasury Offset Program debts; the IRS has no discretion over them |
| Ongoing inability to pay basic living expenses, beyond this one refund | Currently Not Collectible status | Financial-statement test on Form 433-F; note that offsets continue even in CNC |
| IRS levy (wages or bank account) causing hardship, not a refund offset | IRC 6343 hardship levy release | Applies to active levies only; a refund offset is not a levy and follows the OBR path instead |
If your deeper problem is that you cannot pay the IRS at all, the durable fix runs through hardship status or a payment plan. The IRS hardship program overview explains what CNC status does and does not protect. The one-sentence version for this page: CNC stops levies, and it does not stop refund offsets, which is why the OBR exists as a separate remedy.
Cost and speed differ sharply across these paths, and speed is usually what decides it:
| Option | Cost | Typical timeline |
|---|---|---|
| Offset bypass refund | Free | Must be requested and worked before the assessment date, so days rather than months; the released portion is then paid to you as a manual refund |
| Injured spouse (Form 8379) | Free | About 11 weeks if e-filed with the joint return, 14 weeks on paper, or about 8 weeks if filed by itself after the return has processed, per the IRS instructions |
| TAS case (Form 911) | Free | Varies; economic-burden cases are prioritized, and the IRM routes a stalled OBR to TAS when the IRS cannot resolve it within 24 hours |
| Currently Not Collectible | Free (financial disclosure required) | Weeks to set up; protects wages and bank accounts going forward but never the refund |
What can you do if it is too late?
The CP49 notice has arrived, code 826 is on the transcript, and the money is gone. In most cases the IRS cannot undo that, and an employee who finds you more than 30 days past the assessment date is instructed to say so. Four things are still worth doing.
First, if you did call before the assessment date and nothing happened, say so and ask the IRS to check for a clerical error. The IRM lets the IRS reverse an offset and issue the OBR when its own bookkeeping, ministerial or inadvertent mistake prevented a timely request from being processed, and TAS can take the case if the IRS will not. Second, if the refund was a joint one and the debt belongs only to your spouse, Form 8379 can be filed after the offset.
Third, if you later amend the return or the IRS adjusts it and a new overpayment appears, that overpayment can be requested as an OBR; ask before it posts. Fourth, and most important, fix the balance so next year's refund survives. Run the numbers on our IRS payment plan calculator to see what a monthly agreement would look like, read how the IRS Fresh Start program options fit together, or find out whether an Offer in Compromise is realistic on your income.
Red flags that sink an OBR request
Most denied requests fail on one of these. Check them before you call, because each one is cheaper to fix in advance than to argue about afterward.
- A TOP debt on the account. Child support, a federal student loan, state income tax or state unemployment debt makes an OBR impossible. The IRS employee must check with the Bureau of the Fiscal Service before issuing one, so check first yourself at 800-304-3107.
- Code 826 or 898 already on the transcript. The money has moved. Outside a clerical error, a freeze code or a later adjustment, there is nothing left to refund.
- No dollar figure. The IRM caps the release at the amount you document. "I need my refund" releases nothing; a pay-or-quit notice for $2,300 is a request for $2,300.
- Proof that arrives later. The documents validating the hardship and the amount need to be faxed or uploaded the same day you call, because the employee is told to work the request immediately.
- Ordinary bills with no immediate consequence. Economic hardship means an inability to pay basic, necessary living expenses. Wanting to keep the money does not meet that test.
- Going to TAS first. The IRM says the IRS itself must work the request. TAS is the escalation when it stalls past 24 hours, so call the main line first and use both inside the same week.
- Waiting for a notice. There is no pre-offset notice for a federal tax offset. The CP49 arrives after the money is gone.
Can you request an OBR yourself?
Clarity Tax Relief tells clients they can make this request on their own. Yes. The IRS requires no representative, and the request costs nothing. If your situation is a single tax year owed, a clean filing record, one clear hardship document and time before you file, a patient morning on the phone (or a Form 911 to TAS) is a reasonable plan.
Experienced help earns its keep when the clock or the file is against you. The return is already filed and the refund could post any day. The hardship spans several categories and needs to be packaged to support a larger release. Or the real problem is the $76,400 behind the offset, where sequencing an OBR now with an installment agreement, CNC request or settlement analysis afterward determines what the next several years cost. In those cases a tax professional is making sure a one-shot request lands right the first time, and then dealing with the balance that caused it. Our pricing page explains what that work costs up front.
Terms in the offset process, decoded
- Offset: the IRS or Treasury applying your refund to a debt during processing. Administrative, automatic, and not a levy.
- Offset bypass refund (OBR): the IRS's discretionary manual refund of the hardship portion of an overpayment that would otherwise offset to your federal tax debt.
- 23C date: the assessment date of your return, always a Monday. The overpayment is created and offset on that date, and the OBR paperwork must reach Accounting by the Friday before it.
- IRC Section 6402(a): the statute saying the IRS may apply overpayments to your tax debts. The word "may" is where OBR discretion lives.
- Treasury Offset Program (TOP): the separate, mandatory system that takes refunds for child support, student loans and state debts. No bypass exists for it.
- Code 826 / Code 898 / Code 840: transcript codes showing your refund moved to another tax year (826), to a non-tax agency debt (898), or was issued as a manual refund (840), which is how an approved OBR posts.
- Economic hardship: the inability to pay basic, necessary living expenses, as defined under IRC Section 6343 for levy releases.
The bottom line on an offset bypass refund
An offset bypass refund is a phone request, made the week you file, for a specific dollar amount backed by a dated notice. It works only against your own federal tax debt, only before the 23C date, and only up to the hardship you can document. Confirm there is no TOP debt, gather the proof, call 800-829-1040, and escalate to TAS if nothing happens within 24 hours. Then fix the balance underneath, because the offset comes back every filing season until you do.
Offset bypass refund questions, answered
Is there an IRS form for an offset bypass refund?
No. The IRS has no form for an offset bypass refund. You request one by calling the IRS at 800-829-1040 and asking for an OBR based on economic hardship, or by contacting the Taxpayer Advocate Service at 877-777-4778 or on Form 911. Have your hardship documents and the exact dollar amount you need ready, because the IRS issues the refund for that amount and no more.
How do I successfully complete an offset bypass refund request?
Confirm the offset is for your own federal tax debt and not a Treasury Offset Program debt, gather a dated notice that shows the exact amount you need (eviction, utility shutoff, medical), call the IRS at 800-829-1040 before your return is assessed, ask for an offset bypass refund for economic hardship, and send the documents the same day. If the IRS cannot resolve it within 24 hours and your refund has not yet posted, ask for a Taxpayer Advocate Service referral.
Can an offset bypass refund stop a child support or student loan offset?
No. An OBR only bypasses an offset to your own federal tax debt under IRC Section 6402(a). The Internal Revenue Manual states that if a Treasury Offset Program debt exists, such as past-due child support, a federal student loan or state income tax, the IRS has no authority to issue an OBR. Your dispute goes to the agency that certified the debt.
When do I have to request an offset bypass refund?
Before your return is assessed, which the IRS calls the 23C date. That is when the overpayment is created and the offset happens. The manual refund paperwork has to reach IRS Accounting by the Friday cutoff before that Monday assessment date, and the IRS says most e-filed refunds arrive within about three weeks of filing. As a practical matter, request the OBR when you file or within days afterward.
How much of my refund can an OBR release?
Only the documented hardship amount, and only the part of it that would otherwise have been offset. The IRS's own example: a $1,000 overpayment, a $600 hardship request and a $500 prior-year balance produces a $600 refund, of which $100 is treated as the OBR and the remaining $400 offsets. The exact figures on your eviction, shutoff or medical notice set the ceiling.
What counts as economic hardship for an OBR?
Economic hardship within the meaning of IRC Section 6343, which means being unable to pay basic, necessary living expenses. The IRS handles each request case by case and keeps no exclusive list of qualifying expenses, so a pending eviction or foreclosure, a utility disconnection, essential medical care, or a car repair you need to keep working can all qualify. Vague financial stress does not; you need a specific expense, a specific amount, and paper proving both.
What if my refund was already offset? Can I get it back?
Usually no. Once the overpayment is applied to your balance there is nothing left to refund, and more than 30 days past the assessment date the IRS will tell you it cannot undo the offset. Two exceptions exist: if you requested the OBR in time and an IRS clerical error stopped it from being processed, the IRS can reverse the offset and issue the refund, and a later adjustment such as an amended return that creates a new overpayment can be refunded as an OBR.
Will the IRS take my refund again next year?
Yes, until the balance is resolved. Refund offset is automatic every year you have a federal tax debt, even in currently not collectible status or on many payment plans. Each year's OBR request stands alone, so the durable fix is addressing the underlying balance through an installment agreement, an Offer in Compromise, or hardship status.
Your next 24 hours
- Find out where your refund stands. Call the Treasury offset hotline at 800-304-3107 and pull your IRS account transcript. No code 826 or 898 yet means your OBR window is still open.
- Gather the hardship paper. The eviction, shutoff or medical notice with its exact dollar amount and due date, plus a copy of this year's return (or the draft, if you have not filed).
- Get a free case review before the refund posts. Call (888) 825-7779 or use the 2-minute form. An OBR is a one-shot request, and once the offset applies, the money is gone for the year.
For the IRS's own resources: the OBR procedure is in IRM 21.4.6.5.7.1, payment options for the underlying balance are at IRS.gov/payments, and the Taxpayer Advocate Service is at taxpayeradvocate.irs.gov. The Treasury Offset Program is run by the Bureau of the Fiscal Service.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.