
IRS Notices
CP49 Notice: What It Means When the IRS Applied Your Refund to Back Taxes
What this episode covers
- What is IRS notice CP49 and does it require a response?
- How do I verify a CP49 refund offset using IRS transcript code 826?
- What happens if I don't pay the remaining balance after an IRS CP49 notice?
- Can Form 8379 recover a refund taken for a spouse's separate tax debt?
The short answer: a CP49 notice means the IRS kept all or part of your tax refund and used it to pay a federal tax balance you owe from another year. It is a receipt, not a new bill or an audit. It shows which year took the money and what balance, if any, remains. Updated October 5, 2026 against the IRS page at irs.gov/cp49. Clarity Tax Relief checks the matching code 826 on the transcript for every CP49.
This guide covers what a CP49 means, how to tell it apart from the lookalike notices, the three numbers to find on it, how to dispute an offset that looks wrong, and what to do about the balance that is left over. You checked your deposit account for days, and instead of the refund you had assigned to rent and the credit card, a CP49 arrived saying the money went to a tax year you had half forgotten. That sinking feeling is real. So is the upside: your old debt just got smaller, and this letter hands you everything you need to finish the job on your terms.
A CP49 asks nothing of you by a printed deadline, because the offset has already happened. Your job now is to verify the money landed on the right year, understand what is left, and stop the leftover balance from eating next year's refund too. The image below shows what a CP49 looks like and where to find the three figures that drive every decision on this page.
What is a CP49 notice from the IRS?
A CP49 is the IRS's notice that it used all or part of your refund to pay a tax debt. In the IRS's own words on its CP49 page: "We used all or part of your refund to pay a tax debt." The debt is federal tax you owe for a different year, and the IRS is allowed to apply an overpayment to it before sending you anything. If your refund was bigger than the debt, the IRS says you will get a check for the remaining amount within 3 weeks, unless you owe other taxes or debts it is required to collect.
The notice is informational. There is no box to check and no form to return. The IRS's page lists two things you can do if you still owe money after the offset: pay online, or sign in to your online account. If you disagree, the IRS says to call the number on your notice and have your paperwork ready, such as a tax return or amended return. Everything else on this page is about doing those three things well.
⏱ The real clock: a CP49 has no response deadline. The offset already posted. But the failure-to-pay penalty adds 0.5% of the remaining balance every month (up to 25%) and interest runs at 7% per year for the fourth quarter of 2026, compounded daily, until what's left is resolved. If you believe the offset is wrong, call the number on the notice as soon as possible.
Why did the IRS take my refund?
Clarity Tax Relief explains a CP49 as the IRS paying itself first. The IRS sends a CP49 when it applies some or all of your current-year refund to a federal tax balance from another year. Under IRC §6402(a), the IRS is allowed to keep an overpayment and apply it to your outstanding federal tax before refunding anything to you. Its computers do this automatically, before a refund ever leaves the building.
Three details on the notice tell the whole story: the tax year your refund came from, the year (or years) the money was applied to, and either the remaining refund being sent to you or the balance you still owe. The offset happens even if you are on an active payment plan. The IRS's payment plan page says it plainly: your future refunds will be applied to your tax debt until it is paid in full. Your refund is taken on top of your monthly payments.
What a CP49 is not: an audit, a levy notice, or a new assessment. Nothing on it changes what you owed. It changes how much of it is already paid. If you are not sure why the IRS thinks you owed anything in the first place, start with why did I get a letter from the IRS and pull your account records before reacting to this one notice in isolation.
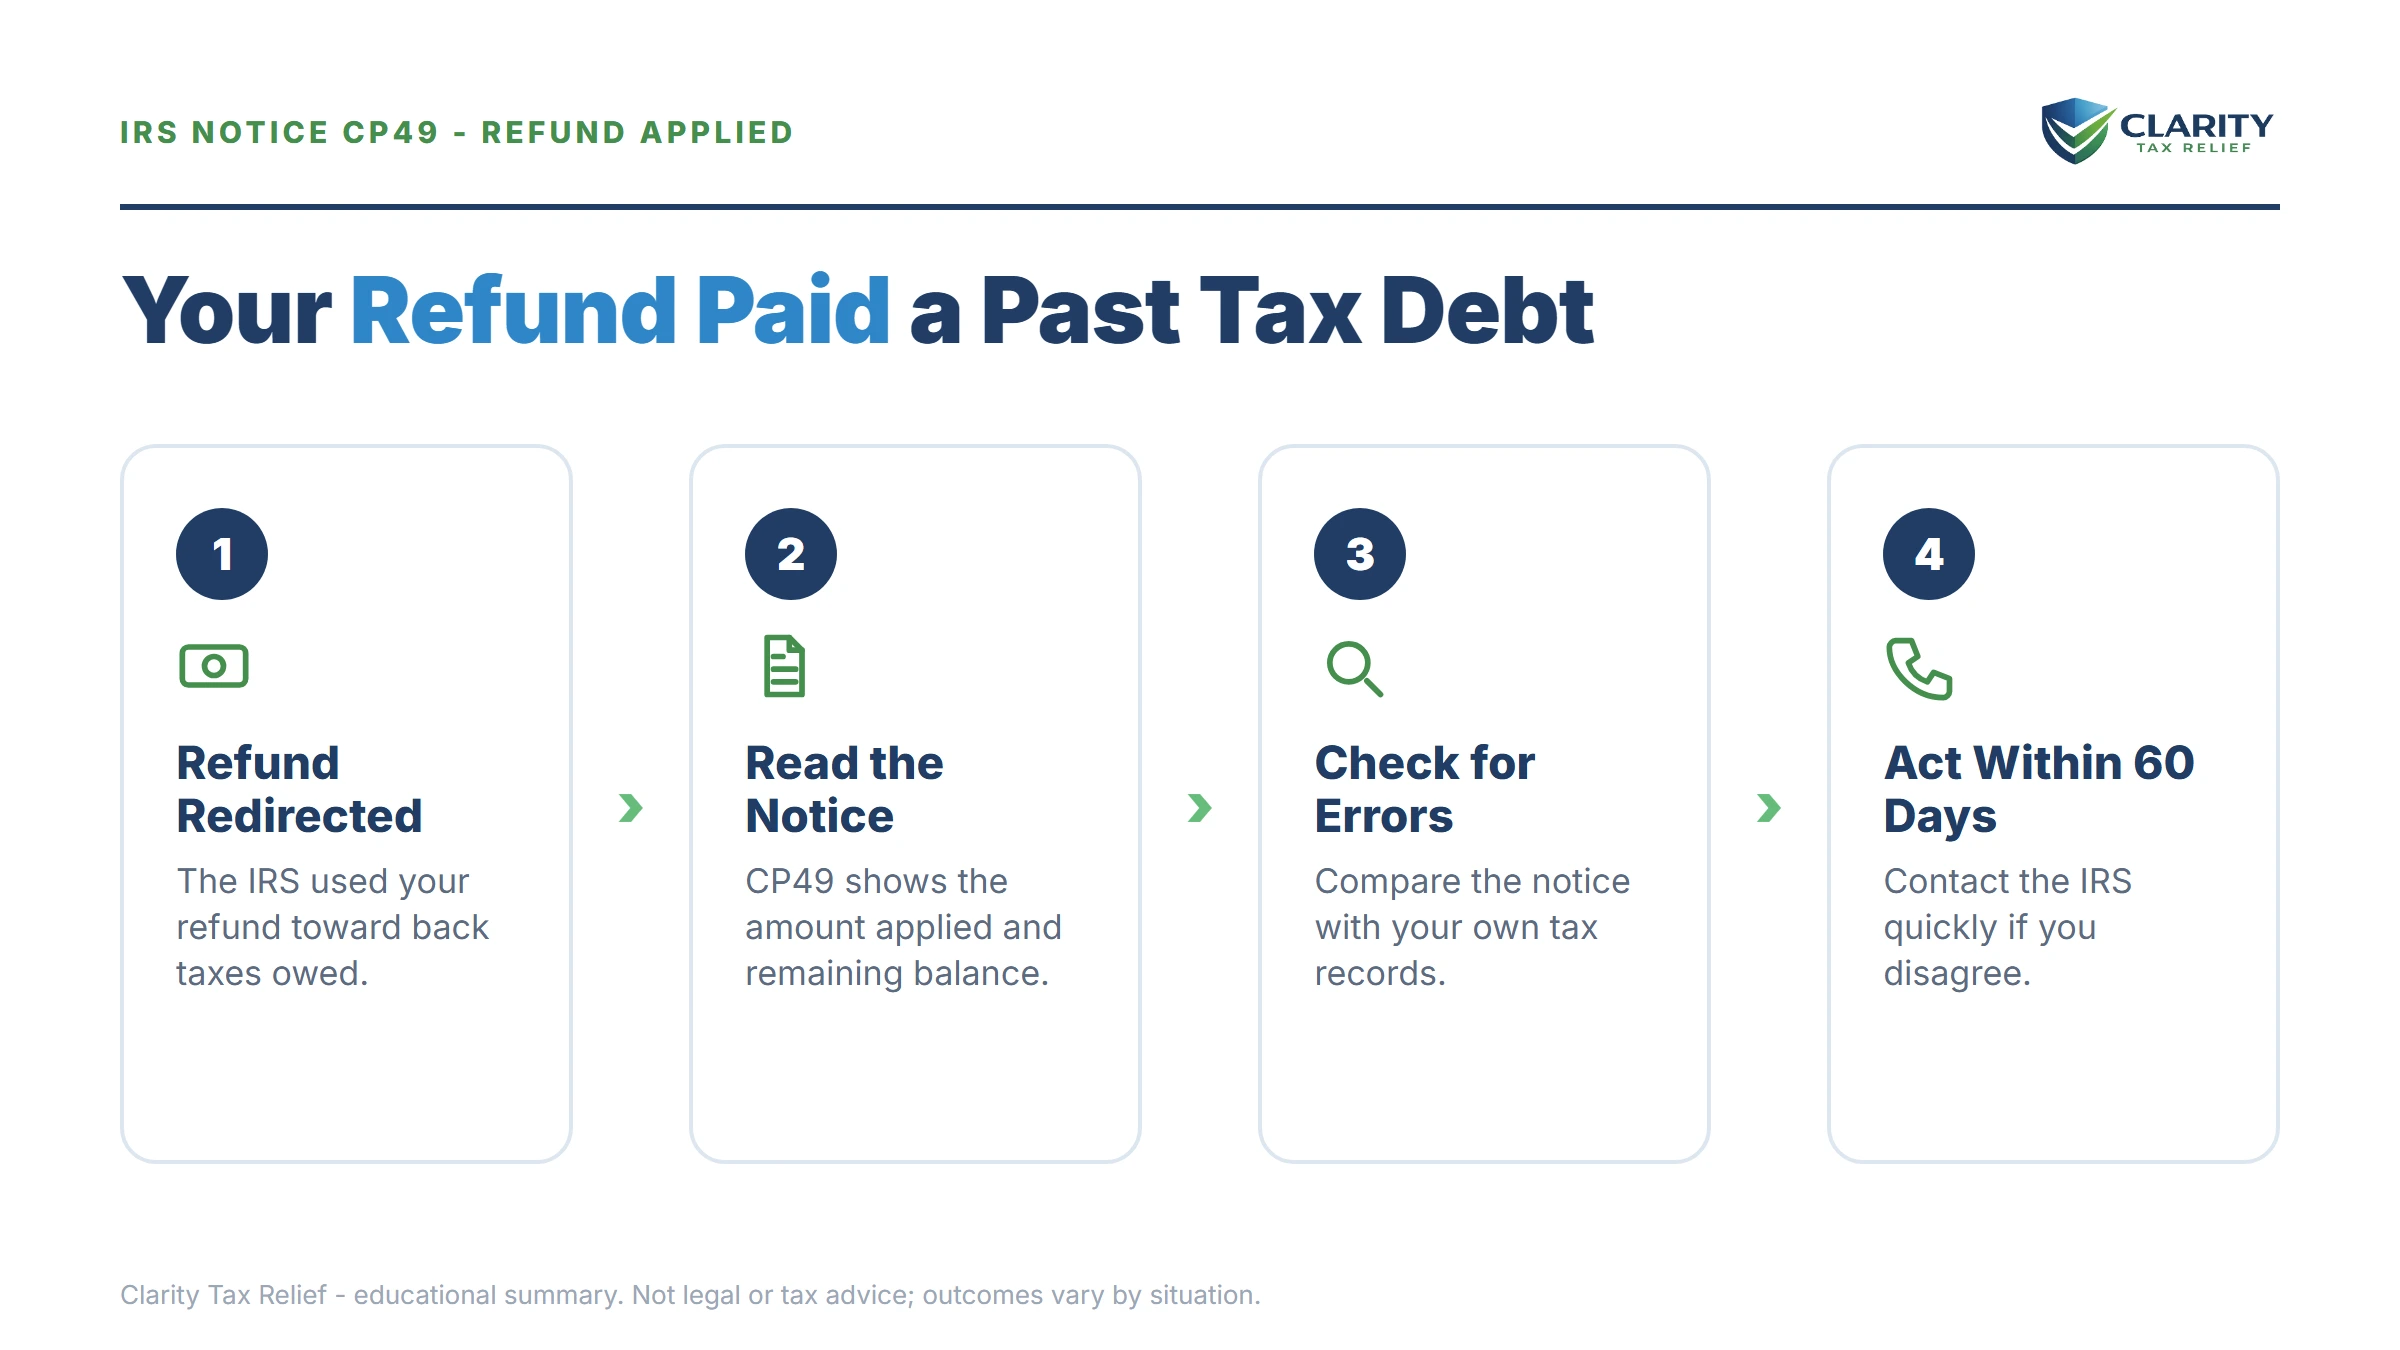
“You'll receive a check for the remaining amount within 3 weeks unless you owe other taxes or debts we’re required to collect.”
Source: Understanding your CP49 notice (IRS.gov)
Is it a CP49 or one of the lookalike notices?
The IRS uses at least six different notices and codes when a refund shrinks or disappears, and each has a different fix. Match yours before doing anything else:
| Notice or code | What it means | What to do |
|---|---|---|
| CP49 | Your refund was applied to your own federal tax debt from another year | Verify the balance, then resolve what's left (this guide) |
| CP42 / CP39 | Your refund (or overpayment) went to your spouse's tax debt | Consider injured spouse relief to recover your share |
| CP44 | Refund delayed while the IRS decides whether to apply it to other tax | Wait or respond; the offset hasn't happened yet |
| Code 826 | Transcript entry showing the same offset a CP49 announces | Confirm date, amount, and receiving year |
| Code 898 | Refund taken for a non-IRS debt (child support, student loans, state tax) through the Treasury Offset Program | Dispute with the agency that got the money, not the IRS |
| CP12 | The IRS corrected a math error and changed your refund amount | Agree, or dispute the correction within the notice window |
| CP05 | Your refund is being held for review, not applied anywhere yet | Usually wait; respond only if the IRS asks for documents |
This distinction matters most for joint filers. If the debt that swallowed your refund belongs only to your spouse (from before your marriage, or from their separate filing), Form 8379 injured spouse can recover your portion of the refund. The IRS's CP49 page says the same thing: you may still be eligible to claim your share of the refund by filing Form 8379, Injured Spouse Allocation. A CP49 for your own debt has no equivalent claw-back.
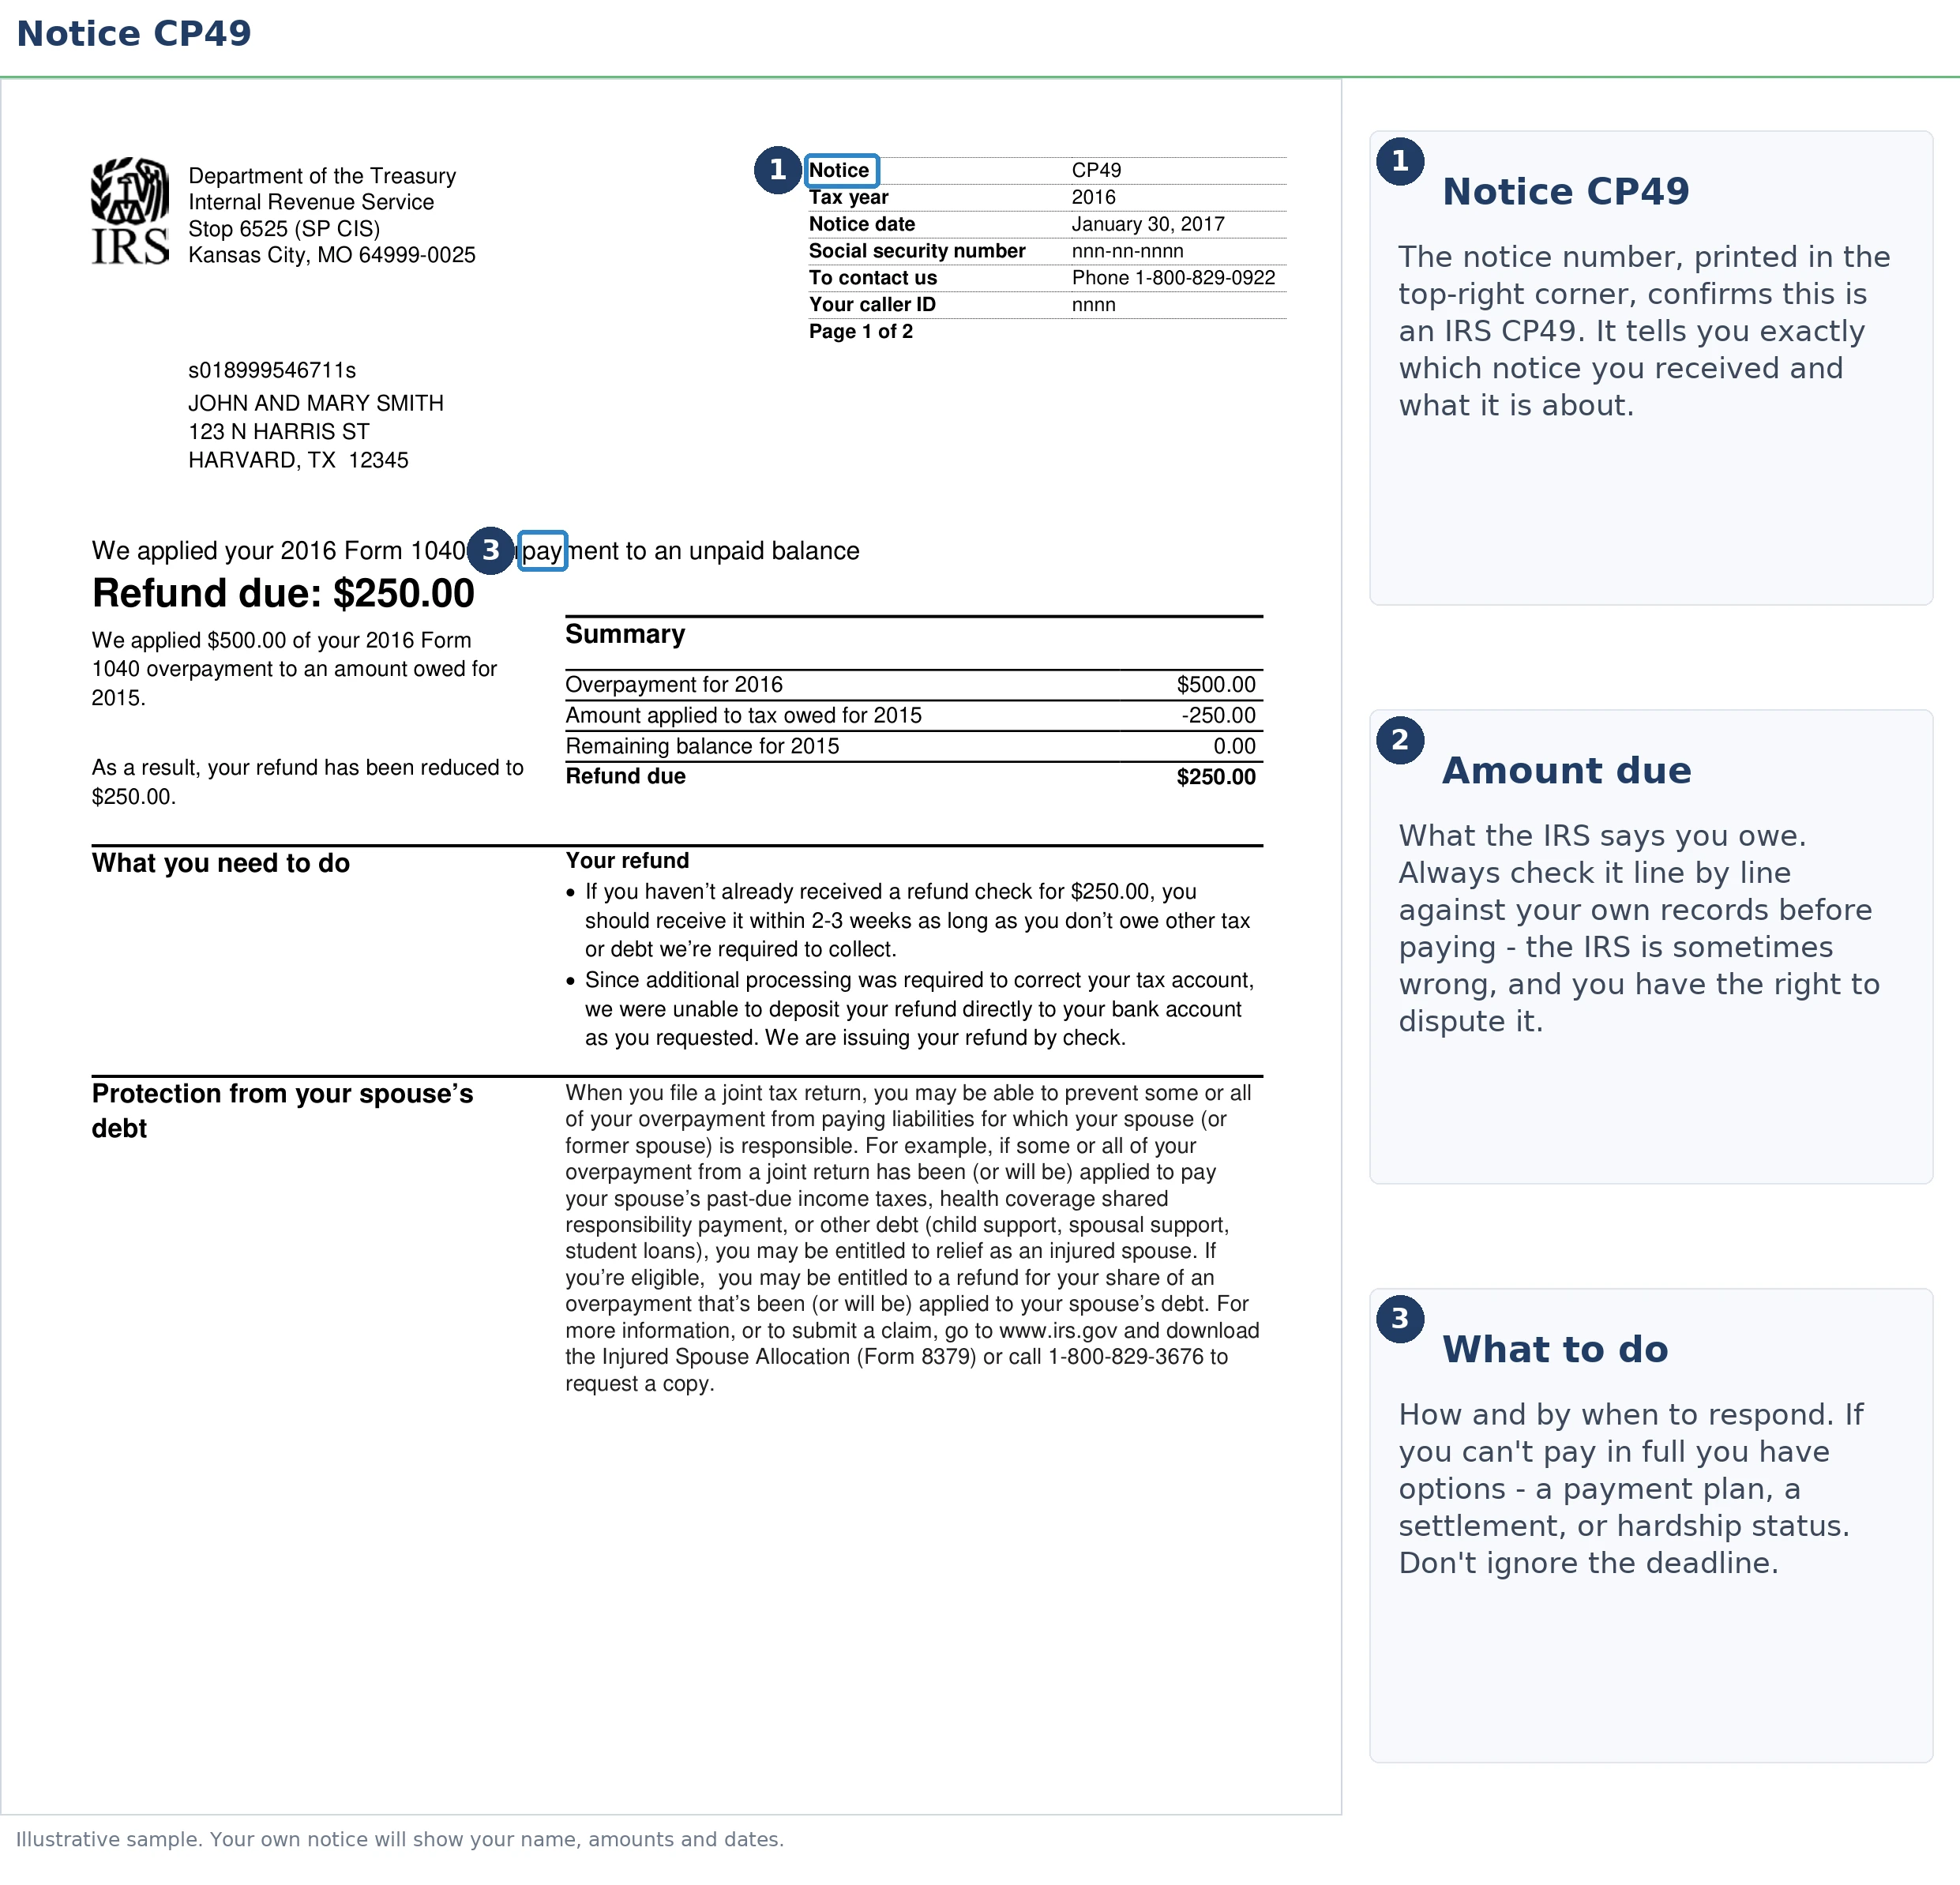
How do you read a CP49?
Reading a CP49 takes about a minute once you know where to look. The notice names the tax year your refund came from, the year it was applied to, the amount applied, and then either the refund still coming to you or the balance you still owe. Every decision you make next depends on those figures. Find:
- The amount applied, and to which year. If the money landed on a year you already paid, or a year that is not yours, you have a dispute rather than a debt.
- Any remaining refund coming to you. If your refund was larger than the old balance, the leftover is still on its way, and the CP49 tells you how much. The IRS says to expect that check within 3 weeks.
- The remaining balance you still owe. If the refund did not cover everything, this number is what keeps accruing penalties and interest starting today.
Also note the notice date and the phone number in the top corner. You will need both if anything does not match your records.
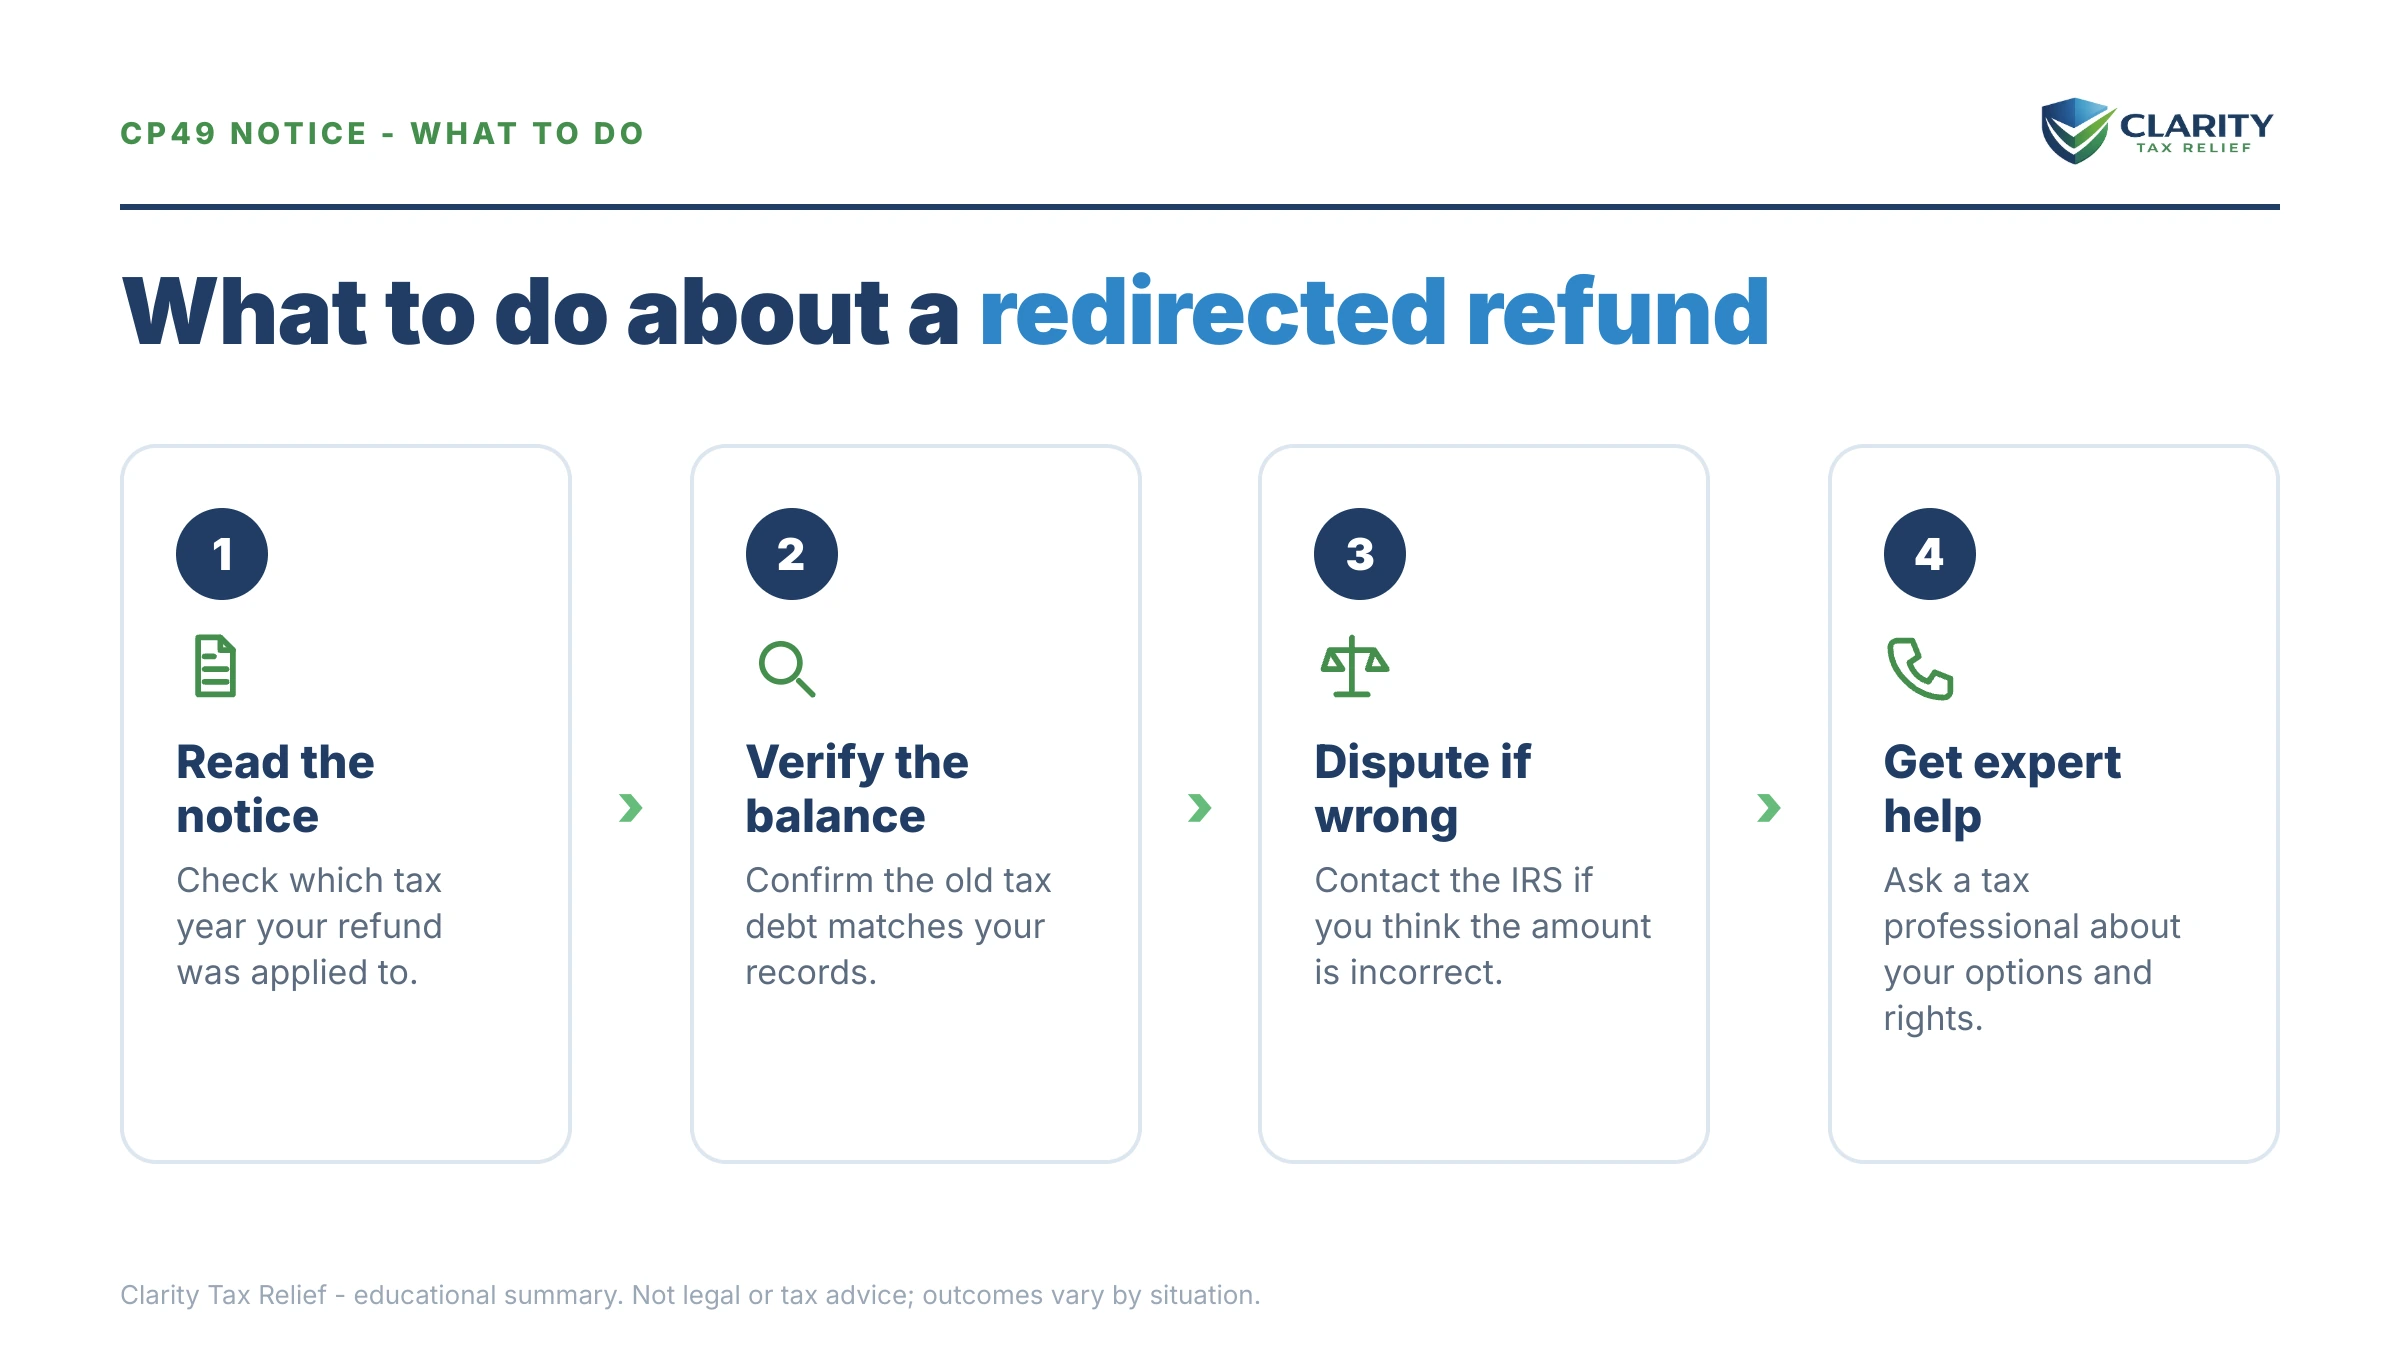
Partial offsets are the confusing case
Clarity Tax Relief does the subtraction for clients on every partial offset. The IRS can apply part of your refund to pay an older balance and release the rest. That produces a smaller deposit than expected and no obvious explanation until the notice arrives. If the arithmetic on the notice does not reconcile with what landed in your account, contact the IRS with both figures rather than assuming one of them is wrong.
What if you disagree with the CP49?
If the old balance is wrong, was already paid, or belongs to someone else, you dispute it. The IRS's instruction is short: call the number on your notice and have your paperwork ready, such as a tax return or amended return. In practice there are four moves. The order matters because the first one is free and takes ten minutes.
| What you believe happened | What to do | How long it takes |
|---|---|---|
| You are not sure the old balance is real | Pull the account transcript for the year the money went to. Look for the assessment and for a code 826 entry matching the CP49 amount. Our IRS transcript code guide decodes the rest of the lines. | Minutes online; 5 to 10 calendar days by mail (800-908-9946) |
| You already paid that year | Call the number on the notice with the payment confirmation, canceled check or bank record. Ask the IRS to locate the payment and move it to the right year. | One call, plus hold time. Our 188-call hold time study shows the best times to dial. |
| The original return for that year overstated the tax | File Form 1040-X to amend it. If the amended return lowers the balance, the offset gets refunded to the extent it exceeded what you really owed. | The IRS says to allow 8 to 12 weeks, and in some cases up to 16 weeks |
| The debt is your spouse's alone | File Form 8379, Injured Spouse Allocation, to claim your share of the joint refund. | Varies; the IRS does not publish a fixed timeline on the form page |
| The refund went to a non-IRS debt | That is not a CP49. Call the Bureau of the Fiscal Service at 800-304-3107 and dispute with the agency that received the money. | Depends on the agency |
Start with the transcript whatever you suspect, because it settles most disputes before anyone calls. The code 826 line on the refund year shows the overpayment moving out. On the year that received it, you should see the same amount posting as a credit. If the amounts match the notice and the balance was real, there is nothing to dispute and the question becomes how to pay the rest. If you see a code 898 instead of 826, the refund went to a non-IRS debt and you are in the Treasury offset lane below.
Worked example: a CP49 on an $8,900 balance
A worked example makes the stakes concrete. Say you owe $8,900 from your 2023 return, a year your withholding fell short, and you rent, with no home equity or savings cushion. Your 2025 return shows a $3,150 refund. Instead of a deposit, you get a CP49: $3,150 applied to 2023, refund to you $0, remaining balance $5,750.
Here is what that $5,750 does if you leave it alone. The failure-to-pay penalty runs 0.5% per month, about $29 a month at this balance, and interest at 7% per year (the IRS rate for the fourth quarter of 2026) compounds daily on top. Do nothing for a year and the penalty alone adds roughly $345 before interest, and next spring's refund gets swept automatically too. You can estimate how fast your own balance grows with our IRS Penalty & Interest Calculator.
Now the fix. $5,750 is well inside the limits for an online payment plan. Simple division ($5,750 over 48 months is about $120 per month before accruals) clears it in about four years. Pay more and both the timeline and the interest shrink. While a plan is in place and you filed on time, the failure-to-pay penalty drops to 0.25% per month. For a renter this matters doubly. The IRS cannot take equity you do not have, so if collection escalates, your paycheck and bank account are the targets, and a modest monthly plan takes both off the table. Run your own numbers in the IRS payment plan calculator to see what a monthly amount does to the payoff date.
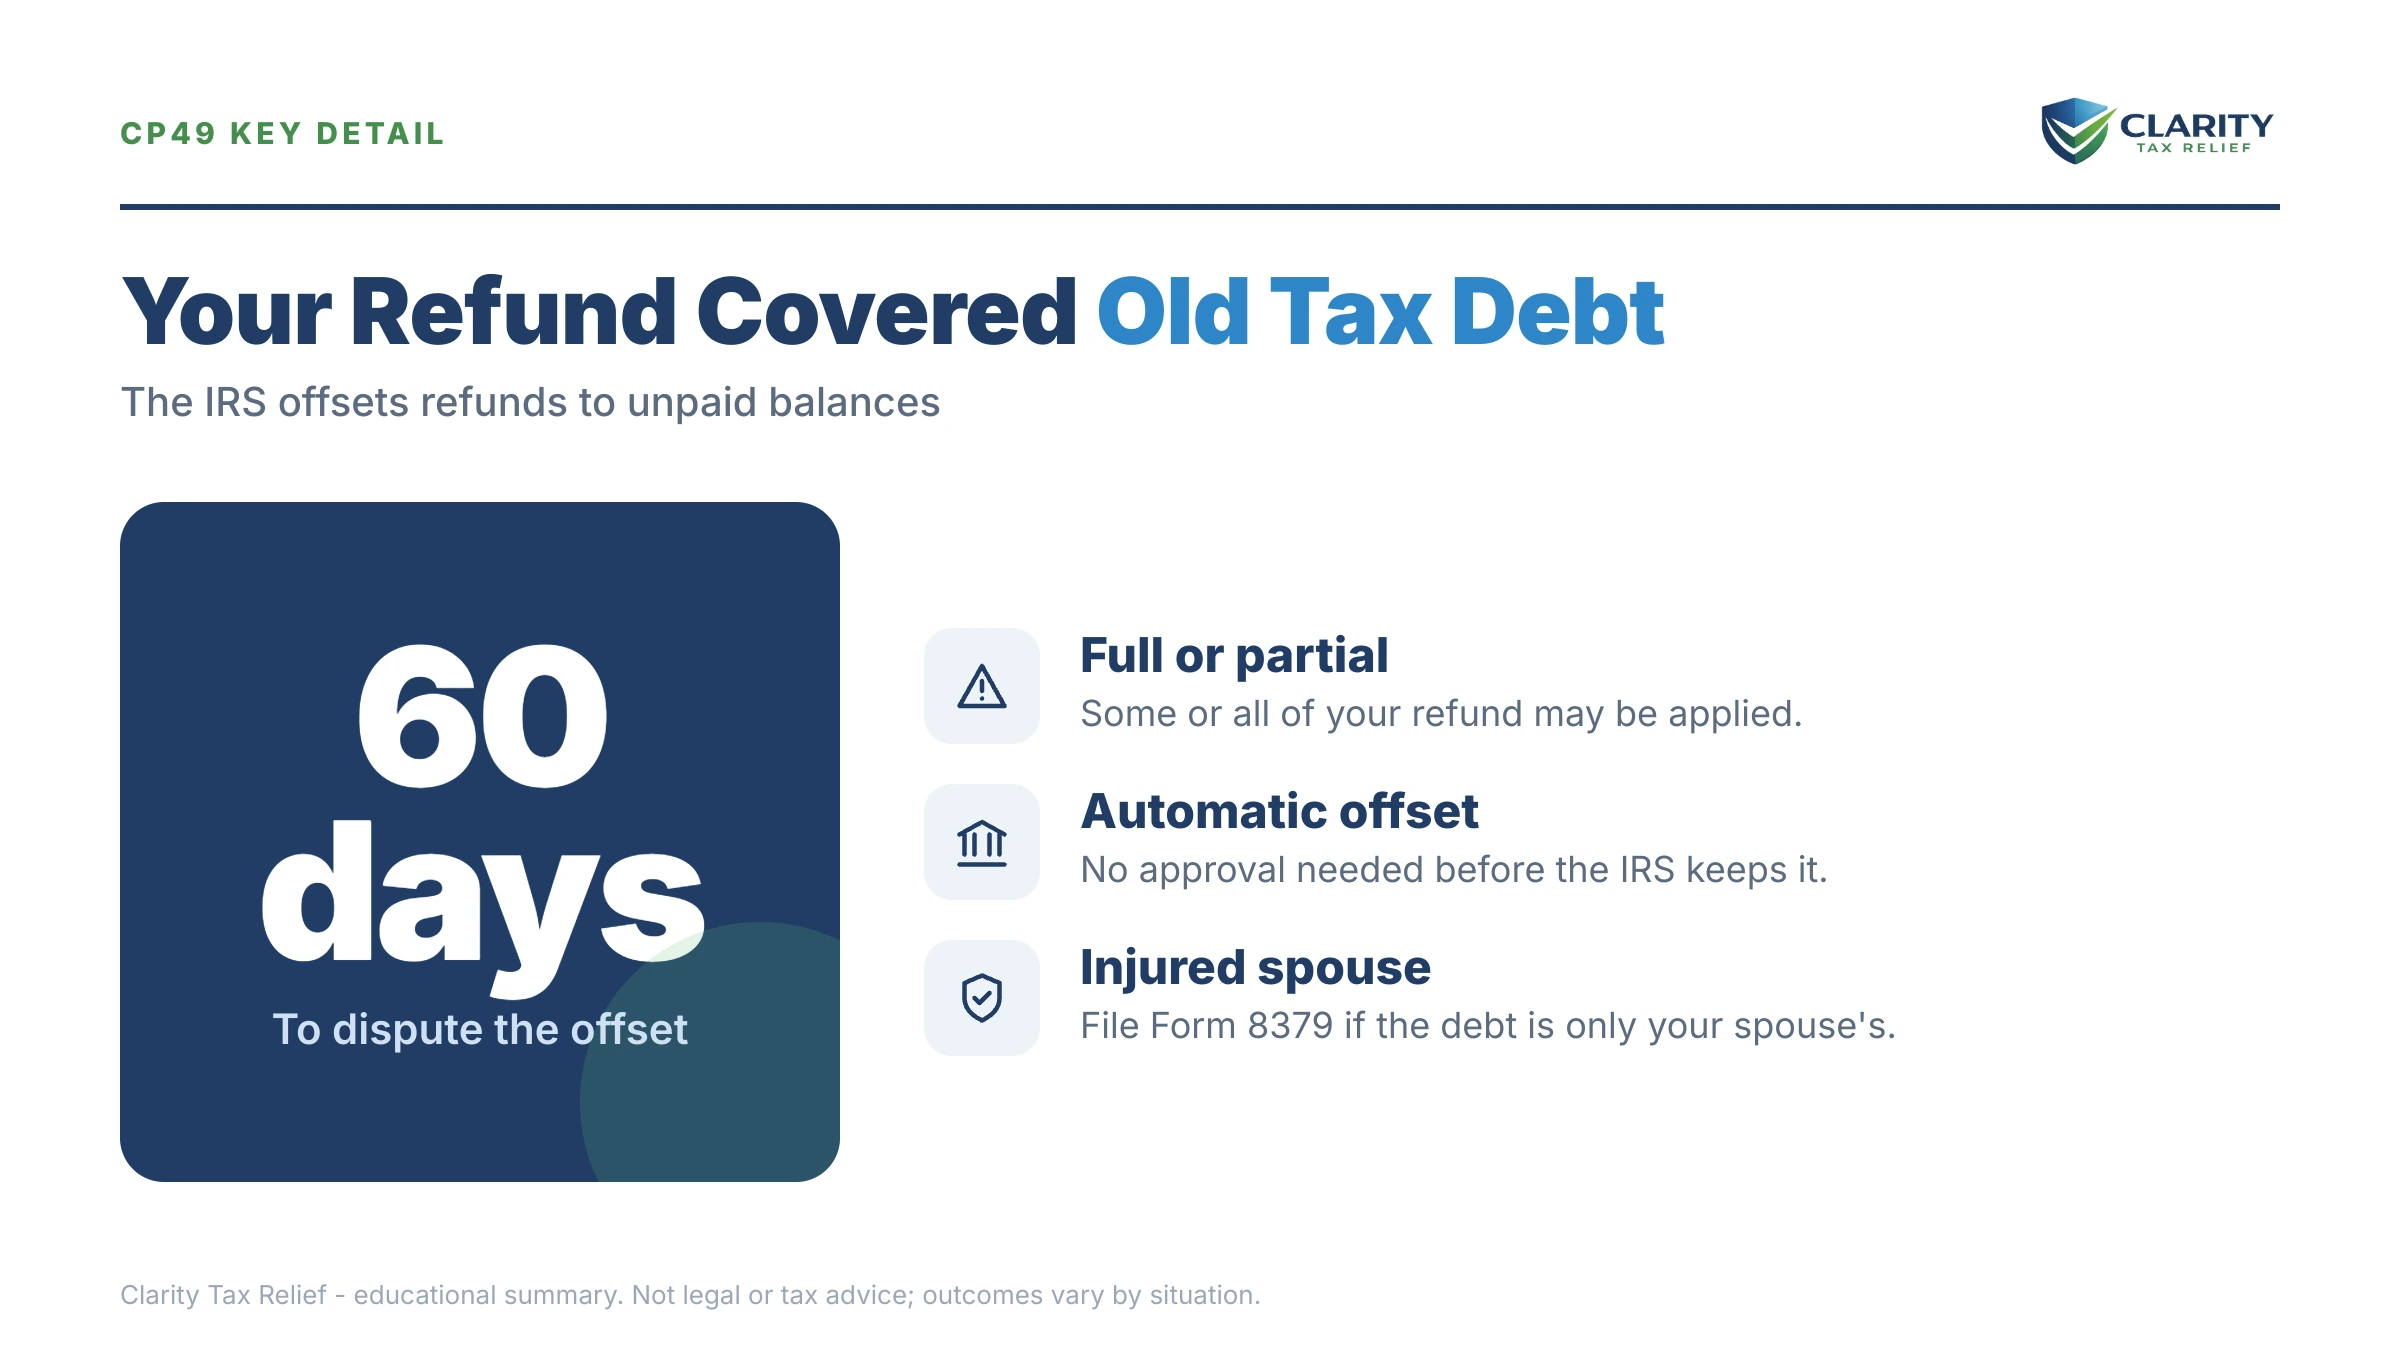
What happens if you ignore the balance left after a CP49?
A CP49 reduces your debt. It never pauses collection on what remains. The remaining balance moves through the IRS's automated sequence, each stage carrying more enforcement power than the last:
“A CP49 reduces the debt. It never pauses collection on whatever is left,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
- CP49. You are here. The offset posted. The leftover balance accrues penalty and interest from day one.
- Balance-due reminders. CP501 and CP503 notices if your account is in an active collection cycle; an annual CP71 reminder if it is dormant. Still just bills, though growing ones.
- CP504, Notice of Intent to Levy. The IRS can now seize your state tax refund. A federal tax lien becomes a live possibility, and the failure-to-pay penalty rises to 1% per month if you do not pay within 10 days of a levy notice.
- LT11 / Letter 1058, Final Notice. This starts a 30-day clock and your Collection Due Process rights (requested on Form 12153). After it runs, the IRS can levy wages and bank accounts, the assets a renter has.
- Next filing season: the sweep repeats. Every future refund is applied to the balance year after year until it is gone.
One 2026 reality check: per TIGTA reports, IRS staffing fell sharply in 2025, so reaching a human is harder. Offsets, notices, and levies are issued by automated systems that never stopped running. The machine escalates on schedule whether or not anyone reviews your file. If the balance that remains is the one a CP14 balance-due notice first announced, that notice's sequence is the one you are now in.
One forward-looking exception. If you expect next year's refund and losing it would leave you unable to cover essential living costs, an offset bypass refund for hardship can sometimes protect it. It generally must be requested before the offset posts, often through the Taxpayer Advocate Service.
The IRS just kept your refund: don't let the rest of the balance ride
Send us your CP49. An experienced tax professional will verify the offset posted correctly, confirm what you actually still owe, and map the cheapest path to closing it out. Free, confidential, and before penalties and interest add another month's growth.
What are your options for the balance that remains?
The CP49 does not list your options. The IRS has several, and which one fits depends on the size of what is left and what your budget can honestly carry:
| Option | Upfront cost | Timeline | The catch |
|---|---|---|---|
| Pay in full | $0 | Immediate | None; accruals stop the day the balance hits zero |
| Short-term payment plan | $0 setup fee | 180 days or less, for balances under $100,000 | Penalties and interest continue until paid |
| Long-term installment agreement | $29 setup fee with direct debit (waived for low income); $69 otherwise ($43 for low income, which may be reimbursed) | Monthly payments; apply online for balances of $50,000 or less | Future refunds are still applied to the balance while you pay |
| Currently Not Collectible | $0 | Lasts while genuine hardship does | Balance and accruals remain; refunds still offset |
| Offer in Compromise | $205 fee (waived with low-income certification) | Months to a decision; automatically accepted if the IRS makes no determination within two years of its receipt date (appeal periods excluded) | Means-tested; per IRS data, the IRS accepted roughly 1 in 5 offers in FY2024 |
| Penalty abatement | $0 | Weeks once requested | Removes qualifying penalties only; interest on tax remains |
Two notes at a typical post-CP49 balance. An Offer in Compromise is rarely the right tool for a few thousand dollars unless your finances show the IRS could never collect it. You may qualify only if your income and assets fall short of the full debt over the collection period. And penalty relief is worth checking even on small balances: first-time abatement applies if your prior three years were clean, and starting summer 2026 the new Automatic Exemption from Penalty (AEP) may grant qualifying relief automatically for eligible returns processed after it starts, while 2025 returns processed before that still need a first-time abatement request.
How to respond to a CP49, step by step
- Verify where the money went. Log into your IRS online account and pull the account transcripts for both years. The code 826 entry should match the amount and year printed on the notice.
- Confirm the remaining balance. Compare the balance the CP49 shows with your online account, and note whether any other tax years also carry balances. They will swallow future refunds too.
- Dispute it if anything is wrong. Call the number printed on the notice with proof of payment or the correct figures. Joint filers protecting their share of the refund file Form 8379.
- Pick a plan for what's left. Pay in full, set up a short-term or monthly payment plan, or pursue hardship or settlement options, before the next collection notice arrives.
- Fix next year's withholding. Stop over-withholding so you are not building another refund the IRS will keep. Put that money toward the balance each month instead.
If you agree with the notice and can clear the rest, payment options are all in one place at IRS.gov/payments. The IRS's own summary of this notice is at Understanding your CP49 notice (the short address printed on the letter, irs.gov/cp49, lands on the same page).
Red flags to check before you do anything else
- The year the money went to is one you already paid, or one that is not yours. That is a dispute. Start with the transcript, then call the number on the notice with proof.
- The deposit and the notice do not add up. A partial offset can release part of the refund. Contact the IRS with both figures rather than guessing which one is wrong.
- The transcript shows code 898 instead of 826. The refund went to a non-IRS debt through the Treasury Offset Program. The IRS cannot fix that; call 800-304-3107.
- The debt belongs only to your spouse. File Form 8379 to claim your share. Waiting does not recover it.
- Other tax years also carry balances. Each one will swallow future refunds until it is cleared. Note all of them before picking a plan.
- You are still over-withholding. Every refund you build will be kept until the balance is gone. Adjust it and send the money to the balance directly.
- A CP504 or LT11 is already in the mail for the remaining balance. The levy clock is running, and that changes the order of operations.
CP49 vs. a Treasury offset: which system took the money?
Clarity Tax Relief identifies which system took the money first. Searchers mix these up constantly, and the fix depends on which one you got. A CP49 is the IRS applying your refund to your own federal tax balance. A Treasury Offset Program (TOP) offset is the Bureau of the Fiscal Service taking your refund for a debt owed to someone other than the IRS. Per IRS Tax Topic 203, that covers past-due child support, federal agency non-tax debts, state income tax obligations and certain state unemployment compensation debts. BFS mails its own notice showing the original refund, the offset amount and the agency that received the money, and the number for questions is 800-304-3107.
| Detail | CP49 | Treasury Offset Program |
|---|---|---|
| Who took the refund | The IRS | Bureau of the Fiscal Service, on behalf of another agency or a state |
| What the debt is | Federal tax you owe for another year | Child support, federal non-tax debt, state income tax, certain state unemployment debt |
| Letter you receive | CP49 from the IRS | Offset notice from BFS naming the agency paid |
| Transcript code | 826 | 898 |
| Who to call | The number on the CP49 | 800-304-3107 (TTY/TDD 800-877-8339), then the agency that got the money |
| Injured spouse claim | Form 8379 if the tax debt is your spouse's alone | Form 8379 if the non-tax debt is your spouse's alone |
If a single refund was large enough, both can happen in the same season. The IRS takes its share first and the remainder goes to TOP. In that case you get both letters and need both numbers.
Can you handle a CP49 yourself?
Most people who receive a CP49 do not need professional help. If the offset matches your records, the debt is yours, and the remaining balance is something you can pay within 180 days or through an online installment agreement, handle it yourself. The whole thing takes an evening.
Experienced help changes outcomes in a narrower set of situations. A CP504 or LT11 has already arrived for the remaining balance and the levy clock is running. You have multiple years with balances or unfiled returns feeding the debt. The offset went to a spouse's separate liability and an injured spouse allocation needs to be built correctly. Or paying anything would create real hardship, where the CNC and offer math has to be documented rather than guessed. In those cases, sequencing (which year, which program, which form first) is what determines the final cost. The investigation that answers those questions costs $495 for an individual; see our pricing page for what it covers.
Terms on your CP49, decoded
- Refund offset: the IRS keeping your refund and applying it to a debt instead of sending it to you.
- Overpayment: the IRS's word for your refund, tax paid beyond what the year required.
- Code 826: the transcript entry recording an overpayment moved from one tax year to another.
- Injured spouse: a joint filer whose share of a refund was taken for the other spouse's separate debt, recoverable via Form 8379.
- Failure-to-pay penalty: the 0.5%-per-month charge that keeps growing on any balance the offset didn't cover.
- CSED: the Collection Statute Expiration Date, 10 years from assessment, after which the IRS generally can't collect, though appeals, offers, and bankruptcy pause the clock.
The bottom line on a CP49 notice
The IRS kept your refund and put it on an older federal balance. Nothing is due by a printed date. Check that the code 826 entry matches the notice, confirm what is left, and dispute it only if the year or the amount is wrong. Then deal with the remainder before the next notice does: pay it, put it on a plan, or ask for penalty relief if your prior three years were clean. And fix the withholding, because the sweep repeats every spring until the balance is gone.
CP49 questions, answered
What is a CP49 notice from the IRS?
A CP49 is the IRS telling you it used all or part of your tax refund to pay a federal tax debt from another year. It is a receipt for an offset that already happened, not a bill or an audit. The notice shows the year the money went to, the amount applied, and either the refund still coming to you or the balance you still owe. If you still owe money, the IRS's page says to pay online or sign in to your online account.
Why did the IRS take my refund and send me a CP49?
Because IRS records show you owe federal tax from a prior year. The law lets the IRS apply any overpayment to that debt before sending you the rest. No human decided to take your money. The offset runs by computer, and it happens even if you're on a payment plan. Check your IRS online account to confirm the old balance is real before assuming the notice is right.
How do I read a CP49 notice?
Find three figures. First, the amount applied and the tax year it went to. Second, any remaining refund still coming to you, which the IRS says arrives by check within 3 weeks unless you owe other debts. Third, the balance you still owe, which is the number that keeps growing. Also note the notice date and the phone number in the top corner in case anything does not match your records.
What should I do if I disagree with my CP49?
Call the number on the notice and have your paperwork ready, such as the tax return or an amended return, which is the IRS's own instruction. Before you call, pull the account transcript for the year the money went to and confirm the balance and the code 826 entry. If the original return overstated the tax, file Form 1040-X; the IRS says amended returns take 8 to 12 weeks, sometimes up to 16. If the debt is your spouse's alone, file Form 8379.
Can I get my refund back after a CP49 offset?
Usually only if the underlying debt is wrong. If you already paid the old balance, if the money posted to the wrong year, or if the debt belongs to your spouse alone, you can dispute it with proof and have the offset reversed or reapplied. Joint filers whose refund covered a spouse's separate debt can file Form 8379 to recover their share. Hardship reversals after the fact are rare. The offset bypass refund process generally has to happen before the refund is taken.
Will the IRS keep taking my refund every year?
Yes, until the balance is fully paid or otherwise resolved. Refund offsets repeat automatically each filing season, and they continue even while you're on an installment agreement. The IRS's payment plan page says your future refunds will be applied to your tax debt until it is paid in full. Future offsets stop only when the debt is paid off, an offer in compromise is accepted, or the balance expires under the 10-year collection statute.
Is a CP49 the same as a Treasury Offset Program offset?
No. A CP49 means the IRS applied your refund to your own federal tax debt internally. The Treasury Offset Program takes refunds for other debts, such as child support, federal agency non-tax debt and state income tax, and posts as code 898 on your transcript, with a letter from the Bureau of the Fiscal Service instead of a CP49. Questions about a TOP offset go to 800-304-3107. The dispute paths are completely different, so identifying which one hit you comes first.
What does code 826 on my transcript mean?
Code 826 is the transcript entry for exactly what a CP49 announces: an overpayment from one tax year transferred to the balance on another year. The date and amount next to code 826 tell you when the offset posted and how much moved. If you see 826 but never received a CP49, the notice may have gone to an old address. Update it with Form 8822 so you don't miss the next letter.
Your next 24 hours
- Find the three figures on your CP49: the amount applied and its receiving year, any remaining refund coming to you, and the balance you still owe. Circle them.
- Gather your records: the notice itself, your last two tax returns, and a recent pay stub or income snapshot. That is everything needed to verify the offset and price a payment plan.
- Get a free case review: submit the 2-minute form or call (888) 825-7779. The refund is gone, but the leftover balance is still compounding monthly, and it will take next year's refund too. Resolving it this week is the cheapest it will ever be.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.