
IRS Audits
How Far Back Can the IRS Audit? The 3-Year, 6-Year, and Unlimited Rules (2026)
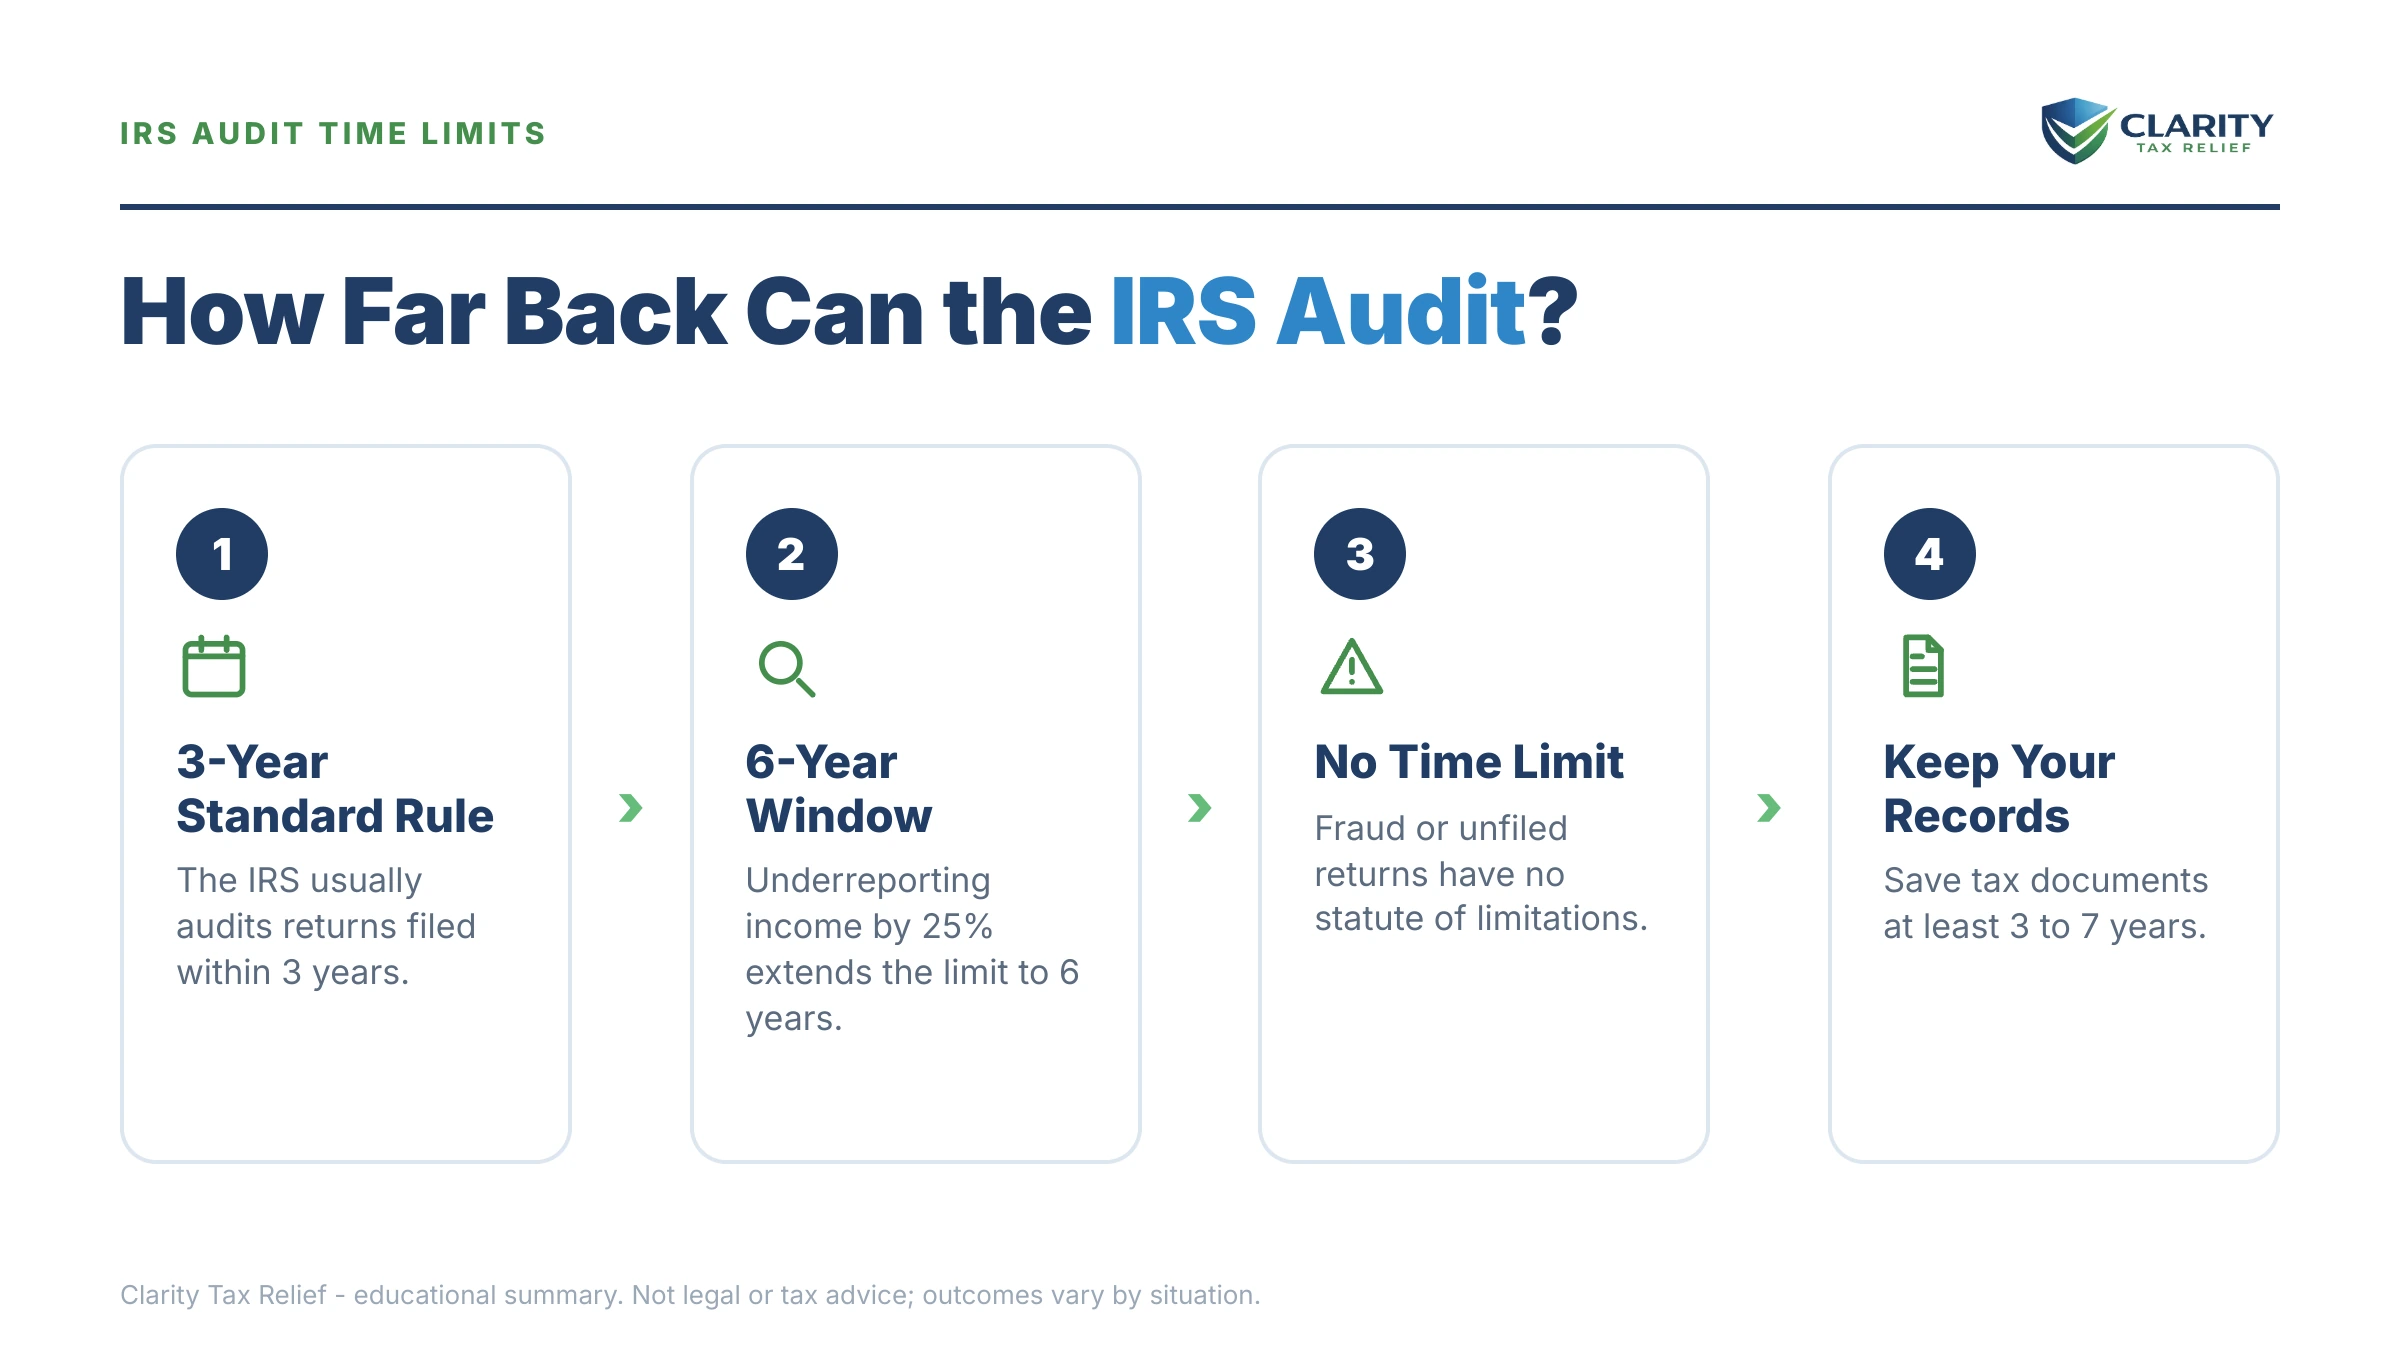
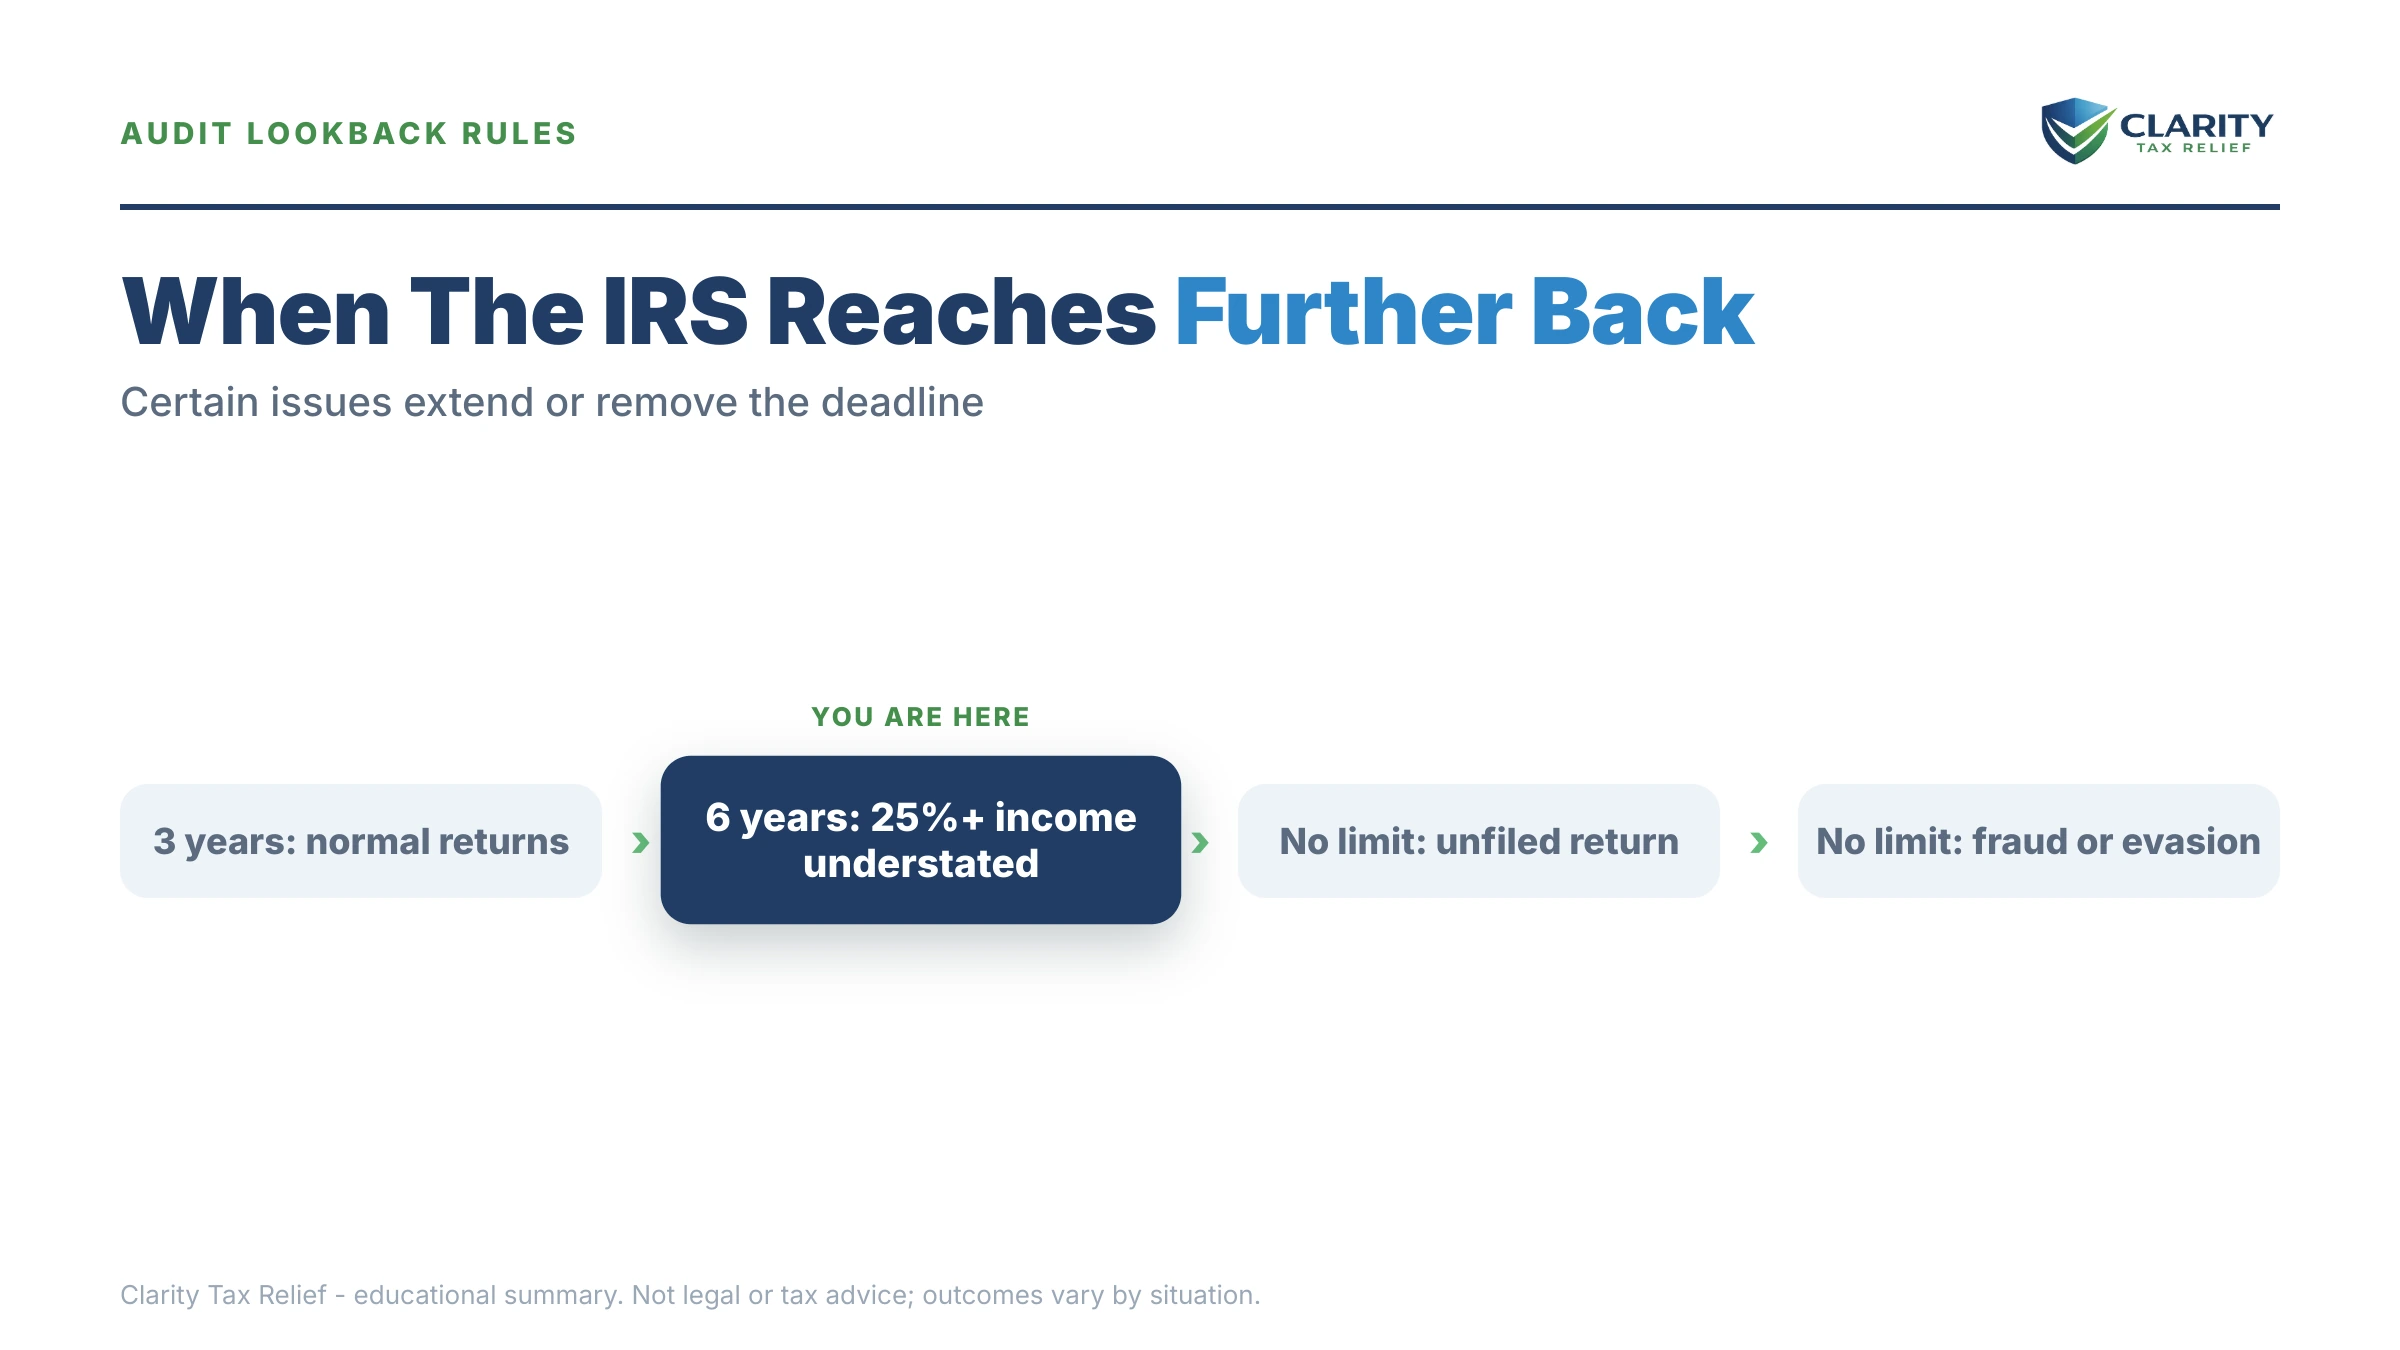
How far back can the IRS audit? Generally 3 years from the later of your filing date or the return's due date. That stretches to 6 years if you omitted more than 25% of your gross income, and there is no limit for fraud or for any year you never filed a return.
This guide covers the three federal audit windows (3 years, 6 years, and no limit), when each clock starts, what a substantial omission means, why old years get opened, what an ignored exam turns into, and how to check your own transcript for audit activity. Maybe you and your spouse just found a 1099 that never made it onto a joint return from three or four years ago, and now you're both counting backward, wondering which years the IRS can still touch. The law draws hard lines around how far back the IRS can go. Once you know where those lines sit for your years, you'll know which ones need attention and which ones are closed for good.
The image below shows how the three windows stack up and where to find the date that controls yours.
⏱ The controlling clock: the IRS has 3 years to audit and assess, counted from the later of the day you filed or the return's original due date (IRC §6501). Filing early doesn't start the clock early. A return filed in February is treated as filed on the April due date.
How far back can the IRS audit?
The IRS can audit a filed return for 3 years, for 6 years if you omitted more than 25% of your gross income, and forever if the return was fraudulent or never filed.
The 3-year window is the default, and it covers the overwhelming majority of taxpayers. If you filed on time and reported your income substantially correctly, the year closes 3 years after the due date. After that, the IRS legally cannot assess more tax for it, even if it later finds an error.
The 6-year window opens only when something big was left off: more than 25% of the gross income shown on the return, more than $5,000 of income tied to foreign financial assets, or an overstated cost basis that shrank a reported gain. The unlimited window applies to fraud and to unfiled years, and "unlimited" means exactly that.
| Your situation | How far back the IRS can audit | Where the rule comes from |
|---|---|---|
| Filed, substantially accurate return | 3 years from filing or the due date, whichever is later | IRC §6501(a) |
| Omitted more than 25% of gross income | 6 years | IRC §6501(e), "substantial omission" |
| Omitted more than $5,000 of foreign-asset income | 6 years | IRC §6501(e) |
| Overstated cost basis to shrink a gain | 6 years | Treated as an omission of income |
| ERC claims from certain 2021 quarters | 5 years | Special ERC assessment window |
| Fraudulent return or willful evasion | No time limit | IRC §6501(c) |
| No return ever filed | No time limit; the clock never starts | IRC §6501(c)(3) |
| You signed a Form 872 extension | Whatever date you agreed to | Consent to extend the statute |
In practice, the IRS moves faster than the law allows. Most audits open within about two years of filing. The IRS's own guidance says it usually doesn't reach back more than the last six years even where it legally could. "Usually" isn't a shield, though. Unfiled years and payroll credit claims are exactly where the IRS reaches deepest right now.
When does the audit clock start, and what keeps a year open?
The 3-year audit statute starts on the later of the date you filed the return or its original due date. It never starts at all for a year you didn't file.
That single rule explains most of the confusion around old years:
- Filed early? The clock starts on the due date rather than your filing date. A 2024 return filed in February 2025 is treated as filed April 15, 2025, so it is open through April 2028.
- Filed late or on extension? The clock starts the day the IRS receives the return. An October 15 extension filing keeps the year open six months longer than an April filing.
- Never filed? A return you never filed has no audit statute at all. The year stays open until three years after you finally file it. Even a substitute for return the IRS files for you does not start the clock. Only your own signed return does. (Practically, the IRS's enforcement policy focuses on a 6-year lookback for unfiled returns, though that is policy rather than law.)
- Amended a return? Amending does not restart the 3-year clock. The one wrinkle: an amended return showing more tax, filed within 60 days of the statute expiring, gives the IRS 60 extra days to assess that additional amount.
- Payroll returns? All four quarterly 941s for a calendar year are treated as filed on April 15 of the following year, so their clocks run together.
- Asked to extend? If an audit is running out of time, the examiner will ask you to sign Form 872, a consent that extends the assessment date. Whether to sign is a real strategic decision. Refusing usually triggers an immediate notice of deficiency on the IRS's current numbers, while signing keeps the year open longer.
What counts as a "substantial omission" under the 6-year rule?
The IRS gets 6 years instead of 3 when a return omits more than 25% of the gross income it reports.
Three details in that sentence trip people up. First, the test measures gross income, and on a joint return that means both spouses' combined gross income. A married couple filing jointly measures the 25% against everything on the return, so one spouse's forgotten 1099 is weighed against the whole household's income, which can help or hurt depending on the numbers.
Second, for the self-employed, "gross income" generally means total receipts before expenses. A business that grossed $80,000 and netted $12,000 measures omissions against a much bigger base than the owner expects. It also means unreported receipts are what trigger the longer window. Overstated deductions alone don't open the 6-year door; unreported income does.
Third, two other paths reach the same 6-year result: omitting more than $5,000 of income tied to foreign financial assets (a foreign brokerage account, foreign rental, foreign pension), and overstating the cost basis of something you sold so the reported gain shrank. Congress added the basis rule in 2015 specifically because courts had ruled it wasn't an "omission." Now it is.
A worked example: how $19,700 lands across the 6-year line
Say a married couple filing jointly reported $104,000 of gross income on their 2022 return, filed in April 2023. A side business's $28,000 in 1099-K receipts never made it on. In early 2026 the IRS opens an exam. Is the year even open, and what does the bill look like?
The statute math first. 25% of the $104,000 reported is $26,000. The $28,000 omission exceeds that, so this is a substantial omission. The year is open through April 2029 under the 6-year rule rather than April 2026 under the 3-year rule. The couple can't run out the clock.
Now the money, all figures hypothetical and rounded:
- Additional income tax and self-employment tax on the $28,000: about $15,300
- 20% accuracy-related penalty on that underpayment: about $3,060
- Interest, accruing from April 2023 (the return's original due date, never the audit date): roughly $1,340 by the time the exam closes
- Total: about $19,700
Notice what drove a $15,300 tax problem to $19,700: time. Interest on audit assessments runs from the original due date, so every year an old return stays wrong, the eventual bill compounds. You can estimate how penalties and interest stack on your own numbers with our Penalty & Interest Calculator. If the couple can't pay in full, a 72-month installment agreement puts the starting payment around $274/month ($19,700 ÷ 72), with interest continuing until paid. One nuance worth knowing: first-time abatement doesn't cover the 20% accuracy penalty. A reasonable-cause argument sometimes does, which is one of the few places representation reliably pays for itself in an exam.
Why does the IRS open audits on older years in 2026?
Old years don't get audited at random. They get opened because a document, a data model, or a credit claim flagged a mismatch.
The most common triggers on returns that are two to five years old:
- Document matching. Every 1099, W-2, and W-2G filed under your Social Security number gets compared to your return, and mismatches surface on the underreporter track, technically a CP2000 review rather than a full audit. It runs on the same statute and produces the same kind of bill.
- Machine-scored selection. With staffing down roughly 27% since 2025, the IRS leans harder on automated scoring to pick which returns get the remaining examiners' attention. How that works is covered in our guide to IRS AI audits. Fewer humans hasn't meant fewer exams on high-score returns. It has meant more of the selection happens without a human at all.
- ERC claims. The 5-year ERC statute of limitations for certain 2021 quarters means payroll-credit exams are still opening on returns that feel ancient. If your business claimed the credit, those quarters are live.
- Unreported cash and deposits. When reported income doesn't support visible spending, examiners reconstruct income from your bank records, the bank deposit method audit, and every unexplained deposit is presumed taxable until you prove otherwise. Cash-heavy businesses and gig income are the usual targets.
- Unfiled years. Because an unfiled year never closes, high-income non-filers are a standing IRS priority, and there's no statute defense at all.
What happens if you ignore an audit of an old year?
An ignored audit doesn't close. It defaults, and the IRS assesses its own numbers with every deduction disallowed.
The sequence runs in stages, each one narrowing your options:
- The exam opens. Letter 566 (correspondence audit) or Letter 2205-A (appointment exam) names the year and the items under review, with a response date printed on it.
- No response, and the IRS writes its own report. Letter 525, the "30-day letter," arrives with the examiner's proposed changes and a 30-day window to protest to the independent Office of Appeals. Silence here waives your cheapest, most flexible dispute path.
- Still nothing, and the Notice of Deficiency follows. The CP3219A notice of deficiency (or Letter 531) starts a hard 90-day clock to petition the U.S. Tax Court, the only way to dispute the tax before paying it.
- Day 91 brings assessment. The tax posts to your account (transcript code 300), with the accuracy penalty and interest back-dated to the return's original due date.
- Assessment leads to collections. The balance enters the standard collection sequence: CP14 bill, reminders, intent-to-levy notices, then lien and levy authority. And a new clock starts. The 10-year collection statute (CSED) runs from assessment, which means a 6-year-old audit year can legally follow you for a decade after that.
Put those clocks together and the real answer to "how far back can the IRS go" gets sobering. A year audited at the edge of the 6-year window, assessed, then collected for 10 more years can shadow you for 16 years. All of it is avoidable at stage one or two.
Got a letter opening an old tax year?
The response date printed on that exam letter is real, and answering it well is the cheapest point in the entire sequence. Send us a photo. An experienced tax professional will tell you whether the year is even legally open and exactly what to send back. Free and confidential.
What are your options if an old-year audit ends in a bill?
An audit that ends in tax due gives you three decision points: appeal before assessment, dispute after assessment, or resolve the balance. Each has its own eligibility rules.
The dispute paths come first, because they can shrink or erase the bill itself. The resolution paths (payment plans, hardship status, settlement) are covered in depth in our guide to how to settle tax debt yourself. Here's how each one fits an audit balance specifically:
| Option | Who's eligible | Cost & the catch |
|---|---|---|
| Audit appeal | Anyone, within the 30-day letter window, before assessment | Free; the strongest point of pressure, since Appeals can settle on hazards of litigation |
| Tax Court petition | Within 90 days of a notice of deficiency | Small filing fee; the only pre-payment court forum, and most cases still settle |
| Audit reconsideration | After assessment, with information the examiner never saw | Free to request; collection isn't automatically paused while it's reviewed |
| Short-term payment plan | Balance you can pay within 180 days | $0 setup; interest and the 0.5%/month late-pay penalty continue |
| Installment agreement | Streamlined up to $50,000 over up to 72 months online | Setup fee applies; interest continues until paid |
| Penalty relief | Clean 3-year history (failure-to-pay penalty) or documented reasonable cause (including the accuracy penalty) | Free to request; the Automatic Exemption from Penalty covers eligible returns processed after summer 2026, and earlier 2025 returns still need an FTA request |
| Offer in Compromise | Assets plus future income below the balance; means-tested | $205 fee (waived for low-income filers); the IRS accepted roughly 1 in 5 offers in FY2024 |
| Currently Not Collectible | Paying anything would create documented hardship | Pauses collection; the debt, interest, and possible lien remain |
The ordering matters more than the menu. Dispute what's wrong first. An appeal that knocks $6,000 off the assessment beats any payment plan on the full amount. Then attack penalties. Only then size a plan or offer to whatever is left.
How to respond when the IRS audits an old return, step by step
- Confirm the year is open. Find the date you filed that return and add three years. If the letter targets a year past that date, assessment may already be barred unless the 6-year or unlimited rules apply.
- Pull your transcripts. Download the account transcript and the wage and income transcript for every year the letter names, so you can see exactly what the IRS sees before you answer.
- Respond by the date printed on the letter. Audit letters carry a real response deadline. Miss it and the IRS decides the year on its own numbers, then assesses.
- Answer only what the letter asks. Send records for the year and items in question. Volunteering extra years, extra accounts, or unrequested documents can widen the exam.
- Resolve any balance before it reaches collections. If the exam ends in tax due, line up an appeal, penalty relief, or a payment arrangement before the assessment rolls into the CP14 collection sequence.
On step one, the statute defense is real and examiners respect it, but it must be raised. The IRS won't volunteer that a year is closed. A signed return date, a certified-mail receipt, or your account transcript's filing entry is the proof that closes the conversation.
How do you check whether an old year is already under review?
Your IRS account transcript shows audit activity weeks before any letter arrives, coded in three digits down the left column.
Pull the account transcript for each year you're worried about (free through your IRS online account) and scan for these:
| Code | What it means | What to do |
|---|---|---|
| 424 | Exam request; the return was pulled for potential audit | Gather that year's records now; many 424s close with no exam, but be ready |
| 420 | Audit indicator; an examination is underway (see our Code 420 guide) | Watch the mail for Letter 566 or 2205-A; don't amend the year while it's under exam |
| 922 | Underreporter review; a document mismatch, the Code 922 CP2000 track | Compare your wage & income transcript against the return to find the mismatch first |
| 560 / 872 notation | The assessment statute date was extended by consent | Confirm what you signed and what date now controls |
| 300 | Additional tax assessed by examination; the audit closed with a balance | Move to the options table above: appeal window, reconsideration, or resolution |
No codes, no open letters, and the year is past its window? It's closed. That's the answer most people checking their transcripts get, and it's worth having in writing before you spend another night worrying about it.
If a code on your transcript or a letter in your mailbox just told you an old year is live, a free case review at (888) 825-7779 (or the 2-minute form) can tell you in one conversation whether the statute protects that year and what to send if it doesn't.
What to check on an old year, and the red flags
- The filing date, not the tax year. Add three years to the later of the filing date or the due date. That is the line, and February filers get no head start.
- Unfiled years. No return means no statute. A substitute for return doesn't start one either.
- A big gap in gross receipts. More than 25% of gross income left off, or more than $5,000 of foreign-asset income, moves the year to 6 years.
- ERC quarters from 2021. Those carry a 5-year window and are still being opened.
- A Form 872 in the envelope. Signing extends the statute. Refusing usually brings an immediate notice of deficiency. Decide on purpose.
- Questions drifting toward "where did this money come from." That shift can signal fraud development, and it is the point to stop answering alone.
- Code 424 or 420 or 922 on the transcript. Activity is already underway, even if no letter has arrived.
- Amending a year under exam. Don't. It crosses wires with the examiner.
Does the federal clock protect you from a state audit?
No. Every state sets its own audit window, and the federal 3-year rule does not carry over.
California's Franchise Tax Board, for example, generally works on a four-year window from the date you file, a full year longer than the IRS. An unfiled state return stays open indefinitely, just like federal. Most states also require you to report federal audit changes within a set period. That report (or the IRS's own data sharing) can reopen a state year that had otherwise closed. So a federal exam that ends in an assessment often produces a second, state bill months later. When the exact window matters for your state, confirm it with the agency directly rather than assuming it mirrors the IRS.
Can you handle this yourself?
Most statute questions and many small exams are self-serve.
You likely don't need professional help if you're only checking whether an old year is still open (transcript plus the 3-year math answers it), you got a correspondence audit on a single, well-documented item like a credit or a 1099 mismatch, or the exam ended in a small balance you can pay within 180 days on a $0-setup short-term plan. The IRS's own overview of the process at IRS.gov's audit page is readable, and plans are set up directly at the IRS payment plans page.
Experienced help reliably changes outcomes in a narrower set of situations: an exam probing unreported income (where a bank-deposit reconstruction is on the table and answers can widen the case), multiple unfiled years with no statute protection at all, a Form 872 extension request you're not sure how to answer, an IRS audit with no receipts where records must be lawfully reconstructed, business or payroll years including ERC claims, and any exam where the examiner's questions drift from "show me the deduction" toward "explain where this money came from." That last shift matters. It can signal fraud development, and what you say there is not a DIY moment. If you're stuck between the exam function and collections, the Taxpayer Advocate Service is a free, independent escalation path.
Terms on your audit paperwork, decoded
- Assessment: the formal recording of tax on your IRS account, the moment a proposed audit change becomes a legally collectible debt.
- Statute of limitations (ASED): the Assessment Statute Expiration Date, the last day the IRS can assess additional tax for a year. The 3-year, 6-year, and unlimited rules all set this date.
- Substantial omission: leaving more than 25% of gross income (or over $5,000 of foreign-asset income) off a return, the trigger that doubles the window to 6 years.
- Form 872: the consent form extending the assessment deadline; signing it is voluntary and negotiable, and refusing it usually triggers an immediate notice of deficiency.
- Substitute for Return (SFR): a return the IRS prepares for a non-filer using only reported income and no deductions. It creates a bill and never starts the audit clock.
- CSED: the Collection Statute Expiration Date, a separate 10-year clock to collect that starts only after assessment, never after filing.
The bottom line on how far back the IRS can audit
Three years from the later of filing or the due date is the rule for most people. Six years if more than 25% of gross income was left off. No limit for fraud or a year that was never filed. Find your filing dates, pull the transcripts, and raise the statute yourself when a year is closed, because nobody at the IRS will raise it for you. For the years that are still open, answer the letter by its printed date and send only what it asks for.
How far back can the IRS audit: your questions, answered
Can the IRS audit you after 10 years?
Almost never for a filed, non-fraudulent return — the audit window closes after 3 years, or 6 years for a substantial omission, long before the 10-year mark. The 10-year figure people remember is the collection statute: once tax is assessed, the IRS has 10 years to collect it. A year you never filed, though, stays open to audit indefinitely, no matter how old it is.
Can the IRS audit me for a return from 7 years ago?
Only in limited situations. A 7-year-old return you filed on time is past both the 3-year and 6-year windows, so an ordinary audit is barred. The exceptions are fraud, a return that was never filed, a Form 872 extension you signed that kept the year open, or certain ERC payroll claims that carry their own 5-year assessment window.
Does filing an amended return restart the audit clock?
No — an amended return does not restart the 3-year statute, which keeps running from the original filing. There is one narrow exception: if you file an amended return showing additional tax within 60 days of the statute expiring, the IRS gets 60 extra days to assess that additional tax. Amending can, however, draw a second look at the year, so time and document any amendment carefully.
How far back can the IRS audit if you never filed a return?
Forever. The 3-year clock only starts when a return is filed, so an unfiled year has no audit statute at all — the IRS can examine and assess it 5, 10, or 20 years later. Even a substitute for return the IRS prepares on your behalf does not start the clock. Filing the missing return yourself is the only thing that ever starts it.
What triggers the 6-year audit window?
Omitting more than 25% of the gross income shown on your return, omitting more than $5,000 of income tied to foreign financial assets, or overstating the cost basis of something you sold so your reported gain shrank. On a joint return, the 25% test applies to both spouses' combined gross income, and for a business, gross income generally means total receipts before expenses — which makes the threshold easier to cross than most owners expect.
Should I sign Form 872 to extend the audit statute?
It depends on what refusing would cost you. If you refuse, the IRS typically protects itself by issuing a notice of deficiency based on its current numbers, often the worst-case version of your bill. Signing buys time to document your position, but keeps the year open. A restricted consent that limits the extension to specific issues or a fixed date is often the smarter middle ground, and it is negotiable.
How will I know if the IRS is auditing an old year?
You will get a letter by postal mail — typically Letter 566 for a correspondence audit or Letter 2205-A for an appointment exam — naming the tax year and the items under review. The IRS does not open audits by phone call, text, or email. You can also see audit activity early on your account transcript: code 424 means the return was pulled for exam, and code 420 means an audit is underway.
How long should I keep my tax records?
Keep everything at least 3 years from filing, and 6 to 7 years if you are self-employed, have investment sales, or have any underreporting risk. That covers the 6-year window plus margin. Keep records that prove the cost basis of property for as long as you own it plus 3 years after you sell. For any year you never filed, keep the records indefinitely, because that year never closes.
Do state tax agencies follow the IRS 3-year audit rule?
Not automatically — every state sets its own window. California's Franchise Tax Board, for example, generally has four years from the date you file. An unfiled state return stays open indefinitely, just like federal. Many states also require you to report federal audit changes, which can reopen a state year that had already closed. When the exact window matters, confirm it with your state agency rather than assuming the federal rule applies.
Does the 3-year rule apply to ERC claims?
No — Congress gave the IRS a longer, 5-year assessment window for Employee Retention Credit claims from certain 2021 quarters, which is why ERC exams are still opening on payroll returns that feel old. If your business claimed the ERC, treat those quarters as open even if your income tax years from the same period have closed. The two statutes run separately.
Your next 24 hours
- Find the filing date for the year you're worried about. Check your records or your IRS online account, then do the math: filing date (or the April due date, if you filed early) plus 3 years. That one calculation answers most of this article for your situation.
- Gather the paper. Any IRS letter you've received, the return for each year in question, and the 1099s, W-2s, and bank statements behind it: organized by year, in one folder, before anyone asks.
- Get the free case review. If a letter has arrived, an exam is showing on your transcript, or an omission you've found could cross the 25% line, call (888) 825-7779 or use the 2-minute form. Interest on any old-year balance has been running since that return's original due date. The review costs nothing, and knowing where you stand does too.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.