
Free IRS Help
How to Contact the Taxpayer Advocate Service in 2026: Phone, Form 911, and Local Offices
Read the transcript
Host: You sent the documents. You called the number on the letter. You waited the sixty days they promised — and then you waited another sixty. And nothing. Meanwhile there's a levy running. So where does somebody go with that?
Tax specialist: Taxpayer Advocate Service. It's an independent organization inside the IRS, and its whole job is unsticking cases the normal IRS machinery has failed. It's free. There's at least one office in every state, plus D.C. and Puerto Rico.
Host: Free free? Or free-with-an-asterisk?
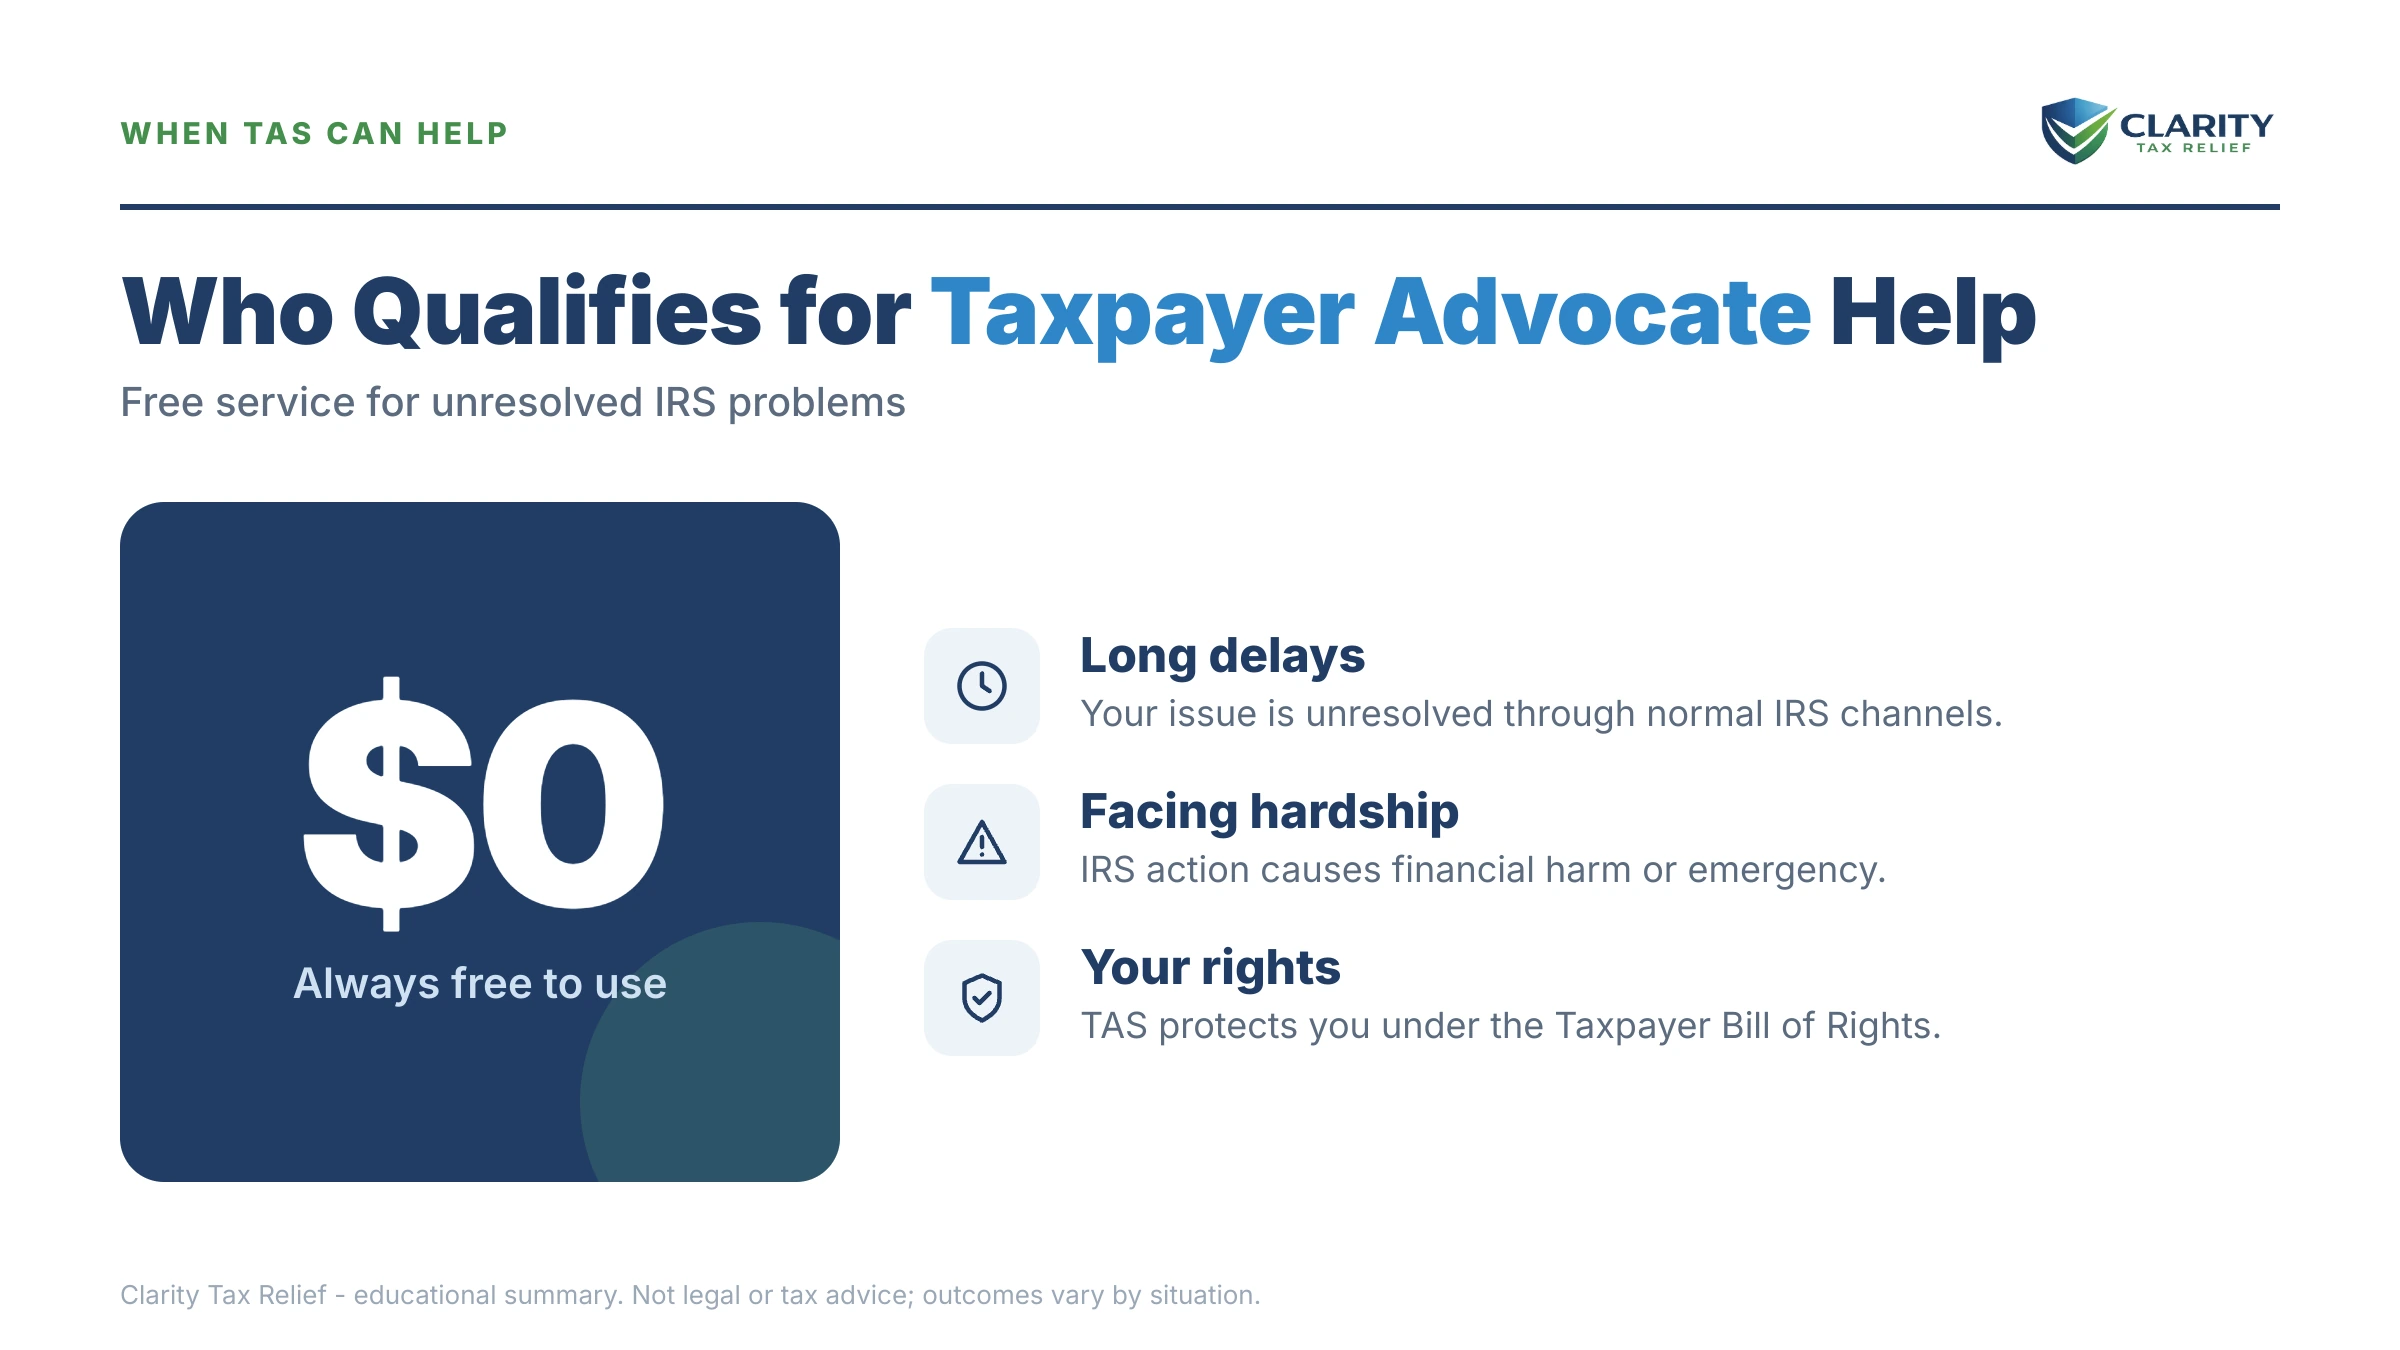
Tax specialist: Free. Doesn't matter what your income is or how much you owe. There's no fee for the form. And I'd add — if anyone tells you they can get you into the Taxpayer Advocate program for a fee, that's something you can do yourself in an afternoon.
Host: Okay. What's the number?
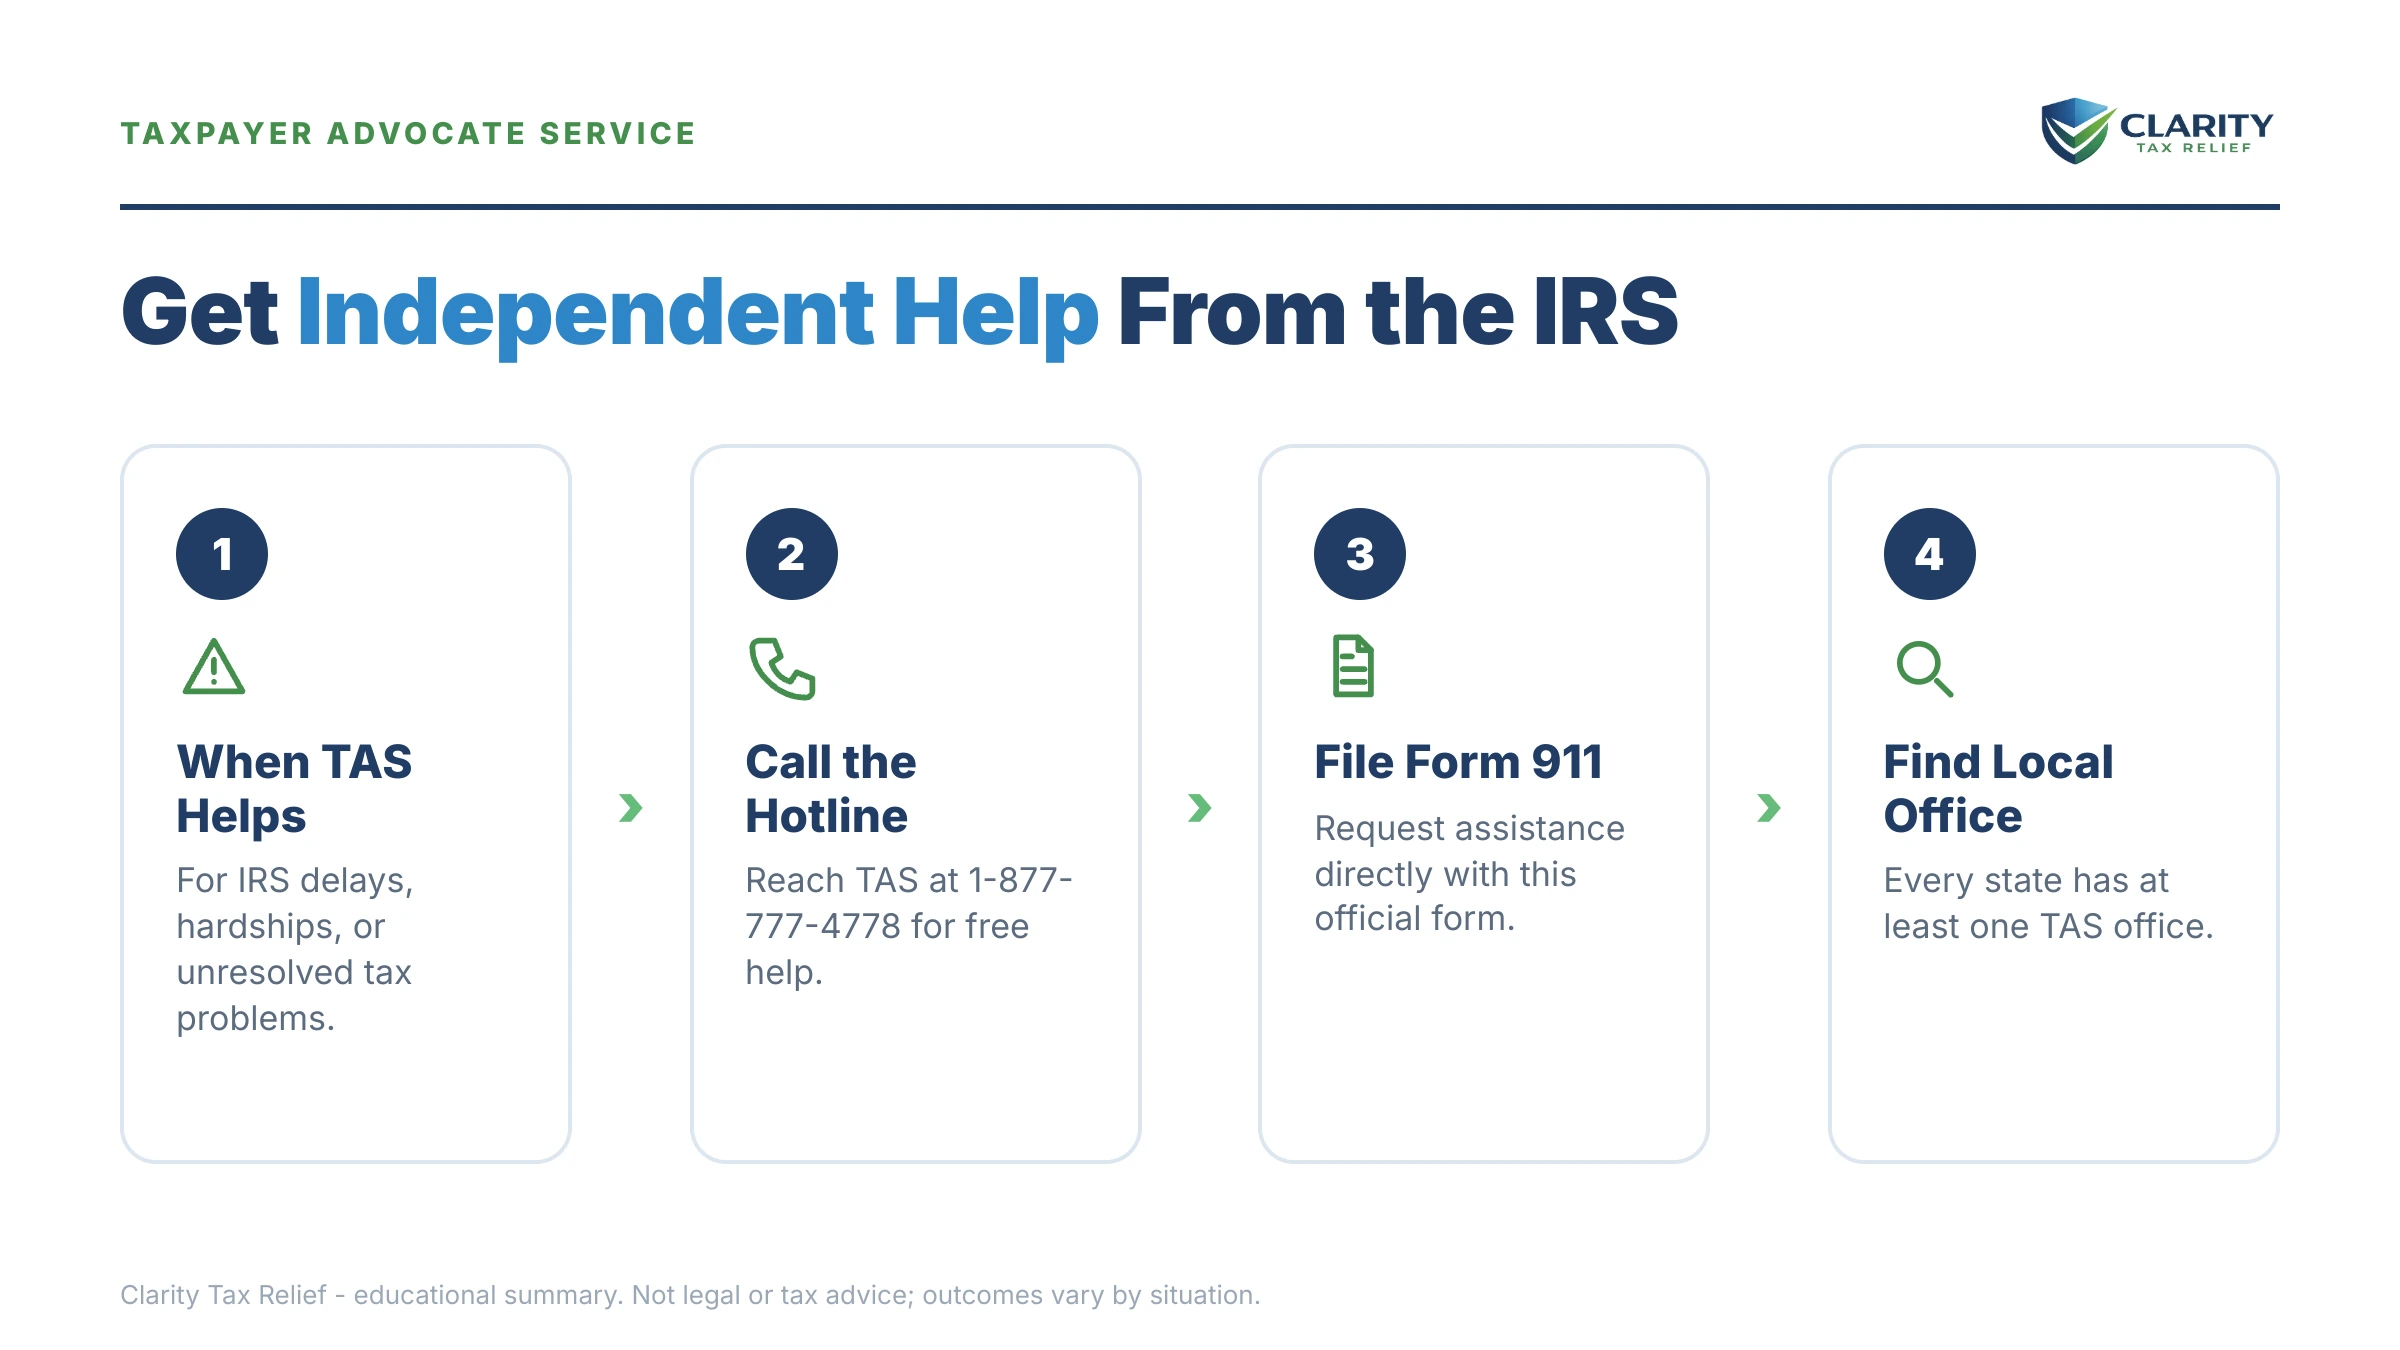
Tax specialist: National intake line, 1-877-777-4778.
Host: 1-877-777-4778.
Tax specialist: That's it. But honestly, in 2026 the written route usually beats the phone. The national line carries the same staffing strain as the rest of the IRS. The workforce is down roughly twenty-seven percent from the 2025 cuts.
Host: So the written route is — what, a form?
Tax specialist: Form 911. Request for Taxpayer Advocate Service Assistance. You fax or mail it to your state's TAS office — and I want to underline state's office. Not a general IRS address. A 911 mailed to the wrong place is the most common self-inflicted delay there is.
Host: How do I find my state's office?
Tax specialist: taxpayeradvocate.irs.gov. There's an office lookup — fax number, mailing address, phone. And fax if you can, because you get a dated transmission record you can point to later.
Host: Hm. Okay, before we go further — does everybody get in? Because I can imagine a listener thinking, great, I'll just—
Tax specialist: No. And this is the part I really want people to hear. TAS is deliberately narrow. It's not a faster customer service queue, it's not an appeals office, and it is not a place to argue that you shouldn't owe the tax.
Host: So what gets in?
Tax specialist: Roughly four situations. One, economic hardship — an IRS action or delay is causing immediate financial harm, and you can document it. Two, IRS delay more than thirty days beyond normal processing time. Three, no response by a date the IRS promised you. Four, a system or process failure, or one of your rights being ignored.
Host: Give me the fourth one in plain terms.
Tax specialist: Two IRS units contradicting each other. Payments posting to the wrong year over and over. Collection continuing on an account that should be on hold. That kind of broken.
Host: And if none of those fit? If I just owe money and I want a payment plan?
Tax specialist: Then they route you back to normal channels. A case that's merely slow, with no hardship and no missed promise behind it — that usually goes back to the phone line.
Host: Right.
Tax specialist: There's a thing I need to flag that trips people up badly, though. TAS never pauses your IRS deadlines.
Host: Wait. Say that again.
Tax specialist: Bringing in an advocate does not stop the clock on a statutory deadline. The thirty-day window to request a Collection Due Process hearing after an LT11 keeps running. The ninety-day window to petition Tax Court after a Notice of Deficiency keeps running. Both of them, while your case is being worked.
Host: So the order matters.
Tax specialist: The order matters. Protect the deadline first — file Form 12153 for the CDP hearing, file the petition, file the appeal — then bring in the advocate.
Host: Form 12153 for the CDP hearing. Got it. And there's no deadline to contact TAS itself?
Tax specialist: Correct. No deadline on that side. It's your own rights that expire, and they don't wait for the IRS to answer its phone.
Host: Let's do the example in the article, because I think it makes this concrete. There's a divorce case in there.
Tax specialist: Yeah, and it's a hypothetical — the article's illustration, not a real client. Recently divorced. The IRS is collecting fifty-four thousand six hundred dollars from three joint returns the ex-spouse controlled. Innocent spouse relief was requested five months ago on Form 8857. IRS acknowledged it, promised a response within sixty days, went silent. And a continuous wage levy has started.
Host: Okay, so what's the arithmetic?
Tax specialist: Take-home is fifty-two hundred a month. The levy takes about fourteen hundred, so thirty-eight hundred is left. Documented essentials — rent, utilities, car, insurance, food for the parent and one child — run forty-six fifty.
Host: So that's an eight hundred fifty dollar hole.
Tax specialist: Eight hundred fifty a month you cannot cover. Two more levy cycles and rent gets missed. And that arithmetic, written plainly on the 911 with the lease and the levy notice attached, hits two acceptance criteria at once — the hardship, and the blown sixty-day promise.
Host: And what does TAS actually do with that?
Tax specialist: You'd ask for something specific. Release the wage levy under the economic hardship rule while the innocent spouse claim is pending. TAS can press for exactly that. What it does not do — it doesn't decide the innocent spouse claim, and it doesn't touch the fifty-four six. That number gets decided by the innocent spouse determination.
Host: So it stops the bleeding.
Tax specialist: It stops the bleeding and forces the IRS to work the file. That's the honest framing.
Host: What's the ceiling on their power? Like, what can't they do at all?
Tax specialist: They can't reduce a tax you legally owe. Can't extend a statutory deadline. Can't overturn an audit result — that's Appeals or Tax Court. Can't give legal advice. What they can do is real, though: assign you one named case advocate with a direct phone number, force a stalled unit to work your file, expedite hardship refunds, push for levy releases, fix misapplied payments, and in stubborn cases issue a Taxpayer Assistance Order.
Host: Which is what, exactly?
Tax specialist: A formal order directing the IRS to take, or stop taking, a specific action on your account. No private company can do that. Neither can you from the general IRS line.
Host: How long does all this take?
Tax specialist: Varies with caseload, and TAS doesn't publish a timeline. Hardship cases get triaged first, which is exactly why documenting the hardship on the form matters so much. Expect the underlying fix to run weeks to months depending on what's broken.
Host: And while I'm waiting, the machine keeps going.
Tax specialist: It does. The failure-to-pay penalty adds half a percent a month, interest compounds daily. The notice sequence advances — a first bill becomes reminders, then a CP504 intent to levy your state refund, then an LT11 final notice. After that window closes, wage levies and bank levies can start without another warning.
Host: CP504 then LT11. Okay. One more thing — the article mentions clinics as a different door.
Tax specialist: Low Income Taxpayer Clinics. Independent, income-qualified, and they represent you in disputes — audits, appeals, Tax Court, innocent spouse. So different problem. Use TAS when the IRS is broken or unresponsive. Use a clinic when you're fighting the amount itself. Plenty of people use both.
Host: And honestly — most people can file the 911 themselves, right?
Tax specialist: If it's one broken thing, yes. A frozen refund past every published timeframe, a payment in the wrong year, one levy causing provable hardship — Form 911 in an afternoon, fax it, manage the advocate relationship yourself. It was built for that. Where it gets harder is when TAS is one move in a longer game. Multiple unfiled years, a big joint liability where the innocent spouse strategy decides who owes what, or a case where releasing the levy just restarts collection because nothing's standing behind it.
Host: The advocate fixes the process—
Tax specialist: —and somebody has to fix the position. Right.
Host: So next twenty-four hours. What does a listener do?
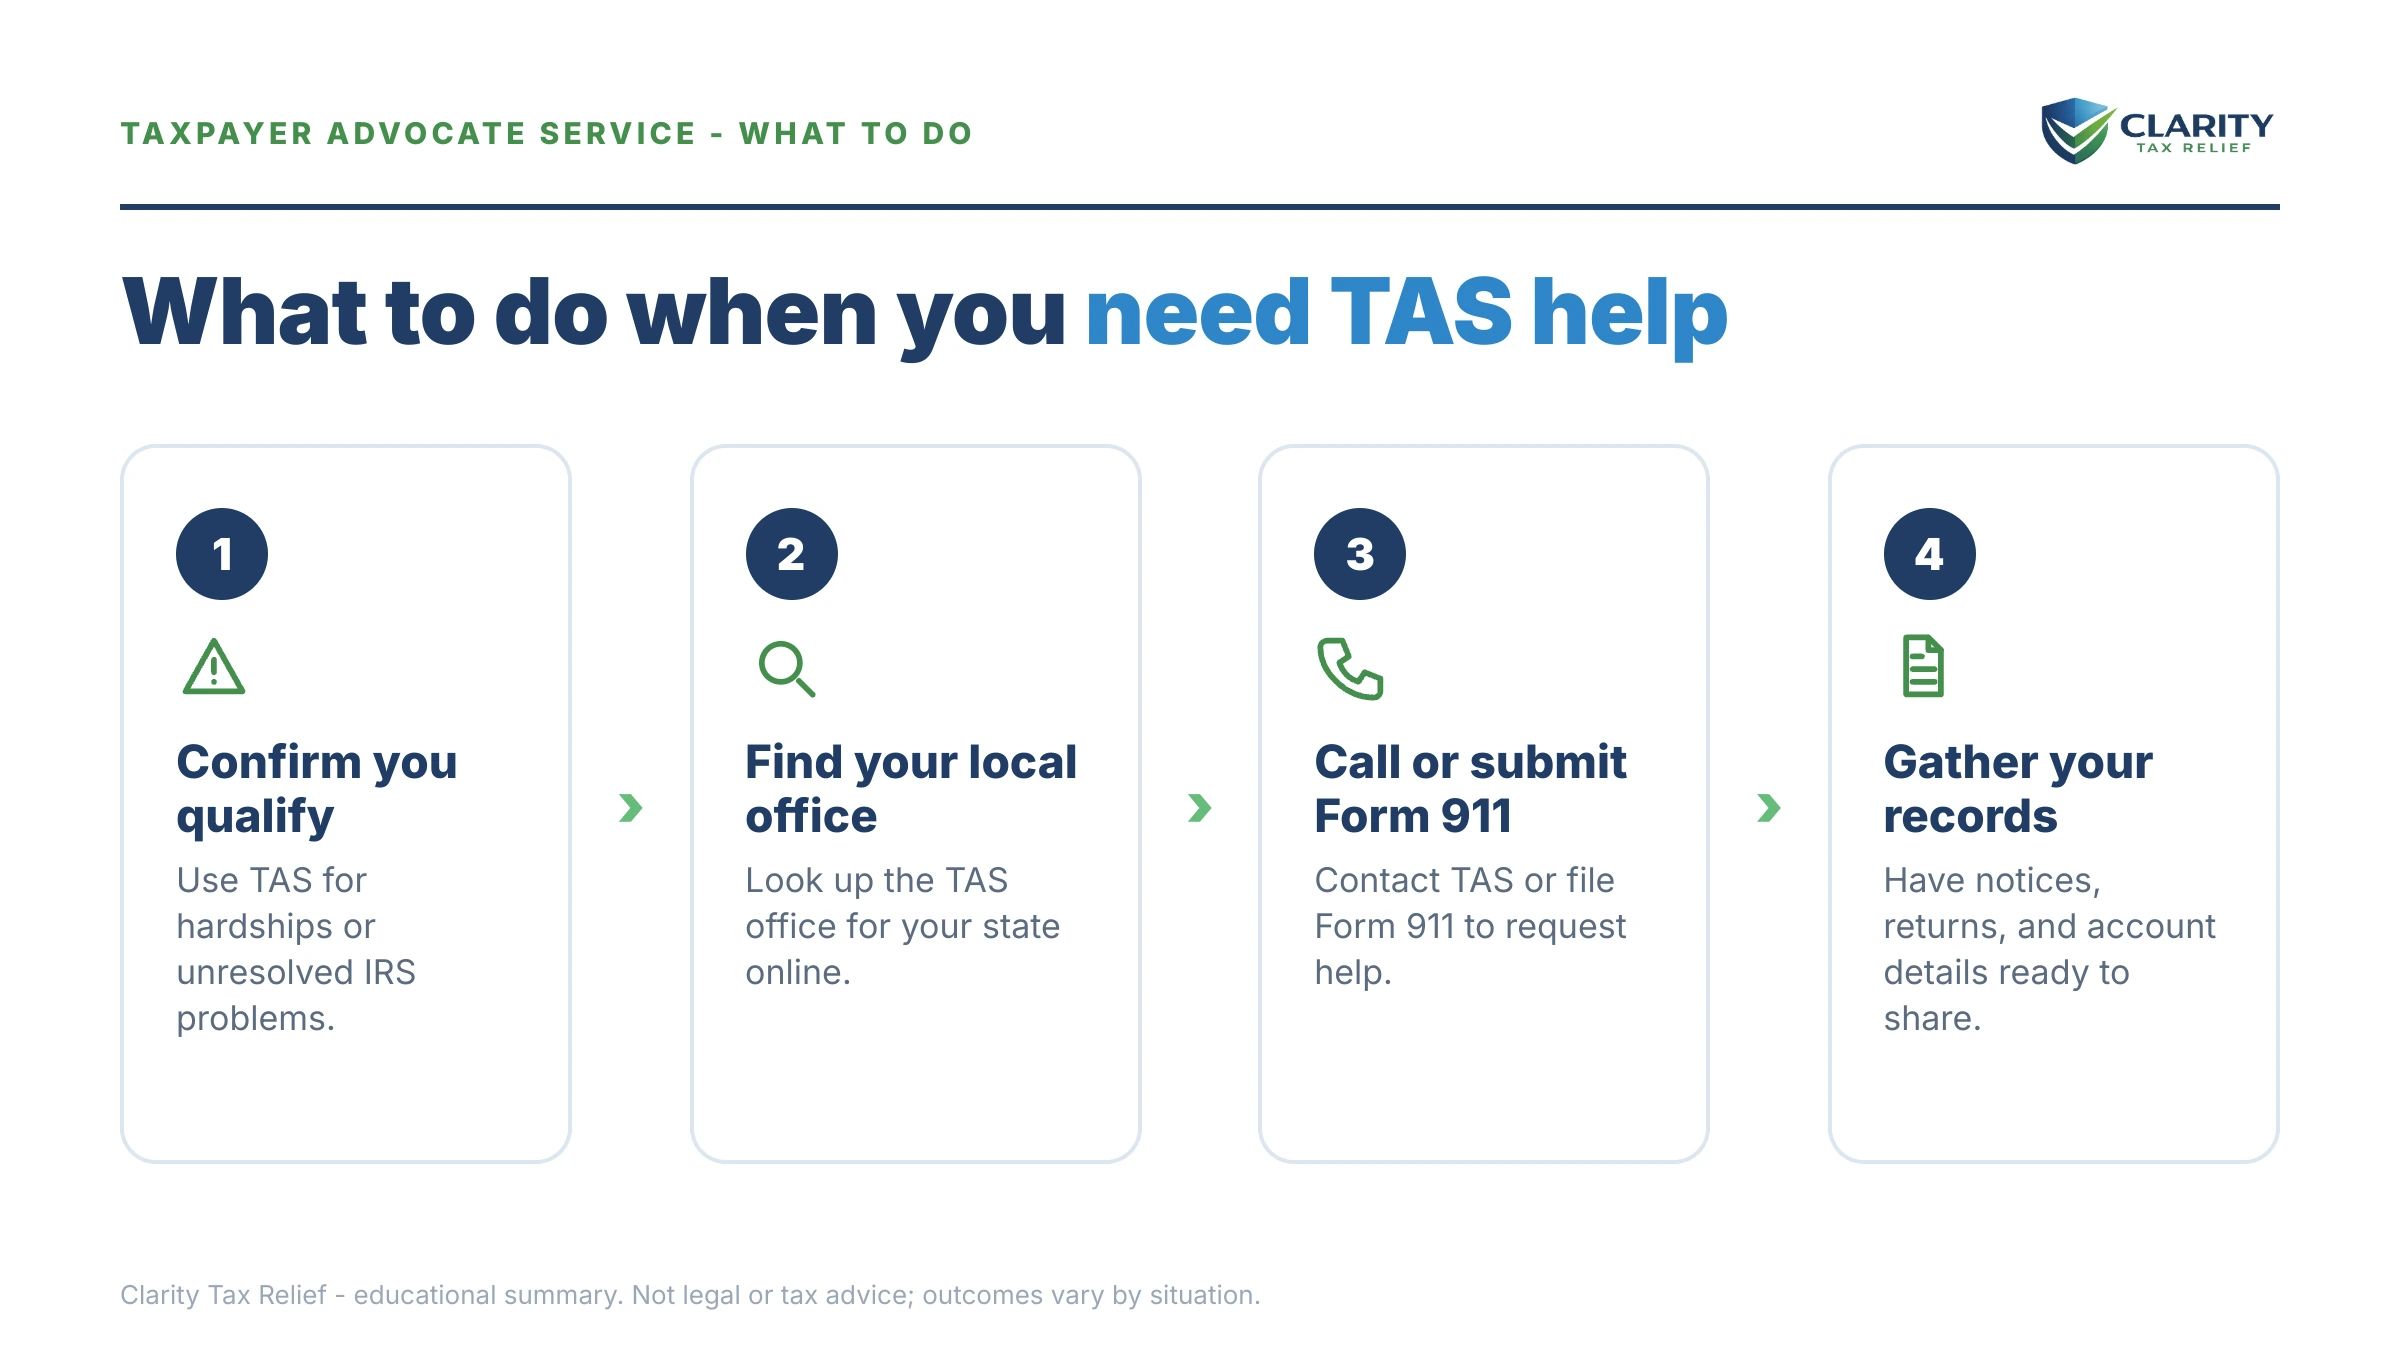
Tax specialist: Pull the dates. The most recent notice, and any letter promising you a response. Those two dates anchor the whole form. Then gather proof — last year's return, every notice, a log of your calls, and the hardship documentation: levy paperwork, the lease, shutoff notices, bank statements showing the shortfall.
Host: And if someone wants a second set of eyes before they send it?
Tax specialist: Clarity's Enrolled Agents will do a free case review — whether the facts line up with the TAS criteria, what belongs in the description-of-problem section, and what needs fixing underneath it. (888) 825-7779.
Host: (888) 825-7779. And one last thing — if you're already on the phone with an IRS employee today, you can just ask, right?
Tax specialist: You can. The sentence is: I'm requesting a referral to the Taxpayer Advocate Service. Employees are required to route qualifying cases.
The short answer: to contact the Taxpayer Advocate Service, call 1-877-777-4778 or fax/mail Form 911 to your state's local TAS office (find it at taxpayeradvocate.irs.gov). TAS help is free — but it only accepts cases involving economic hardship, an IRS delay past 30 days, or a broken IRS process.
If you're researching how to contact the Taxpayer Advocate Service, you've probably already done everything you were supposed to do: sent the documents, called the number on the letter, waited the "60 days" you were promised — twice. Maybe a divorce left you holding a joint balance while your innocent spouse claim sits in a queue nobody can see into. There's a real path around the wall, and it starts with one form.
That form is Form 911, and how you fill out its "description of problem" section largely decides whether TAS takes your case. The visual guide below maps the deadlines, contact options, and steps, so keep reading before you download it.
⏱ The clock to watch: there is no deadline to contact TAS — but TAS never pauses your IRS deadlines. The 30-day window to request a Collection Due Process hearing and the 90-day Tax Court window keep running while your case is worked. Protect any deadline first (file Form 12153 for a CDP hearing if you have levy rights expiring), then bring in the advocate.
Why you'd contact the Taxpayer Advocate Service — and why it isn't a complaint line
The Taxpayer Advocate Service is an independent organization inside the IRS that unsticks cases the normal IRS machinery has failed — for free. It has at least one office in every state, plus the District of Columbia and Puerto Rico, and it answers to the National Taxpayer Advocate, not to IRS collections or examination.
That independence is the whole point. Your case advocate can reach into IRS systems, demand action from the unit sitting on your file, and — in stubborn cases — issue a Taxpayer Assistance Order directing the IRS to act or stop acting. No private company can do that, and neither can you from the general IRS phone line.
But TAS is deliberately narrow. It is not a faster customer-service queue, not an appeals office, and not a way to argue that you shouldn't owe the tax. It takes cases in roughly four situations:
| TAS accepts your case when… | What it looks like in practice |
|---|---|
| Economic hardship — an IRS action or delay is causing immediate financial harm | A levy or frozen refund means you can't cover rent, utilities, medical care, or basic living costs — and you can document it |
| IRS delay — more than 30 days beyond normal processing time | An amended return, innocent spouse claim, identity-theft case, or penalty request has sat with no movement well past the published timeframe |
| No response by a promised date | The IRS told you "you'll hear from us within 60 days" — that date passed and nothing came |
| A system or process failure, or a taxpayer right being ignored | Two IRS units contradict each other, payments post to the wrong year repeatedly, or collection continues on an account that should be on hold |
If none of those fit — you simply owe money and want a payment arrangement — TAS will route you back to normal channels. For that situation, start with our guide to how to settle tax debt yourself instead; it covers payment plans, hardship status, and offers in one place so this article doesn't have to.
What happens while you wait: the IRS machine doesn't pause
IRS collection notices are generated by automated systems that keep escalating whether or not a human ever answers your calls. In 2026, with the IRS workforce down roughly 27% from the 2025 cuts, the humans are scarcer than ever — but the notice stream, the liens, and the levies never stopped. "I couldn't get through" is the single most common story TAS hears, and here is what it costs while it goes unfixed:
- The balance grows monthly. The failure-to-pay penalty adds 0.5% per month and interest compounds daily on top of it — on hold or not.
- The notice sequence advances. A first bill becomes reminder notices, then a CP504 intent to levy your state refund, then an LT11 final notice — each with more enforcement power than the last.
- Enforcement begins. After the final notice window closes, wage levies (continuous until released) and bank levies (a 21-day hold, then the money leaves) can start without another warning.
- Rights expire. The 30-day CDP window and the 90-day Tax Court window don't wait for the IRS to answer its phone — miss them and you lose your strongest review rights.
This is exactly the gap TAS exists to close: when the agency's own dysfunction is about to cost you money or rights, the advocate is the pressure valve Congress built into the system.
Stuck between an unresponsive IRS and a growing balance?
A TAS request works best when it's paired with an actual resolution plan — otherwise the same problem comes back. Get a free case review from an experienced tax professional: we'll tell you whether your case fits TAS criteria, what to put on Form 911, and what to fix underneath it. Call (888) 825-7779 or use the 2-minute form.
Every way to reach the Taxpayer Advocate Service, compared
There are four ways into TAS, and in 2026 the written route usually beats the phone. The national intake line carries the same staffing strain as the rest of the IRS; a faxed Form 911 lands directly at your state's office with a dated transmission record attached.
| Method | Best for | What you need |
|---|---|---|
| Call the national line: 1-877-777-4778 | A first conversation — screening whether your case qualifies before you write anything | Your SSN or ITIN, the notice in front of you, and a one-minute summary of what the IRS has and hasn't done |
| Fax or mail Form 911 to your local TAS office | Hardship cases and anything you want on the record — the strongest, most trackable route | Completed Form 911 plus proof of harm: levy paperwork, shutoff or eviction notices, the promised-response letter the IRS missed |
| Contact your state's local TAS office directly | Complex or multi-year messes; every state has at least one office | The office phone, fax, and address from the lookup at taxpayeradvocate.irs.gov |
| Ask any IRS employee for a TAS referral | You're already on an IRS call and hitting a wall | The sentence: "I'm requesting a referral to the Taxpayer Advocate Service" — employees are required to route qualifying cases |
Fax Form 911 to your state's TAS office rather than a general IRS address — a 911 mailed to the wrong place is the most common self-inflicted delay. If you're unsure any letter you're responding to is genuine in the first place, verify it against our guide to how to tell if an IRS letter is real before you send anyone your information; TAS itself never initiates contact by email or text.
What if you don't qualify for TAS?
TAS is one of several free doors, and picking the right one saves weeks. Here's how the alternatives stack up:
| Option | Cost | Best fit |
|---|---|---|
| Taxpayer Advocate Service | Free | The IRS is broken, unresponsive, or causing hardship — and you can document it |
| Low Income Taxpayer Clinic | Free or nominal, income-qualified | You're disputing what the IRS says you owe — audits, appeals, Tax Court, innocent spouse |
| Calling the IRS directly | Free (plus your time) | Routine fixes on a working account — payment plans, transcript requests, address changes |
| Your congressional representative's casework office | Free | A stalled case with a sympathetic story — congressional inquiries get formal IRS responses |
| An experienced tax professional | Fees vary by case | Multiple years, active enforcement, or resolution strategy — the "what should I actually do" layer TAS doesn't provide |
The clinic route deserves its own look if money is tight and you're fighting the amount itself — see our guide to Low Income Taxpayer Clinics — and the full menu is in free help with IRS tax debt.
How to contact the Taxpayer Advocate Service, step by step
A complete, well-documented Form 911 is the difference between acceptance and a polite referral back to the phone line. Here is the sequence that works:
- Confirm your case fits TAS criteria. Check that you can honestly claim economic hardship or a documented IRS breakdown — a delay past 30 days beyond normal processing, a missed promised-response date, or a system failure. If neither applies yet, work normal IRS channels first.
- Build your paper trail. Gather every IRS notice, the dates of every call you made, any response date the IRS promised, and proof of the harm — levy paperwork, an eviction or shutoff notice, medical bills. Specific dates and dollar amounts are what get a Form 911 accepted.
- Complete Form 911. Download Form 911 from irs.gov and fill in your identifying information, a factual description of the problem with dates, and the specific relief you are requesting — for example, release of a wage levy causing hardship while an innocent spouse claim is pending.
- Submit it to your local TAS office. Fax or mail the completed Form 911 to the TAS office for your state, found through taxpayeradvocate.irs.gov — or call 1-877-777-4778 and open the request by phone. Fax creates the best dated record.
- Respond fast when your case advocate calls. If accepted, you are assigned one named case advocate with a direct line. Answer their document requests within the short deadlines they set — a stalled response from you is the fastest way to lose the momentum you just created.
For a box-by-box guide to the form itself — including how to word the "relief requested" line — see our full Form 911 walkthrough. If your problem involves old tax years and missing paperwork, pull your income records first using how to get old W-2s for back taxes so your 911 tells a complete story.
A worked example: $54,600, a divorce, and a levy nobody at the IRS will discuss
Say you're recently divorced and the IRS is collecting $54,600 from three joint returns your ex-spouse controlled. You filed Form 8857 requesting innocent spouse relief five months ago; the IRS acknowledged it, promised a response "within 60 days," and went silent. Meanwhile a continuous wage levy has started. This hypothetical is close to the textbook TAS case — here's why the math qualifies:
- Your take-home pay is $5,200/month. The levy is taking roughly $1,400/month, leaving you $3,800.
- Your documented essentials — rent, utilities, car, insurance, food for you and one child — run $4,650/month.
- Shortfall: $4,650 − $3,800 = $850/month you cannot cover. Two more levy cycles and you miss rent.
That arithmetic, written plainly on Form 911 with the lease and the levy notice attached, hits two acceptance criteria at once: economic hardship (the $850 monthly shortfall) and a missed promised date (the 60-day letter, now three months stale). The relief requested would be specific: release the wage levy under the economic-hardship rule while the pending innocent spouse claim is decided. TAS can press for exactly that — the mechanics of hardship releases are covered in our guide to a levy causing hardship.
Notice what TAS does not do in this example: it doesn't decide the innocent spouse claim, and it doesn't erase the $54,600. It stops the bleeding and forces the IRS to work the case. Whether you ultimately owe $54,600, half of it, or none of it is decided by the innocent spouse determination — which is why pairing the TAS request with a strategy for the underlying claim matters.
What the Taxpayer Advocate can and can't do
TAS has real power inside the IRS and zero power over the law itself. Set your expectations accordingly:
TAS can: assign you one named advocate with a direct phone number; force a stalled unit to work your file; expedite hardship refunds (including an offset bypass refund in genuine hardship); push for levy releases; fix misapplied payments and account errors; and issue a Taxpayer Assistance Order when the IRS won't move.
TAS can't: reduce a tax you legally owe, extend a statutory deadline, overturn an audit result (that's Appeals or Tax Court), give legal advice, or prioritize a case that's merely slow with no hardship or missed promise behind it. It also can't make the underlying resolution decision for you — payment plan versus hardship status versus offer is still your call to get right.
When you can handle this yourself — and when help changes the outcome
Contacting TAS is genuinely a do-it-yourself task for most people. If your situation is one broken thing — a refund frozen past all published timeframes, a payment posted to the wrong year, one levy causing provable hardship — you can complete Form 911 in an afternoon, fax it, and manage the advocate relationship on your own. TAS was built for exactly that, and it costs nothing.
Experienced help changes the outcome when TAS is only one move in a longer game: a levy in motion on top of multiple unfiled years, a $54,600 joint liability where innocent spouse strategy decides who owes what, or a case where releasing the levy just restarts collection unless a payment plan, hardship status, or offer is stood up behind it. In those cases the advocate fixes the process — a professional fixes the position. If unfiled years are part of your tangle, understand the stakes first via how long can you go without filing taxes.
Terms on Form 911 and TAS letters, decoded
- Form 911 — the Request for Taxpayer Advocate Service Assistance; the application that opens a TAS case.
- Case advocate — the single TAS employee assigned to your case, with a direct phone number — your one consistent human inside the IRS.
- Taxpayer Assistance Order (TAO) — a formal order the advocate can issue directing the IRS to take, or stop, a specific action on your account.
- Economic hardship — the TAS (and levy-release) standard meaning you can't meet basic, reasonable living expenses — not merely that paying is painful.
- Systemic issue — a problem affecting many taxpayers, not just you; reportable to TAS through its Systemic Advocacy portal even if you have no individual case.
- LITC — Low Income Taxpayer Clinic; an independent, income-qualified clinic that represents you in disputes, distinct from TAS.
Taxpayer Advocate Service questions, answered
What is the Taxpayer Advocate Service phone number?
The national Taxpayer Advocate Service intake line is 1-877-777-4778. Every state, plus the District of Columbia and Puerto Rico, also has at least one local TAS office you can call or send Form 911 to directly — the office lookup is on taxpayeradvocate.irs.gov. In 2026, faxing Form 911 to your local office often moves faster than waiting in the national phone queue.
Is the Taxpayer Advocate Service free?
Yes — TAS is completely free, no matter your income or how much you owe. It is an independent organization inside the IRS, funded by Congress, and there is no application fee for Form 911. Anyone who asks you to pay to "get you into" the Taxpayer Advocate program is selling you something you can do yourself in an afternoon.
Will the Taxpayer Advocate Service take my case?
TAS accepts cases that meet its criteria — it is not a general complaint line. The two most common doors in are economic hardship (an IRS action or delay is causing immediate financial harm, like missed rent or utility shutoff) and IRS breakdown (your issue has gone more than 30 days past normal processing, or the IRS blew past a date it promised you). A case that is simply moving slowly, with no hardship and no missed promise, usually gets referred back to normal IRS channels.
Can the Taxpayer Advocate stop an IRS levy?
TAS can push hard for a levy release when the levy causes economic hardship, and in stubborn cases the advocate can issue a Taxpayer Assistance Order directing the IRS to act. What TAS cannot do is override the law: if you genuinely owe the tax, the debt survives even after the levy is released. Pair the release with a resolution — a payment plan, hardship status, or an offer — so the levy does not come back.
Does contacting the Taxpayer Advocate extend my IRS deadlines?
No — TAS involvement never pauses a statutory deadline. The 30-day window to request a Collection Due Process hearing after an LT11 and the 90-day window to petition Tax Court after a Notice of Deficiency both keep running while TAS works your case. File the deadline document first (Form 12153, a Tax Court petition, an appeal), then bring in the advocate.
How long does the Taxpayer Advocate Service take to respond?
It varies with caseload, and TAS does not publish a guaranteed timeline — but hardship cases are triaged first, which is why documenting the hardship on Form 911 matters so much. Once accepted, you get one named case advocate with a direct phone number, which alone beats redialing the general IRS line. Expect the underlying fix to take weeks to months depending on what is broken.
Where do I send Form 911?
Fax or mail Form 911 to the TAS office for your state — not to a general IRS address. Find your office's fax number and mailing address through the office lookup on taxpayeradvocate.irs.gov, or ask for it when you call 1-877-777-4778. Fax is usually the better choice because it creates a dated transmission record you can point to later.
What is the difference between the Taxpayer Advocate Service and a Low Income Taxpayer Clinic?
TAS is a government office that unsticks your case inside the IRS; a Low Income Taxpayer Clinic (LITC) is an independent legal clinic that represents you against the IRS in audits, appeals, and Tax Court, generally free if your income qualifies. They solve different problems: use TAS when the IRS is broken or unresponsive, and an LITC when you are disputing what the IRS says you owe. Many taxpayers use both at once.
Your next 24 hours
- Pull the dates. Find the most recent IRS notice and any letter promising a response — the notice date and the blown promise date are the two facts that anchor your Form 911.
- Gather your proof. Last year's return, every IRS notice, a log of your calls, and hardship documentation (levy paperwork, lease, shutoff notices, bank statements showing the shortfall).
- Get a free case review. Before you file, let an experienced tax professional confirm your case fits TAS criteria and map the resolution to run alongside it — the balance keeps growing with penalties and interest until the underlying debt is handled. Call (888) 825-7779 or use the 2-minute form.
Primary sources: the official Taxpayer Advocate Service website (office lookup and case criteria), the Form 911 PDF on IRS.gov, and IRS.gov/payments if you're able to pay down the balance while your case is worked.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.