
State Back Taxes
Maryland Comptroller Back Taxes: What They Are and How to Resolve Them (2026)
The short answer: Maryland Comptroller back taxes are unpaid state (and county) income, sales, or withholding taxes collected by the Comptroller of Maryland. Resolve them by paying in full, a payment agreement, Maryland's Offer in Compromise, or hardship deferral — acting before your notice's response date prevents wage liens and license renewal holds.
What this guide covers: why the Comptroller of Maryland assessed you, what happens at each stage if you do nothing, every resolution option Maryland offers with its eligibility rules and costs, what a divorce does to a joint bill, and how to respond step by step.
The return address says Comptroller of Maryland, Compliance Division, and the balance inside landed in the middle of a year when you're already rebuilding everything else. Maryland's collection system is smaller than the IRS's. It also moves faster in the ways that hurt. Every one of its enforcement tools has a release path if you act before the response date on your notice.
The image below shows what a Maryland Comptroller collection notice looks like and where to find the notice number, tax year, balance, and response date that control everything that follows.
⏱ Your deadline: the response date printed on your Maryland notice controls your options. There is no grace period after it. Interest and penalties keep accruing monthly, and each enforcement stage that follows (refund intercept, recorded lien, wage lien, license renewal hold) is harder to unwind than the one before it.
Why is the Comptroller of Maryland contacting you?
The Comptroller of Maryland is the state's tax collector. It pursues back taxes for one of four core reasons: a filed return with an unpaid balance, a mismatch between your federal and Maryland returns, an unfiled Maryland return, or unpaid business trust taxes.
You filed but didn't pay in full. This is the most common trigger. You filed your Form 502, the payment didn't cover the balance, and the Comptroller's billing cycle started. Penalties and interest have been stacking on top since the original due date, which is why the number on the notice is bigger than the number on your return.
Your federal and Maryland numbers don't match. Maryland receives federal return data from the IRS. If the IRS adjusted your federal return (a CP2000 underreporter change, an audit, an amended return), the Comptroller typically follows with its own assessment for the Maryland tax on that same income. Many Marylanders resolve the IRS side and are blindsided months later when the state's bill for the identical issue arrives.
You didn't file a Maryland return at all. If W-2s or 1099s show Maryland income and no return was filed, the Comptroller can estimate an assessment for you. Estimated assessments ignore your deductions, exemptions, and correct filing status, so they usually overstate what you'd owe on a real return. Filing the actual return is often the single biggest reduction available.
Your business owes trust taxes. The Comptroller also collects sales and use tax and employer withholding, money collected from customers or employees and held in trust for the state. These debts carry personal exposure for the people responsible, and the state treats them as its most urgent collection priority.
One Maryland quirk: your Maryland bill includes the county (or Baltimore City) local income tax, collected on the same return. That piggyback local tax is why Maryland balances often feel larger, relative to income, than people expect, and why a filing-status change after a divorce can produce a surprisingly big swing.
“An IRS levy permits the legal seizure of your property to satisfy a tax debt. It can garnish wages, take money in your bank or other financial account, seize and sell your vehicle(s), real estate and other personal property.”
— Levy (IRS.gov)
What happens if you ignore Maryland back taxes?
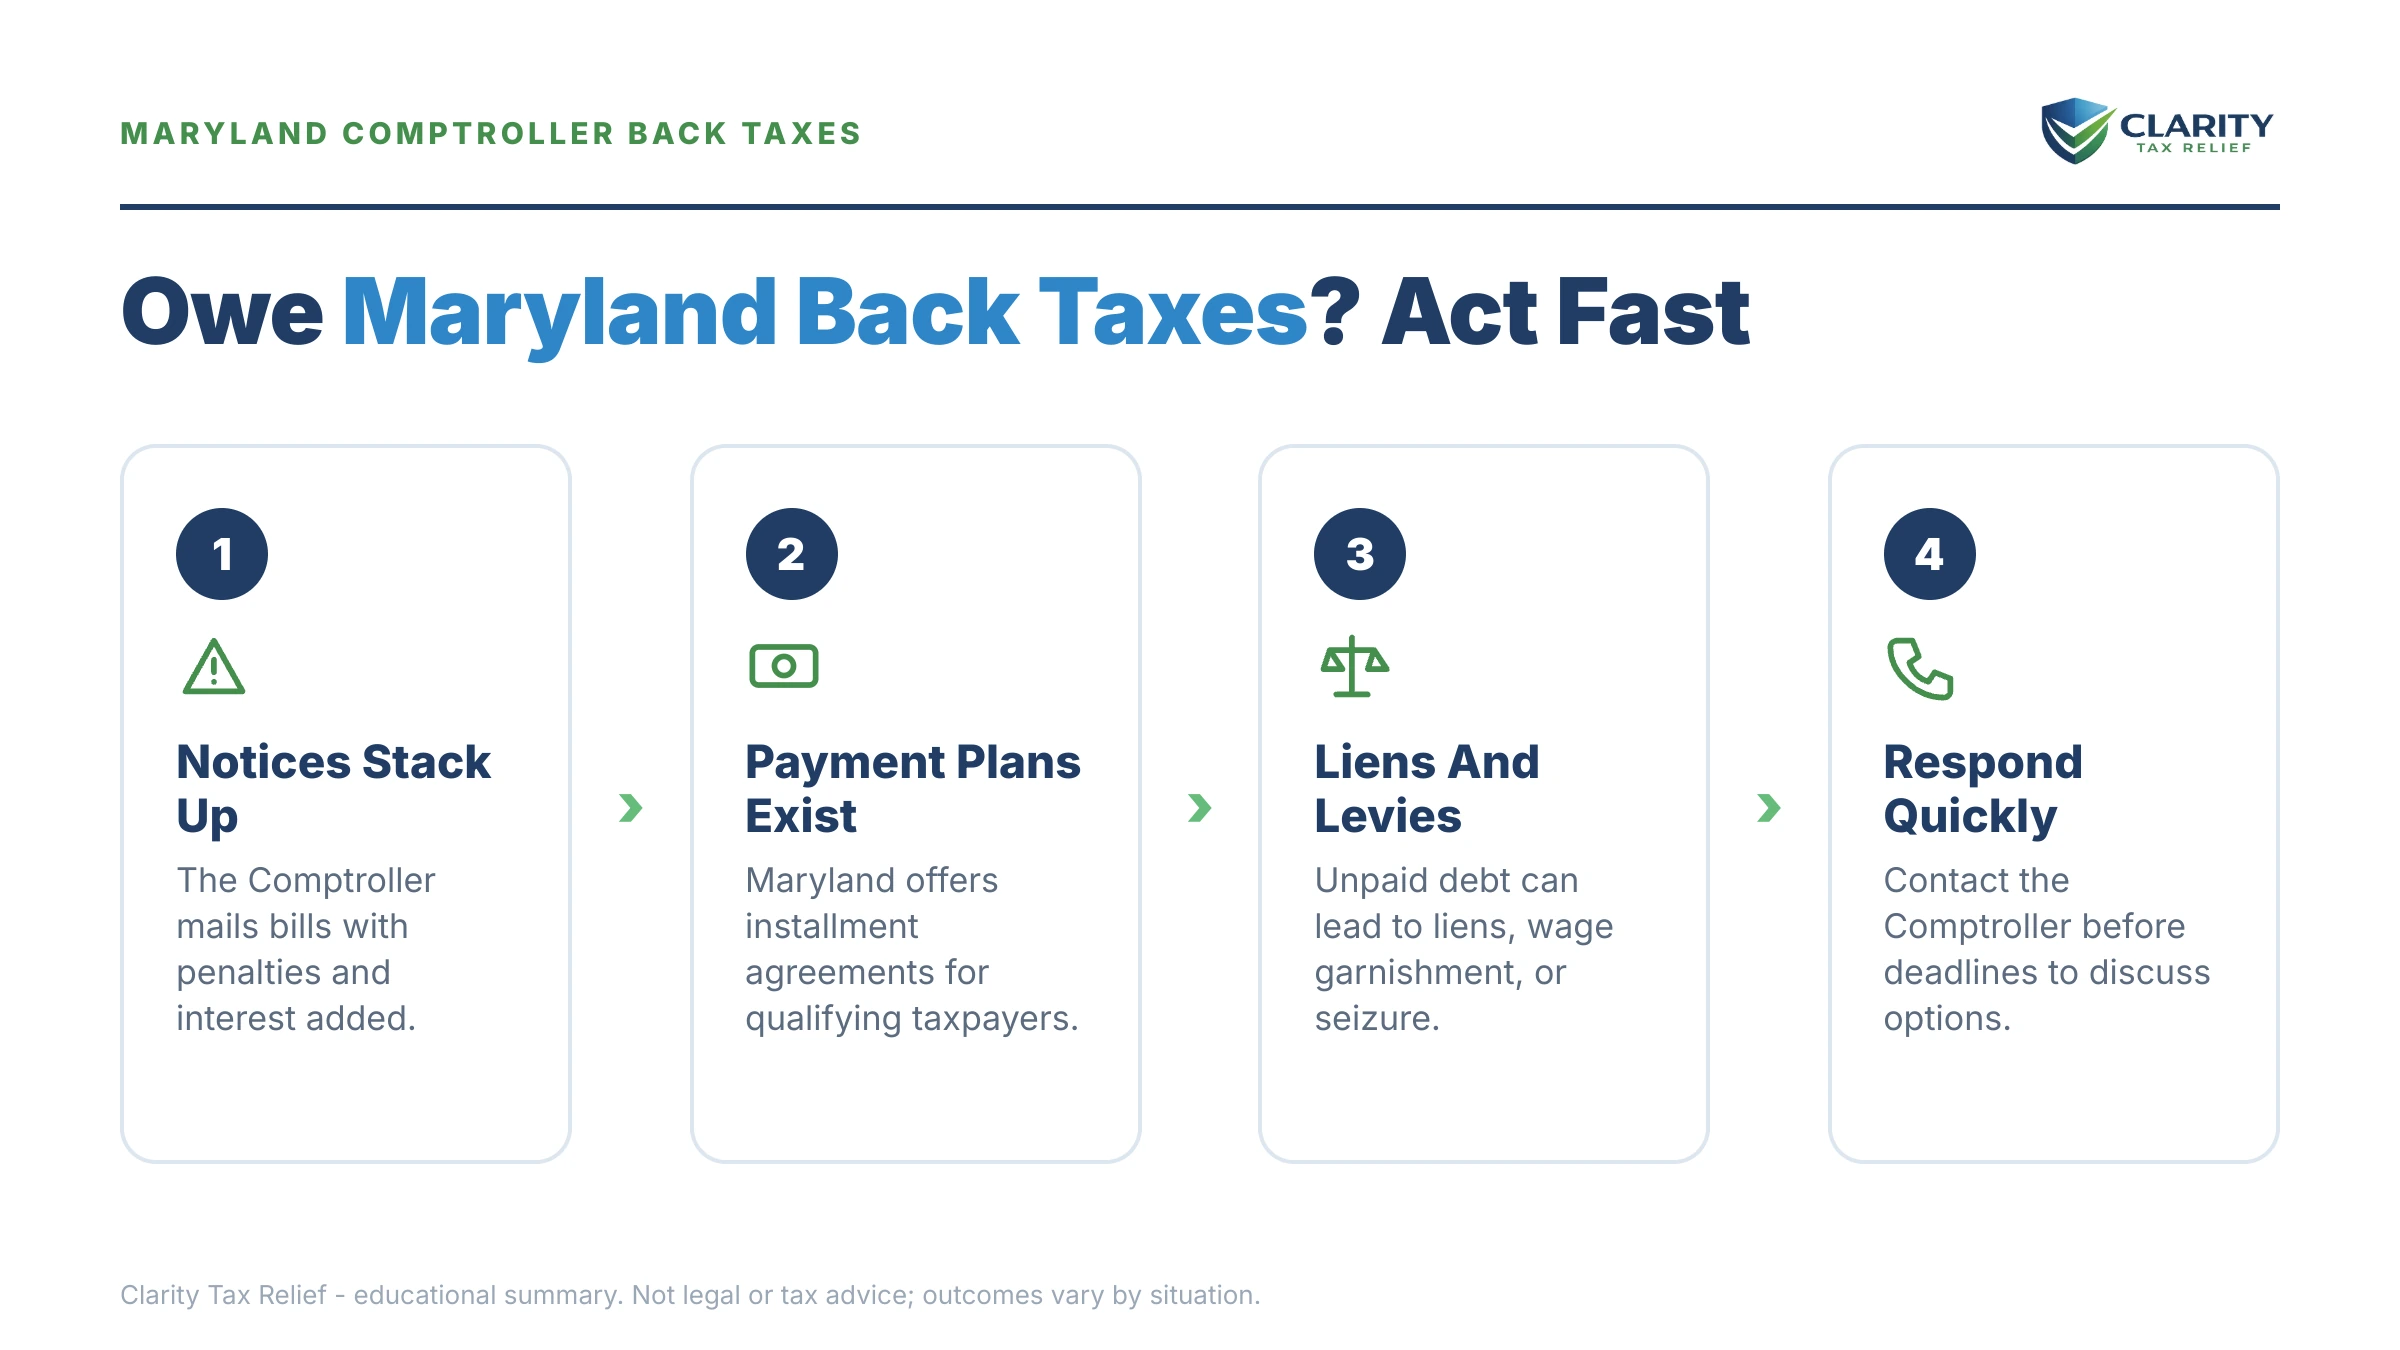
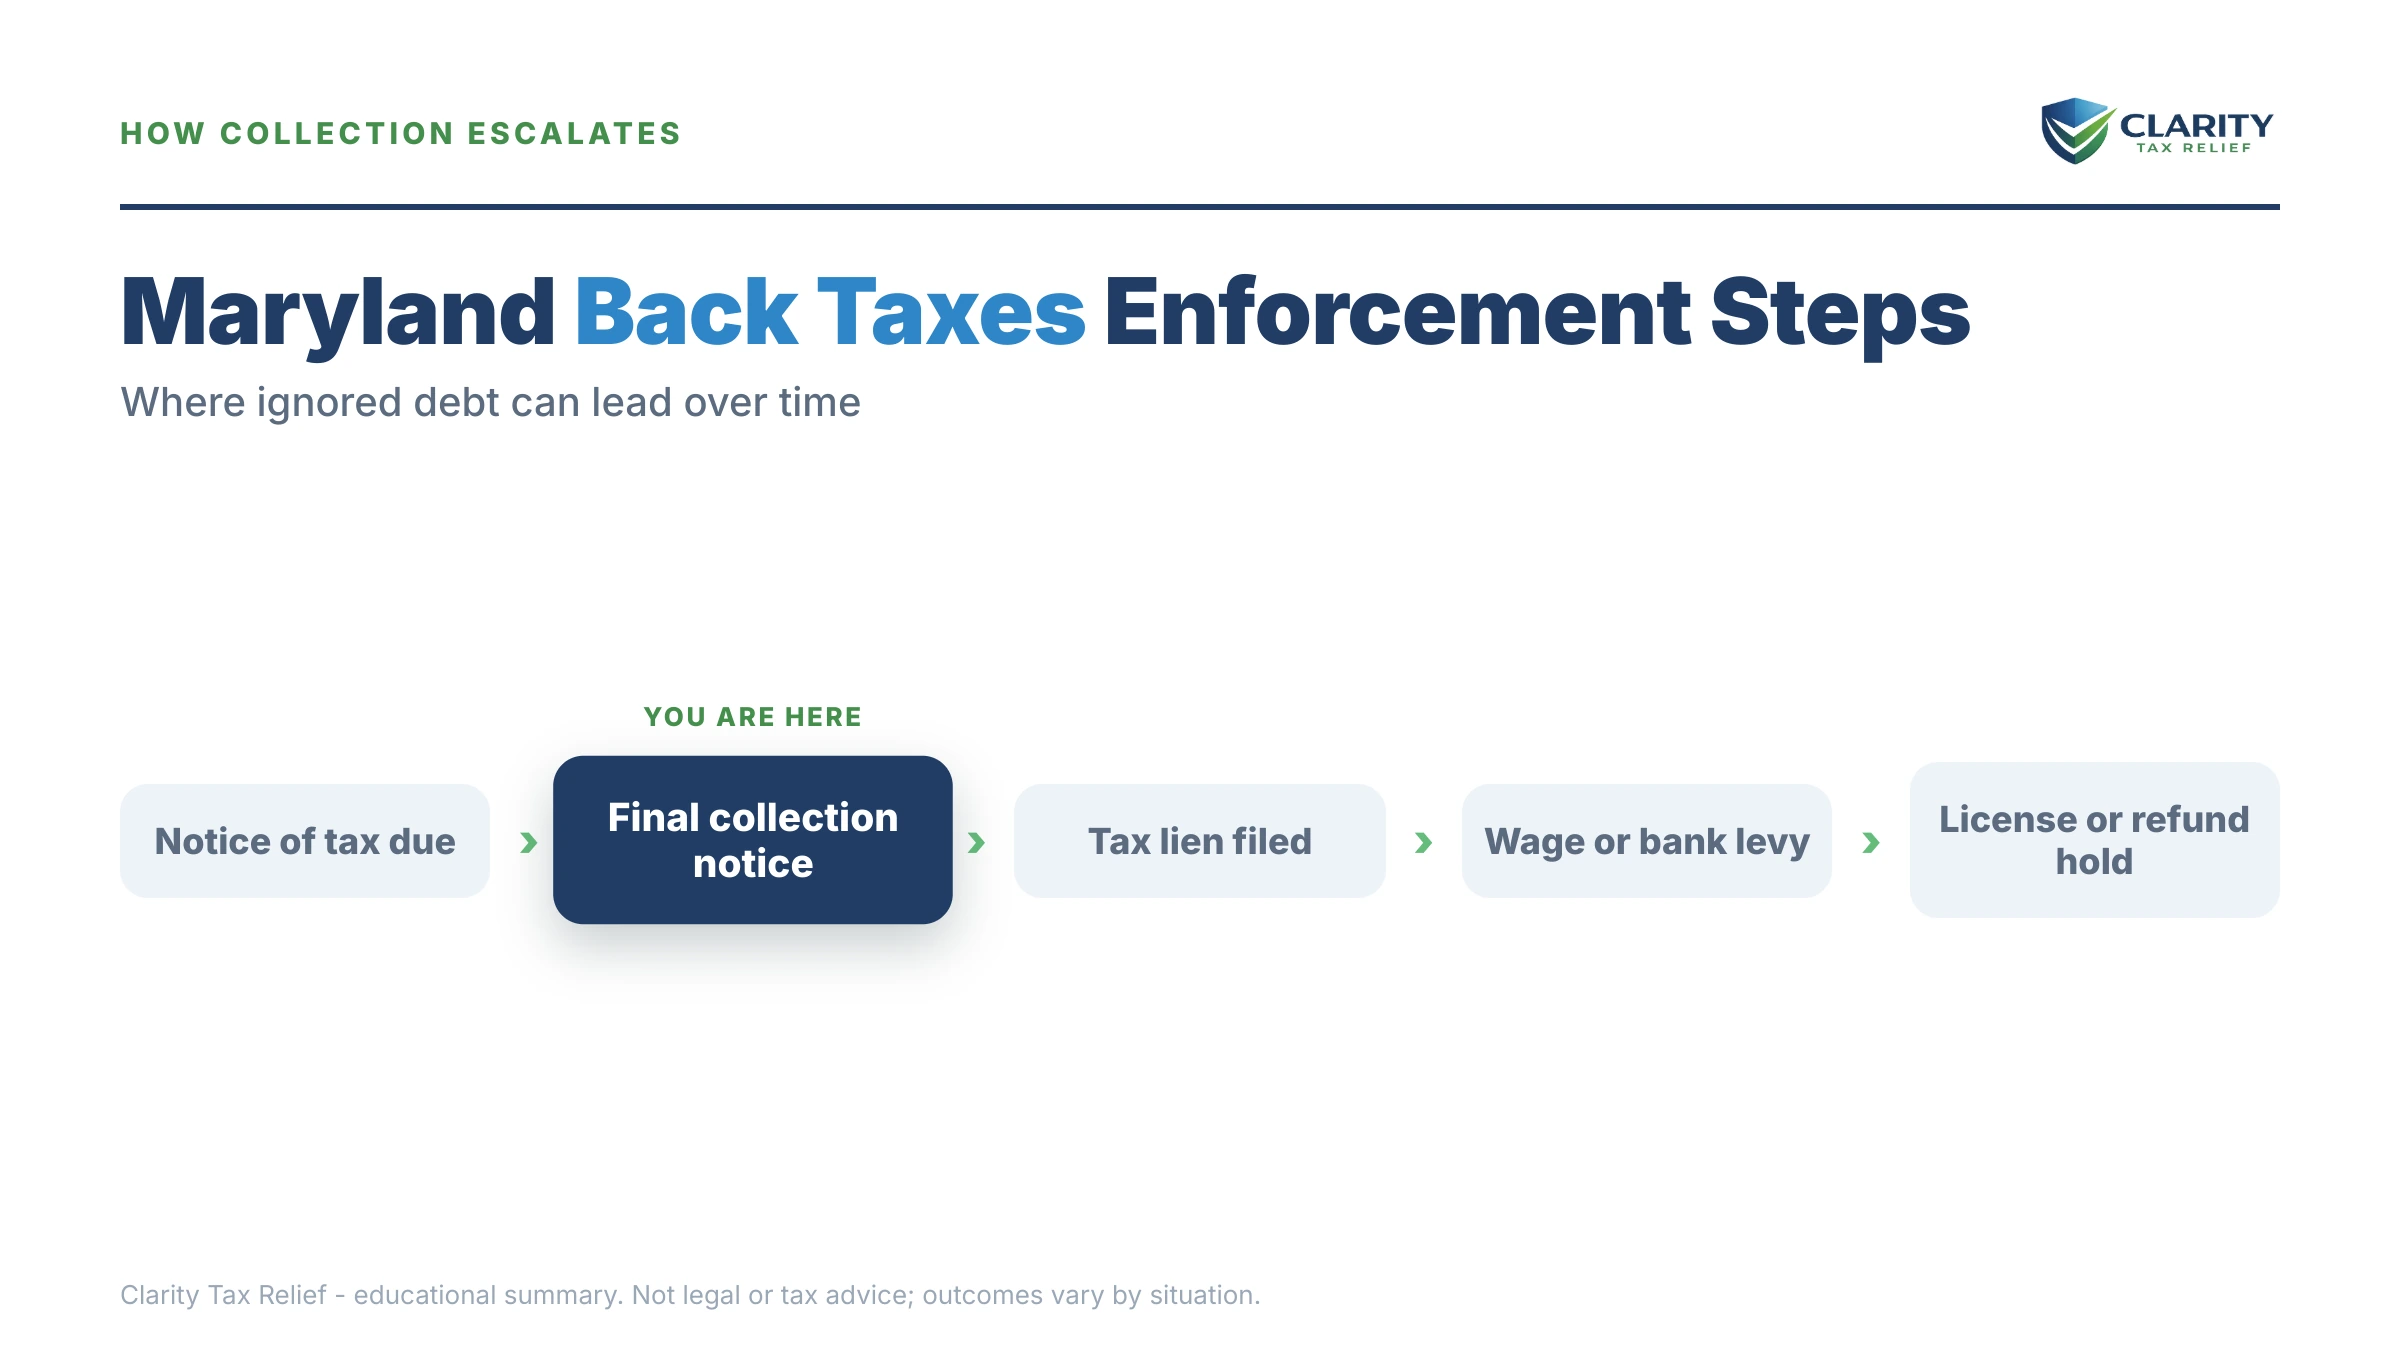
Ignoring Comptroller of Maryland notices leads to refund intercepts, a court-recorded tax lien, wage liens, bank attachments, and renewal holds on your driver's license and vehicle registration, in roughly that order. The sequence is largely automated. Nobody has to decide your file is worth pursuing.
- Assessment and billing. The first notice states the tax year, balance, and response date. Penalties and interest are already accruing.
- Follow-up demands. Continued non-response brings escalating demand notices while the balance grows every month.
- Refund intercepts. Your Maryland refund is applied to the debt automatically. The state can certify the debt to the federal Treasury Offset Program to take your federal refund too.
- Tax lien recorded in circuit court. A Maryland tax lien functions like a court judgment: it's public record, attaches to your property, and complicates selling or financing a home.
- Wage lien or bank attachment. The Comptroller can send a wage lien directly to your employer, no lawsuit required, taking a slice of every paycheck. It can also attach funds in your bank account.
- License and registration holds. The state can flag your account with the Maryland Motor Vehicle Administration, blocking renewal of your driver's license and vehicle registration, and can hold professional license renewals as well.
- Outside collection referral. In some cases the Comptroller refers stale accounts to an outside collection agency, which can add collection costs on top of everything else.
Does Maryland tax debt expire like IRS debt?
Not on the same schedule. The IRS's collection statute generally expires 10 years after assessment. Maryland's collection window runs far longer, and a recorded lien behaves like a judgment. Waiting out the Comptroller is a poor plan for most people. Confirm your account's specific assessment dates with the Comptroller's office or an experienced tax professional before you make any decision based on timing.
| Enforcement tool | What it does | How to stop or release it |
|---|---|---|
| State refund intercept | Your Maryland refund is applied to the debt automatically | Resolve the balance; refunds typically keep offsetting until it's paid |
| Federal refund offset (Treasury Offset Program) | Your federal refund is taken and sent to Maryland | A pre-offset notice comes first; pay, arrange, or file a spousal claim for a non-liable spouse's share |
| Tax lien recorded in circuit court | Public judgment that attaches to property and blocks clean financing | Pay or settle the debt, then confirm the release is recorded |
| Wage (salary) lien | Your employer must send part of each paycheck to the state | A payment agreement or documented hardship is the usual release path |
| Bank account attachment | Funds in the account are frozen and taken | Act before it lands; releases after attachment are difficult |
| License & registration renewal holds | Driver's license, vehicle registration, and professional license renewals blocked | Enter an approved arrangement; the flag lifts once you're compliant |
Holding a Comptroller of Maryland notice right now?
The stage after billing is enforcement — refund intercepts, a recorded lien, a wage lien to your employer. Get your Maryland notice reviewed free before the response date printed on it passes. An experienced tax professional will decode exactly where your account stands and which option fits your finances.
How do you resolve Maryland Comptroller back taxes?
Maryland offers five real resolution paths: full payment, a payment agreement, an Offer in Compromise, hardship deferral, and penalty relief. You also have appeal rights if you dispute the assessment itself. Your finances decide which one fits.
| Option | Best for | Key eligibility / what to know |
|---|---|---|
| Pay in full | You can raise the money without hardship | Fastest, cheapest end to the case; stops all accrual and enforcement |
| Payment agreement | Steady income and a balance you can retire over time | All required returns must be filed; missed payments can void the agreement |
| Offer in Compromise | Income and assets genuinely can't cover the debt | Means-tested; full financial disclosure required; declined if a plan could pay it |
| Hardship deferral | Paying anything would prevent basic living expenses | Temporary; the balance keeps growing and the state revisits your finances |
| Penalty waiver | A cause beyond your control led to the late filing or payment | Removes penalties only, not tax; document the cause in writing |
| Appeal / hearing | You dispute that you owe the assessed amount at all | Strict appeal window that starts on the notice date; check your notice |
Maryland payment agreement
A payment agreement is the workhorse resolution for Maryland individual income tax debt. Smaller balances can often be set up online or by phone with minimal paperwork. Larger balances and business trust taxes usually require talking to the Compliance Division, and the state may ask for financial disclosure before approving terms. Interest continues to accrue during the plan, so a shorter term always costs less in total. Staying current on every future Maryland filing is a condition of keeping the agreement alive.
Maryland Offer in Compromise
Maryland runs its own Offer in Compromise program, separate from the IRS's. It can settle a state tax debt for less than the full balance on two grounds: your documented finances show the state could never collect it in full, or there's real doubt you owe it. Expect full disclosure of income, expenses, and assets. Expect a decline if the numbers show a payment plan could retire the debt. It's a real program and a means-tested one, so nobody gets a discount just by asking.
Hardship deferral
If paying anything would leave you unable to cover rent, food, or medical care, the Comptroller can temporarily suspend active collection while your situation improves. Two honest caveats. The debt remains and keeps growing with interest, and refund intercepts typically continue even while collection activity is paused. Hardship status buys breathing room and resolves nothing by itself.
Penalty waiver
Maryland can waive penalties when a circumstance beyond your control caused the late filing or payment: serious illness, a disaster, records tied up in litigation, or a life event like a divorce that disrupted your finances. Put the request in writing, attach documentation, and be specific about dates. Interest is rarely waived, so treat penalty relief as a meaningful reduction and nothing more. (Maryland's rules are its own. Federal programs like first-time abatement don't apply to a state balance.)
Disputing the assessment
Maybe the assessment itself is wrong. The income isn't yours, the estimated assessment ignores your real return, or the federal adjustment it's based on was reversed. You can request an informal hearing with the Comptroller's hearings and appeals staff, and appeal further to the Maryland Tax Court if needed. The appeal window is short and starts on the notice date, so check your specific notice and don't let the deadline pass while you gather documents.
| Option | What it costs you | Typical timeline |
|---|---|---|
| Pay in full | The balance shown plus interest accrued through payoff | Immediate; ends penalties, interest, and enforcement |
| Payment agreement | Full balance over time; interest keeps accruing during the plan | Setup often within days; payoff runs the length of the plan |
| Offer in Compromise | The offered amount if accepted, plus time and documentation to prepare | Months for review; interest accrues while it's pending |
| Hardship deferral | Nothing now, but the balance keeps growing and refunds are still intercepted | Relief while approved; the state periodically re-reviews your finances |
| Penalty waiver | Free to request; removes penalties, not tax or (usually) interest | Weeks to months for a written decision |
| Appeal / hearing | Free to request; professional representation optional | Short window from the notice date; hearing first, Maryland Tax Court after |
A worked example: say you owe Maryland $19,700 after a divorce
Say your divorce was final in March and your withholding was still set for married-filing-jointly all year. Your first single-filed Maryland return, state plus county local tax, lands with a $19,700 balance you don't have. This is hypothetical. The math is real:
- Do nothing: penalties and interest compound monthly, and this year's state and federal refunds get intercepted. The eventual wage lien takes the decision out of your hands at a percentage you don't choose.
- 24-month payment agreement: $19,700 ÷ 24 ≈ $821/month before interest. That's heavy on one income, but it ends the case in two years with the least total interest.
- 48-month payment agreement: $19,700 ÷ 48 ≈ $410/month before interest. Livable on a post-divorce budget, at the cost of more total interest over the longer term.
- Offer in Compromise: only if the disclosure math supports it. If your take-home is $4,000/month and allowable expenses leave roughly $600/month free, the state sees a taxpayer who can pay through a plan, and will say so. An offer fits when income and assets can't reach $19,700. A plan that merely feels painful doesn't qualify.
Then fix the leak: update your Maryland withholding for single status so next April doesn't create a second balance behind this one.
Divorced and holding a joint Maryland tax bill?
On a joint Maryland return, both spouses are liable for the entire balance, and your divorce decree does not change that. A decree assigning the tax debt to your ex is enforceable between the two of you in family court. The Comptroller isn't a party to it and can collect 100% from whichever spouse is easier to reach. The same principle applies federally; see why a divorce decree doesn't bind tax collectors and divorce and IRS debt: who pays.
What you can do on the Maryland side:
- Protect your own refunds. If you've remarried, a claim for the non-liable spouse's share (an injured-spouse-type claim) can protect part of a joint refund from being swallowed by your old debt. It must be filed. Nothing happens automatically.
- Raise the underreporting issue. If your ex hid income or overstated deductions without your knowledge on a joint return, relief from the resulting liability may be available. Document what you knew and when.
- Get your own agreement. If your ex won't cooperate, don't wait. The state won't split enforcement fairly between you. An agreement in your name protects your paycheck and your license renewal regardless of what your ex does.
What if you owe Maryland and the IRS both?
Owing both agencies is common, since the same underreported income or unpaid balance usually creates two bills. The general framework for sequencing them lives in our guide to state tax debt vs. IRS: which to resolve first. In Maryland, the Comptroller often reaches enforcement faster than the IRS's long notice sequence, because it can intercept refunds, issue wage liens, and hold license renewals with less lead time. The two agencies also raid each other's refunds. Maryland certifies debts to take your federal refund, and the IRS can grab your state refund through its own levy program. If a refund already vanished and you're not sure who took it, start with state refund taken for tax debt. Both balances accrue interest, so the workable answer is almost always two affordable arrangements, prioritizing whichever agency has already threatened or begun enforcement.
How to respond to a Maryland Comptroller collection notice, step by step
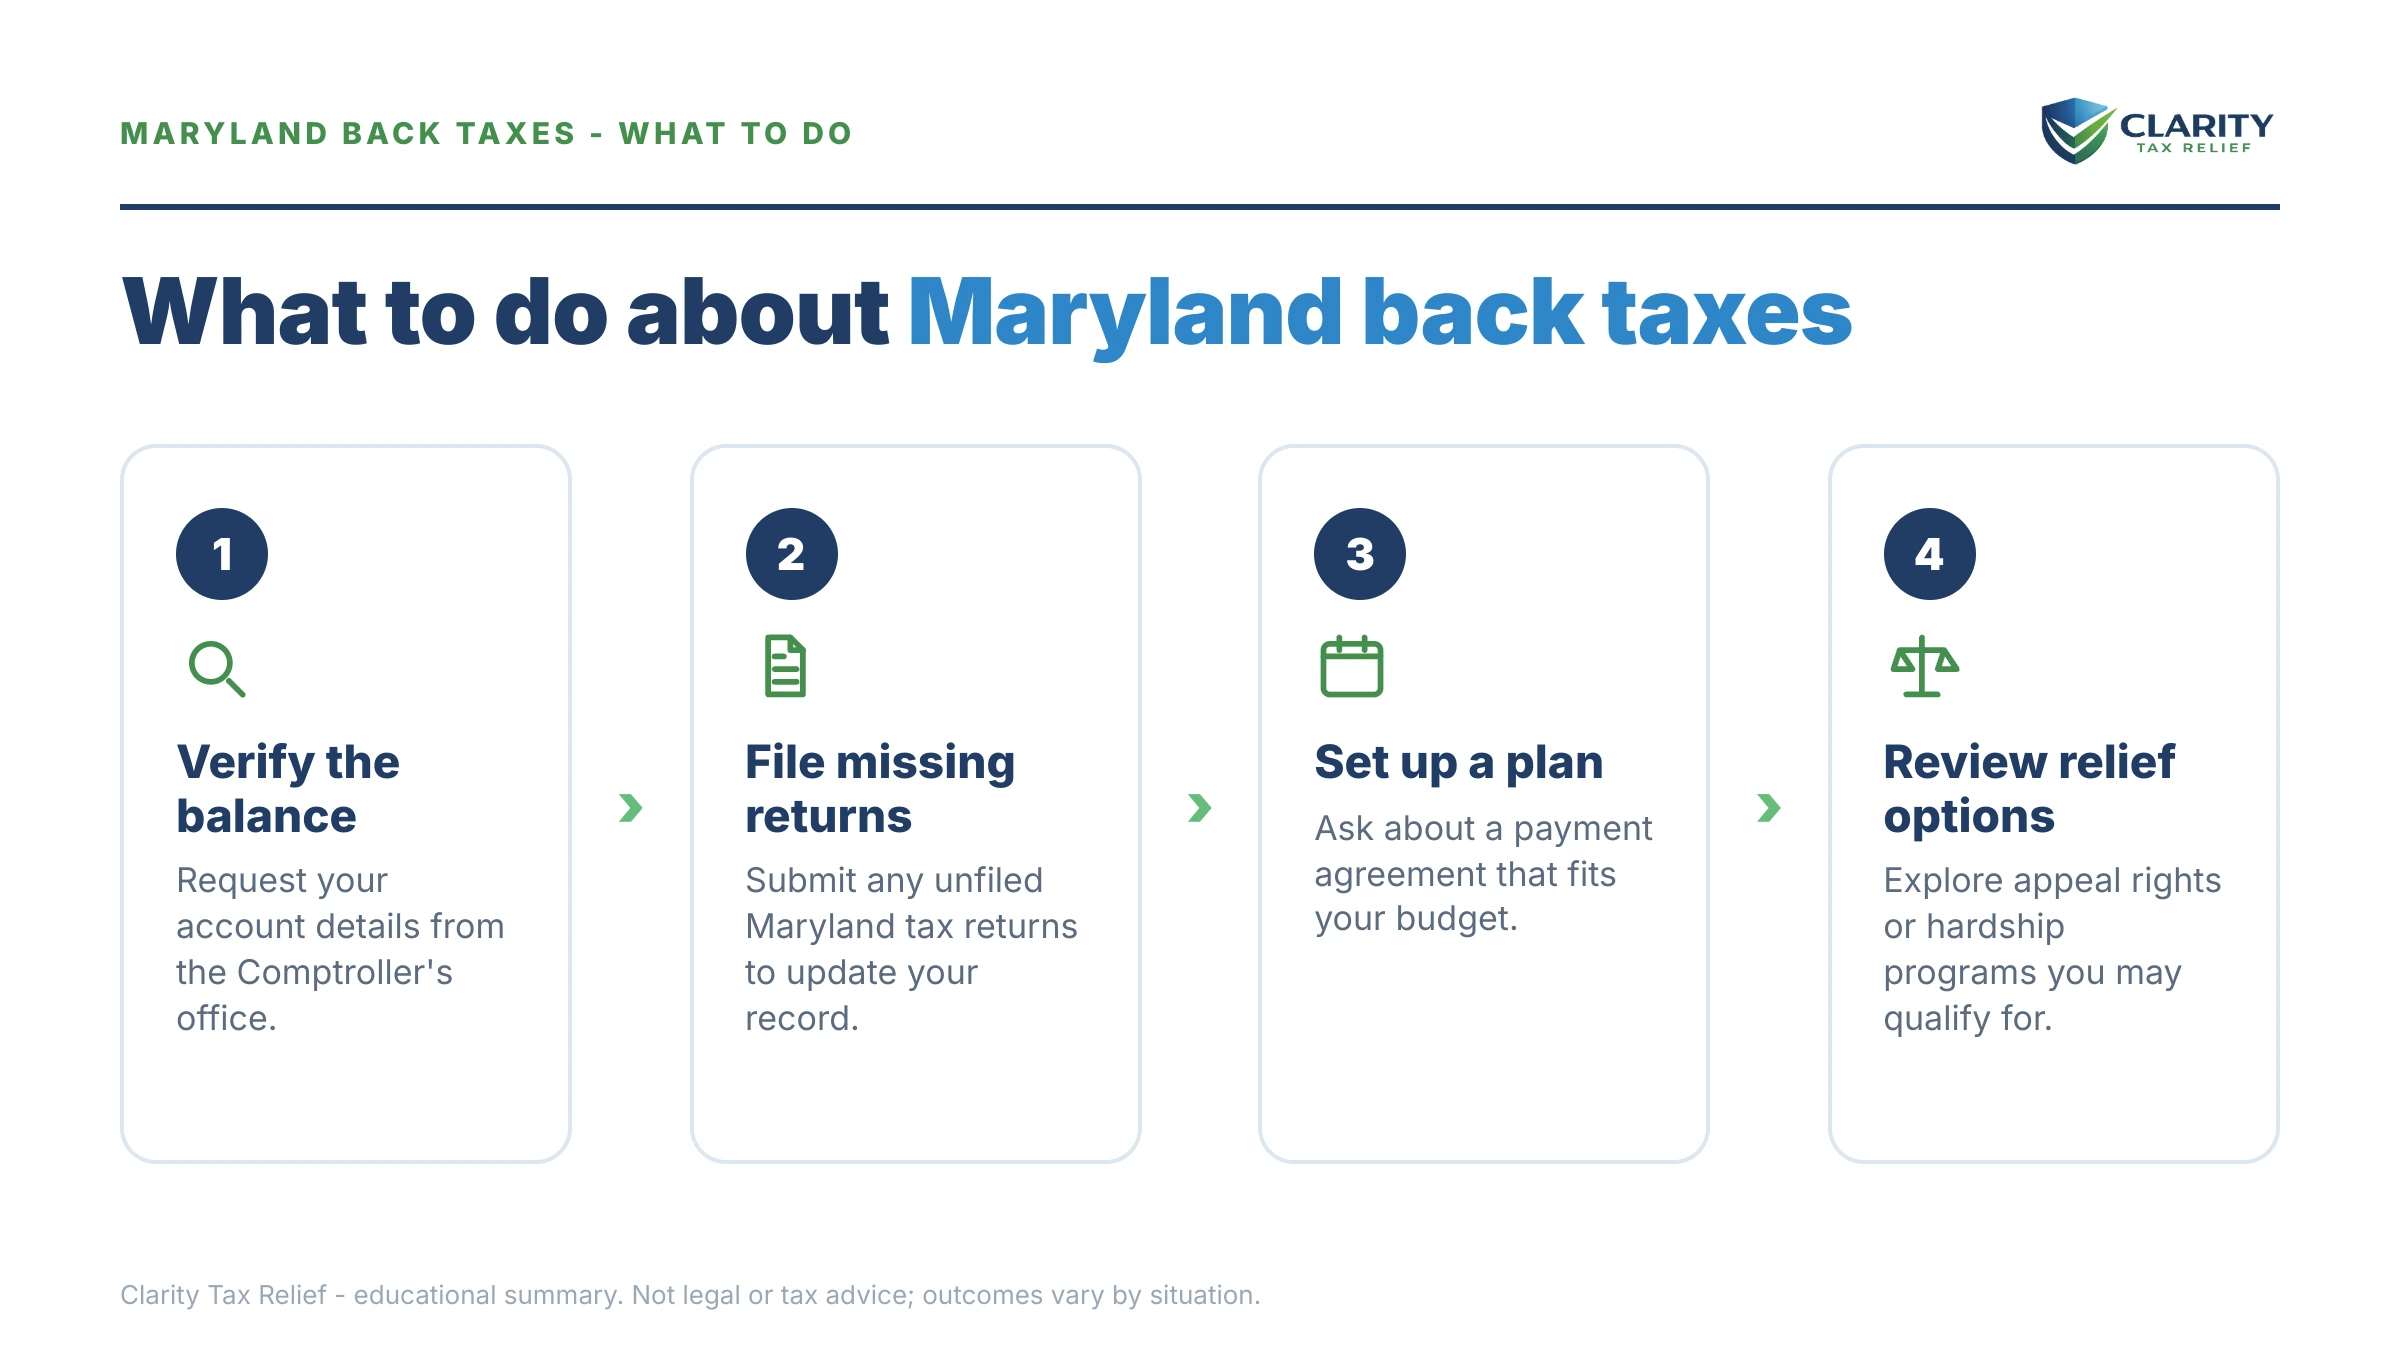
- Verify the balance. Contact the Comptroller's Compliance Division or check your account through the state's online services to confirm the tax years, the amounts, and how much of the balance is penalty and interest versus tax.
- File any missing Maryland returns. The Comptroller generally won't approve a payment agreement or an offer while required returns are unfiled, and filing can replace an estimated assessment with your real, often lower, number.
- Choose your resolution path. Pay in full if you can, request a payment agreement if you need time, or pursue an Offer in Compromise or hardship deferral if your documented finances support it.
- Set it up before your response date. An approved arrangement stops the escalation to liens, wage liens, and license holds; a missed deadline restarts it.
- Request penalty relief in writing. If illness, the divorce itself, or another circumstance beyond your control caused the late filing or payment, ask for a penalty waiver and attach documentation.
- Get a professional review if enforcement has started. Once a lien is recorded or a wage lien is issued, the order you fix things in (returns, penalties, then the balance) changes what you end up paying.
Red flags on a Maryland account
- A response date that has already passed or is days away.
- A federal or state refund that never arrived.
- A pay stub showing a wage lien deduction.
- A renewal notice from the MVA you can't complete.
- An estimated assessment for a year you never filed.
When can you handle Maryland back taxes yourself?
You likely don't need professional help if the balance is one you can pay within a few months, it covers a single tax year, you agree with the number, and no enforcement has started. Verify the balance, set up the payment agreement, keep every confirmation, and stay current going forward. That's the whole job, and paying someone to do it adds cost without changing the outcome.
Experienced help changes outcomes in specific situations. A wage lien is already at your employer, or a lien is already recorded in circuit court. Multiple unfiled Maryland years sit under estimated assessments. Business trust-tax exposure like sales tax debt or withholding puts personal liability on the table. There's a joint-liability fight after divorce. Or you're preparing an Offer in Compromise, where the disclosure package is won or lost on how the financial math is presented. In those cases the sequencing (which returns to file first, which relief to request before which agreement) routinely changes the final number.
If your Maryland case involves a recorded lien, a wage lien, or years of unfiled returns, get a free case review before the next notice lands, or call (888) 825-7779.
Terms on your Maryland notice, decoded
- Assessment: the formal act of putting a tax debt on the books; the notice date and assessed amount flow from it.
- Salary (wage) lien: Maryland's administrative wage garnishment, an order sent straight to your employer, no lawsuit required.
- Judgment lien: a Maryland tax lien recorded in circuit court, giving the state the powers of a judgment creditor against your property.
- Refund intercept / offset: your state or federal refund applied to the debt before you ever see it.
- License hold: a flag with the MVA or a licensing board that blocks renewal of your driver's license, registration, or professional license until you're compliant.
- Maryland Tax Court: the independent body that hears appeals when you and the Comptroller disagree after an informal hearing.
Common questions
Can the Comptroller of Maryland stop me from renewing my driver's license?
Yes. The Comptroller can flag unpaid tax accounts with the Maryland Motor Vehicle Administration, which blocks renewal of your driver's license and vehicle registration until the debt is resolved or you enter an approved payment arrangement. It's a renewal hold rather than an immediate suspension. It surfaces at the worst moment, when your renewal is due. Entering a payment agreement is usually the fastest way to get the flag lifted.
Can Maryland garnish my wages without taking me to court?
Yes. The Comptroller can issue a wage lien directly to your employer through an administrative process. It does not need to sue you and win a judgment first, the way most private creditors do. Once your employer receives the lien, a portion of every paycheck goes to the state until the balance is paid or you negotiate a release, usually by entering a payment agreement.
Can I set up a Maryland tax payment plan online?
In many cases, yes. The Comptroller offers online payment-agreement setup for individual income tax balances, and phone setup is available if your situation doesn't fit the online tool. Larger balances or business trust taxes like sales and withholding tax typically require speaking with the Compliance Division and may require financial disclosure before terms are approved. Missing a payment can void the agreement, so pick a number you can sustain.
Bottom line
The Comptroller moves from bill to refund intercept to lien to wage lien and license hold, and Maryland's collection window runs far longer than the IRS's ten years. File anything missing, pick the option your finances support, and get it in place before the response date on your notice. If enforcement has already started, the order you fix things in matters.
Your next 24 hours
- Find the controls on your notice: the notice number, tax year(s), total balance, and the response date. Those four items determine which options are still open.
- Gather your paperwork: the notice itself, your last two Maryland returns (the joint years and your first single-filed year), and your current income information, such as pay stubs or 1099s.
- Get a free case review before the response date on your notice passes: the 2-minute form or (888) 825-7779. An experienced tax professional will confirm what Maryland's records show and match your finances to the right resolution, whether that's a payment agreement, offer, hardship, or appeal.
Primary sources: the Comptroller's official site at the Comptroller of Maryland handles payments, agreements, and account questions for state tax debt. If you also owe federally, the IRS's own options live at IRS.gov/payments.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.