
IRS Transcript Codes
Code 810 Refund Freeze: What It Means, Why It Shows $0.00, and How It Gets Released
The short answer: code 810 on an IRS transcript is a refund freeze: a compliance unit flagged the return for identity verification, a questionable refundable credit, a frivolous-return screen, or an exam. It shows $0.00 because it is a flag, not a dollar entry. Only code 811 releases it. Clarity Tax Relief finds the unit that set the freeze before doing anything else.
This guide covers what code 810 means on an IRS transcript, the responsibility codes behind it, why it shows $0.00, why the letter lags the code, how long each path takes according to the IRS's own pages, and how to get the freeze released.
You checked your transcript expecting an 846 with a deposit date and found "810 Refund Freeze" instead, with $0.00 beside it and nothing in the mail explaining it. That line is not a bill and it is not a decision. It is a hold placed by a specific IRS unit, and the whole game is finding out which unit and what it wants. If the transcript layout itself is unfamiliar, start with how to read an IRS account transcript, then come back here.
⏱ Your real clock: code 810 has no printed deadline. The freeze holds your refund until it is released with code 811. But if the IRS mailed you a verification or document-request letter, the response date printed on that letter controls. Miss it, and the IRS can disallow the refund instead of releasing it.
What does code 810 mean on an IRS transcript?
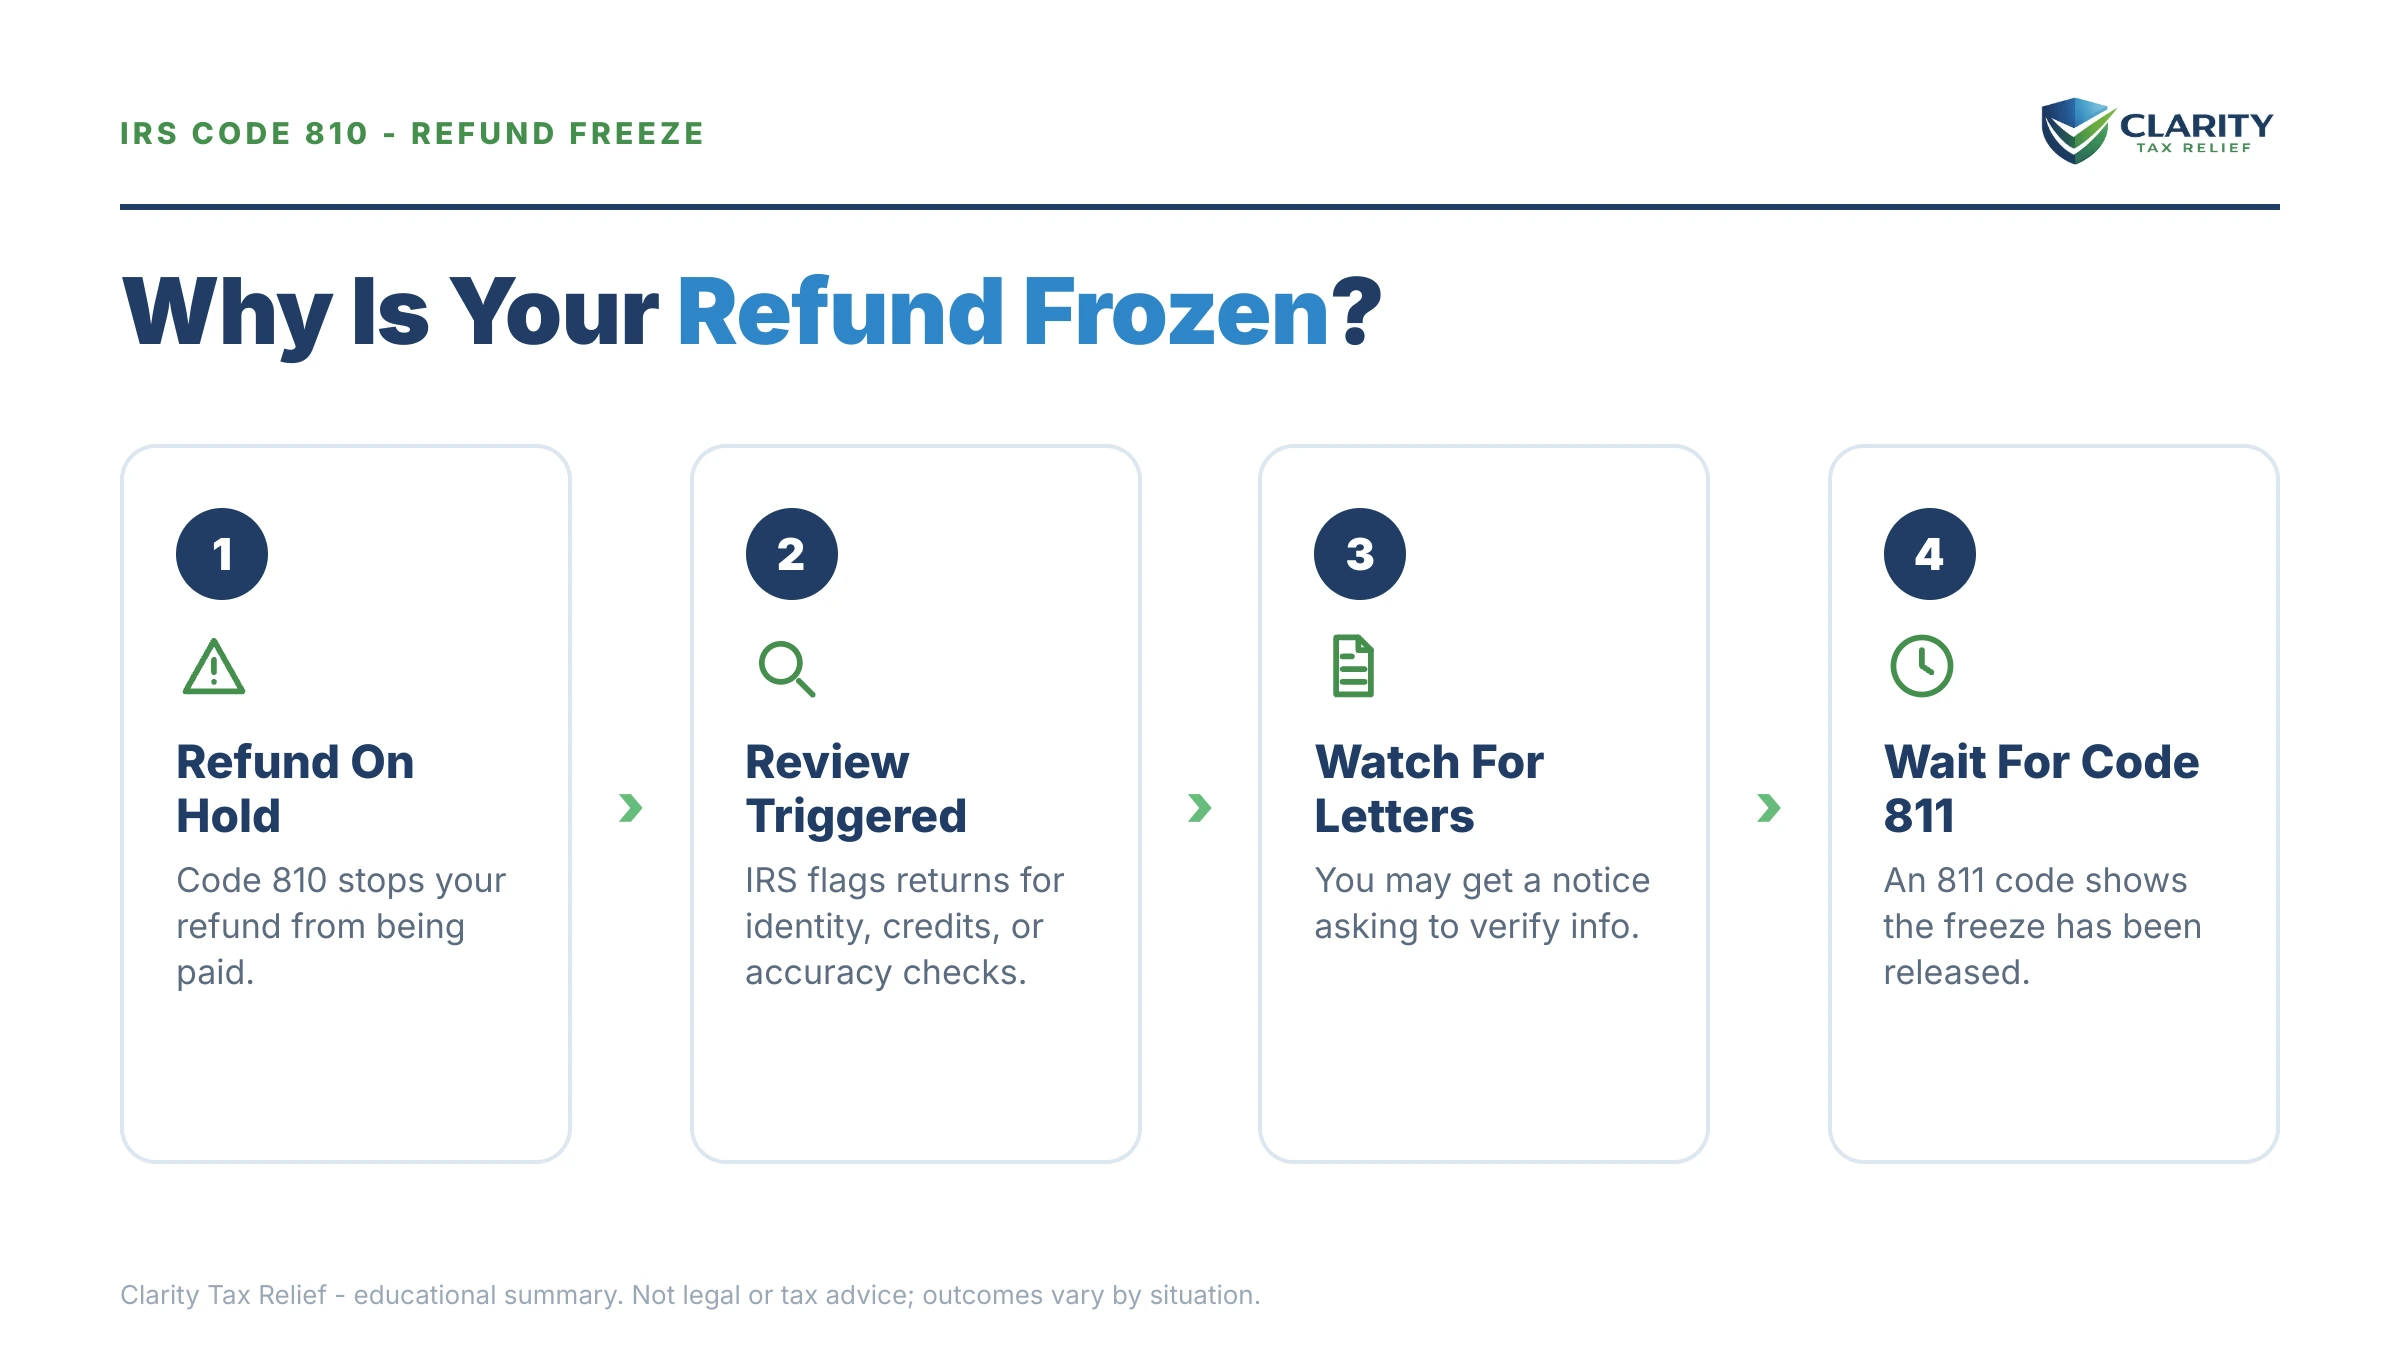
IRS transaction code 810 is a refund freeze. The IRS code book, Document 6209, defines TC 810 as a transaction input "to freeze the module from refunds, offsets and credit elect." In practice, a compliance unit flagged your return before paying the refund, and only that same unit can lift the flag. Unlike the softer code 570 account hold, which often resolves on its own during routine processing, an 810 is a hard freeze that requires a person in that unit to release it. The IRS manual (IRM 21.5.6) says the 810 is placed "by Compliance or Return Integrity and Compliance Services (RICS)." If you want the wider map of codes, our IRS transcript code guide covers every line; this page stays on 810.
Four triggers account for nearly all 810 freezes:
- Identity verification. The IRS's return-integrity filters flagged the return as possibly not yours. A CP5071 series notice (the IRS now groups the 5071C under that name), a 4883C, or a 5747C usually follows, asking you to prove you filed it.
- Questionable refundable credits. The return claims credits the IRS sees heavily abused: the fuel tax credit, sick-and-family-leave credits, or Earned Income Credit and Child Tax Credit claims that do not match its records. The IRS manual lists responsibility code 3 as the credit freeze, naming EITC, the Additional Child Tax Credit, the Premium Tax Credit and the American Opportunity Tax Credit.
- Frivolous return screening. Returns that resemble known refund schemes get a preventive freeze in RIVO under responsibility code 4. The IRS can add a $5,000 penalty per return ($10,000 on a joint return) under IRC §6702 if the position is not corrected, and its Letter 3176C gives 30 days to withdraw the position or file a corrected return before the penalty is assessed.
- Pre-refund examination. The IRS wants to audit the return before paying. The manual says a code 420 or 424 posting after the 810 identifies Examination involvement.
Which trigger applies decides everything about the fix, which is why identifying it is step one rather than calling and demanding the refund.
What the responsibility code on an 810 tells you
Every 810 carries a one-digit responsibility code (RC) that names the reason. You cannot see it on a transcript, but a phone representative can, and asking for it is the fastest way to learn which unit has your return. This table is drawn from Document 6209 and IRM 21.5.6:
| RC | Meaning | Letter that usually follows |
|---|---|---|
| 1 | Pre-filing notification: a compliance refund-hold project | Varies by project; a letter or document request from the unit that set the hold |
| 2 | Abusive Tax Shelter Detection (ATSDT) freeze | A letter or document request from the unit that set the hold |
| 3 | Refundable-credit freeze: EITC, ACTC, Premium Tax Credit, AOTC | CP75, Letter 566, or a 4800C from the Automated Questionable Credit unit |
| 4 | Preventive RIVO freeze to screen for frivolous-return criteria | Letter 3176C, or nothing for up to 180 days |
| 6 | Preventive freeze for an identity or income-document (IRP) review | Possibly a notice asking you to support income or withholding; phone staff are told to allow 180 days |
| 7 | Preventive refund freeze set by Return Integrity and Compliance Services | Possibly a notice asking you to support income or withholding; phone staff are told to allow 180 days |
Why does the 810 refund freeze show $0.00?
Clarity Tax Relief tells clients to set the amount on an 810 aside. The $0.00 beside code 810 confuses more people than the code itself. It is normal. An 810 is an indicator, not a movement of money, so the transcript prints it with no amount. The tax you owe is on code 150, your withholding is on 806, your refundable credits are on 766 and 768, and the refund that pays is on 846. The 810 sits between those lines and blocks the 846 from posting. A zero on the 810 line does not mean your refund was reduced to zero, and it does not mean the IRS decided anything yet.
The same is true of code 811 when it arrives. Document 6209 says an 811 with a zero amount "will reverse the TC 810 and allow release of all credit," provided no other freeze is on the account. So an 811 for $0.00 is the good version. It is the full release.
“It may take up to 9 weeks to process your return after you verify it.”
— Verify your return (IRS.gov)
What does your transcript show around an 810, and what does each code mean?
The codes surrounding an 810 tell you who froze the refund and how far the case has moved. The three that matter most after an 810 are 971 (a notice went out), 420 or 424 (Examination has the return), and 811 (the freeze was released). Read the dates and dollar amounts on each line, then match them to this table. Every meaning below is taken from Document 6209, Section 8A:
| Code | What it means | What to do |
|---|---|---|
| 150 | Your return posted; this is the tax it computed | Confirm the year and amounts match what you filed |
| 806 | Withholding credited from your W-2s and 1099s | Check it against your actual forms |
| 766 / 768 | Refundable credits posted (CTC, EITC, others) | These are often what the freeze is examining |
| 810 | Refund freeze; no refund pays until released. Shows $0.00 | Identify the trigger; follow the steps on this page |
| 971 | A notice or letter was issued | Watch your mail; the letter names the fix. A 971 with action code 128 means the AQC unit has it |
| 420 / 424 | Examination opened or requested | Audit path. Respond to Letter 566 or CP75 fully |
| 811 | Freeze released by the unit that set it | Good news. Watch for 846 next |
| 846 | Refund issued, with the payment date | Nothing. The money is on its way |
A worked example: the $13,600 joint refund
Say you and your spouse filed jointly and the transcript reads: code 150 (tax) $4,400, code 806 (withholding) $11,100, and codes 766/768 (refundable credits) $6,900. Your refund is $11,100 plus $6,900 minus $4,400, or $13,600, all of it frozen by the single $0.00 810 line, the credits included.
Now the trigger decides the outcome. If it is identity, one successful verification releases the entire $13,600. If it is the credits and an exam disallows them, the refund shrinks to $11,100 minus $4,400, or $6,700, a $6,900 swing that turns entirely on whether you can document eligibility. Same code, very different endings.
One small consolation: if the refund is paid after a long hold, the IRS generally adds interest for the time it kept your money.
What happens if you ignore an 810 refund freeze?
An 810 freeze never times out in your favor. Left alone, it moves toward disallowance rather than release. The sequence runs in stages:
- The freeze posts. Where's My Refund stalls, sometimes showing Tax Topic 151. No letter yet; the transcript knows before the mail does.
- A letter follows. Identity (CP5071 series, 4883C, or 5747C), a review notice (CP05 or CP05A asking for documents), or an exam opener (Letter 566 or CP75). Each carries a printed response date.
- You don't respond. On the identity path, the return is treated as unverified and the refund is never processed. On the credit path, the exam disallows the credits and a code 290 adjustment rewrites your account without them.
- Formal disallowance. The refund is denied. If the return claimed fabricated credits, the $5,000 frivolous-return penalty can be added, turning a frozen refund into a balance you owe, which then enters IRS collections.
The letters can lag the code by months. The automated freeze itself posts instantly and never forgets. Silence from the IRS is not the same as the case resolving.
Is a code 810 freeze sitting on your refund right now?
Send us your transcript and any IRS letters. An experienced tax professional will identify which unit set the freeze, what it is examining, and the response that unit needs. The review is free, confidential and no pressure. If the freeze has turned into an exam of your credits, our IRS audit representation team can answer the examiner for you. Letter response windows are short once the mail arrives, so don't wait for the next notice.
Which credits draw this freeze most often?
An 810 is a hold, not a finding, and it lands disproportionately on returns claiming refundable credits. The Earned Income Tax Credit is the one that shows up most in these transcripts, because it is refundable and it turns on household facts the IRS cannot see from a W-2. By law, refunds on returns claiming EITC are also held until mid-February every year, so an early-season wait is not by itself a freeze. Our PATH Act refund hold data shows how that annual hold plays out.
That is useful to know for one practical reason: if your return claims a refundable credit, the fastest thing you can do while the freeze sits there is assemble the proof for it. Not send it, yet. Have it ready, because the letter that eventually arrives will ask for exactly that and the clock starts when it does. For a qualifying child, that means school, medical or lease records showing where the child lived; our guide to proving residency for the EIC lists what the IRS accepts.
How do you get an 810 refund freeze released?
Every 810 release runs through the unit that set the freeze, and each trigger has its own fix:
“Every 810 release runs through the unit that set the freeze. Only that unit's code 811 lifts it,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
- Identity trigger: complete verification through your letter's instructions: online at the IRS's verification service for a CP5071 series notice, by phone for a 4883C, or in person for a 5747C. The IRS says it may take up to 9 weeks to process the return after you verify. Our guide to the 810 freeze identity verification path walks through it screen by screen.
- Document review (CP05A): send the requested proof by the date on the notice. The IRS asks for at least three pay statements including the year-end stub, or a letter on employer letterhead, or a retirement benefits statement, and it says not to send a W-2. Use the Document Upload Tool on the notice for the fastest handling, and allow 60 days after you send it.
- Credit exam (CP75 or Letter 566): document eligibility for each credit: school and medical records for a child's residency, birth certificates for relationship, income records. With no response, the IRS disallows the audited items and sends an examination report.
- A return that is wrong: if a preparer claimed credits you never qualified for, amend with Form 1040-X. Correcting it voluntarily is the cleanest way to avoid the frivolous-return penalty.
- Hardship or a stalled case: the Taxpayer Advocate Service can intervene when the delay causes economic harm or the IRS misses its own timelines. Our Form 911 walkthrough shows how to request help.
- Disallowed anyway? You have appeal rights, and a formal claim-disallowance letter starts a two-year window to challenge the denial in court. Do not let a wrong disallowance stand.
Here is how the paper stages line up against your rights:
| What arrives | Your window | What you risk if you miss it |
|---|---|---|
| CP5071 series notice or 4883C (identity) | The date printed on the letter | Return treated as unverified; refund never processed |
| Letter 5747C (in-person verification) | The appointment window in the letter | Same; the return stays in limbo |
| CP05A (send documents) | The date printed on the notice | Withholding or credits removed from the refund |
| Letter 4800C (proposed change from AQC) | 30 days from the letter date | The IRS adjusts your tax, withholding and credits on its figures |
| Letter 566 / CP75 (exam) | The date printed on the letter | Credits disallowed; account adjusted with code 290 |
| Letter 3176C (frivolous screen) | 30 days from the letter date | $5,000 penalty per return assessed under IRC 6702 |
| Formal claim disallowance | Generally 2 years to challenge in court | The refund is permanently lost |
How long does a code 810 refund freeze take?
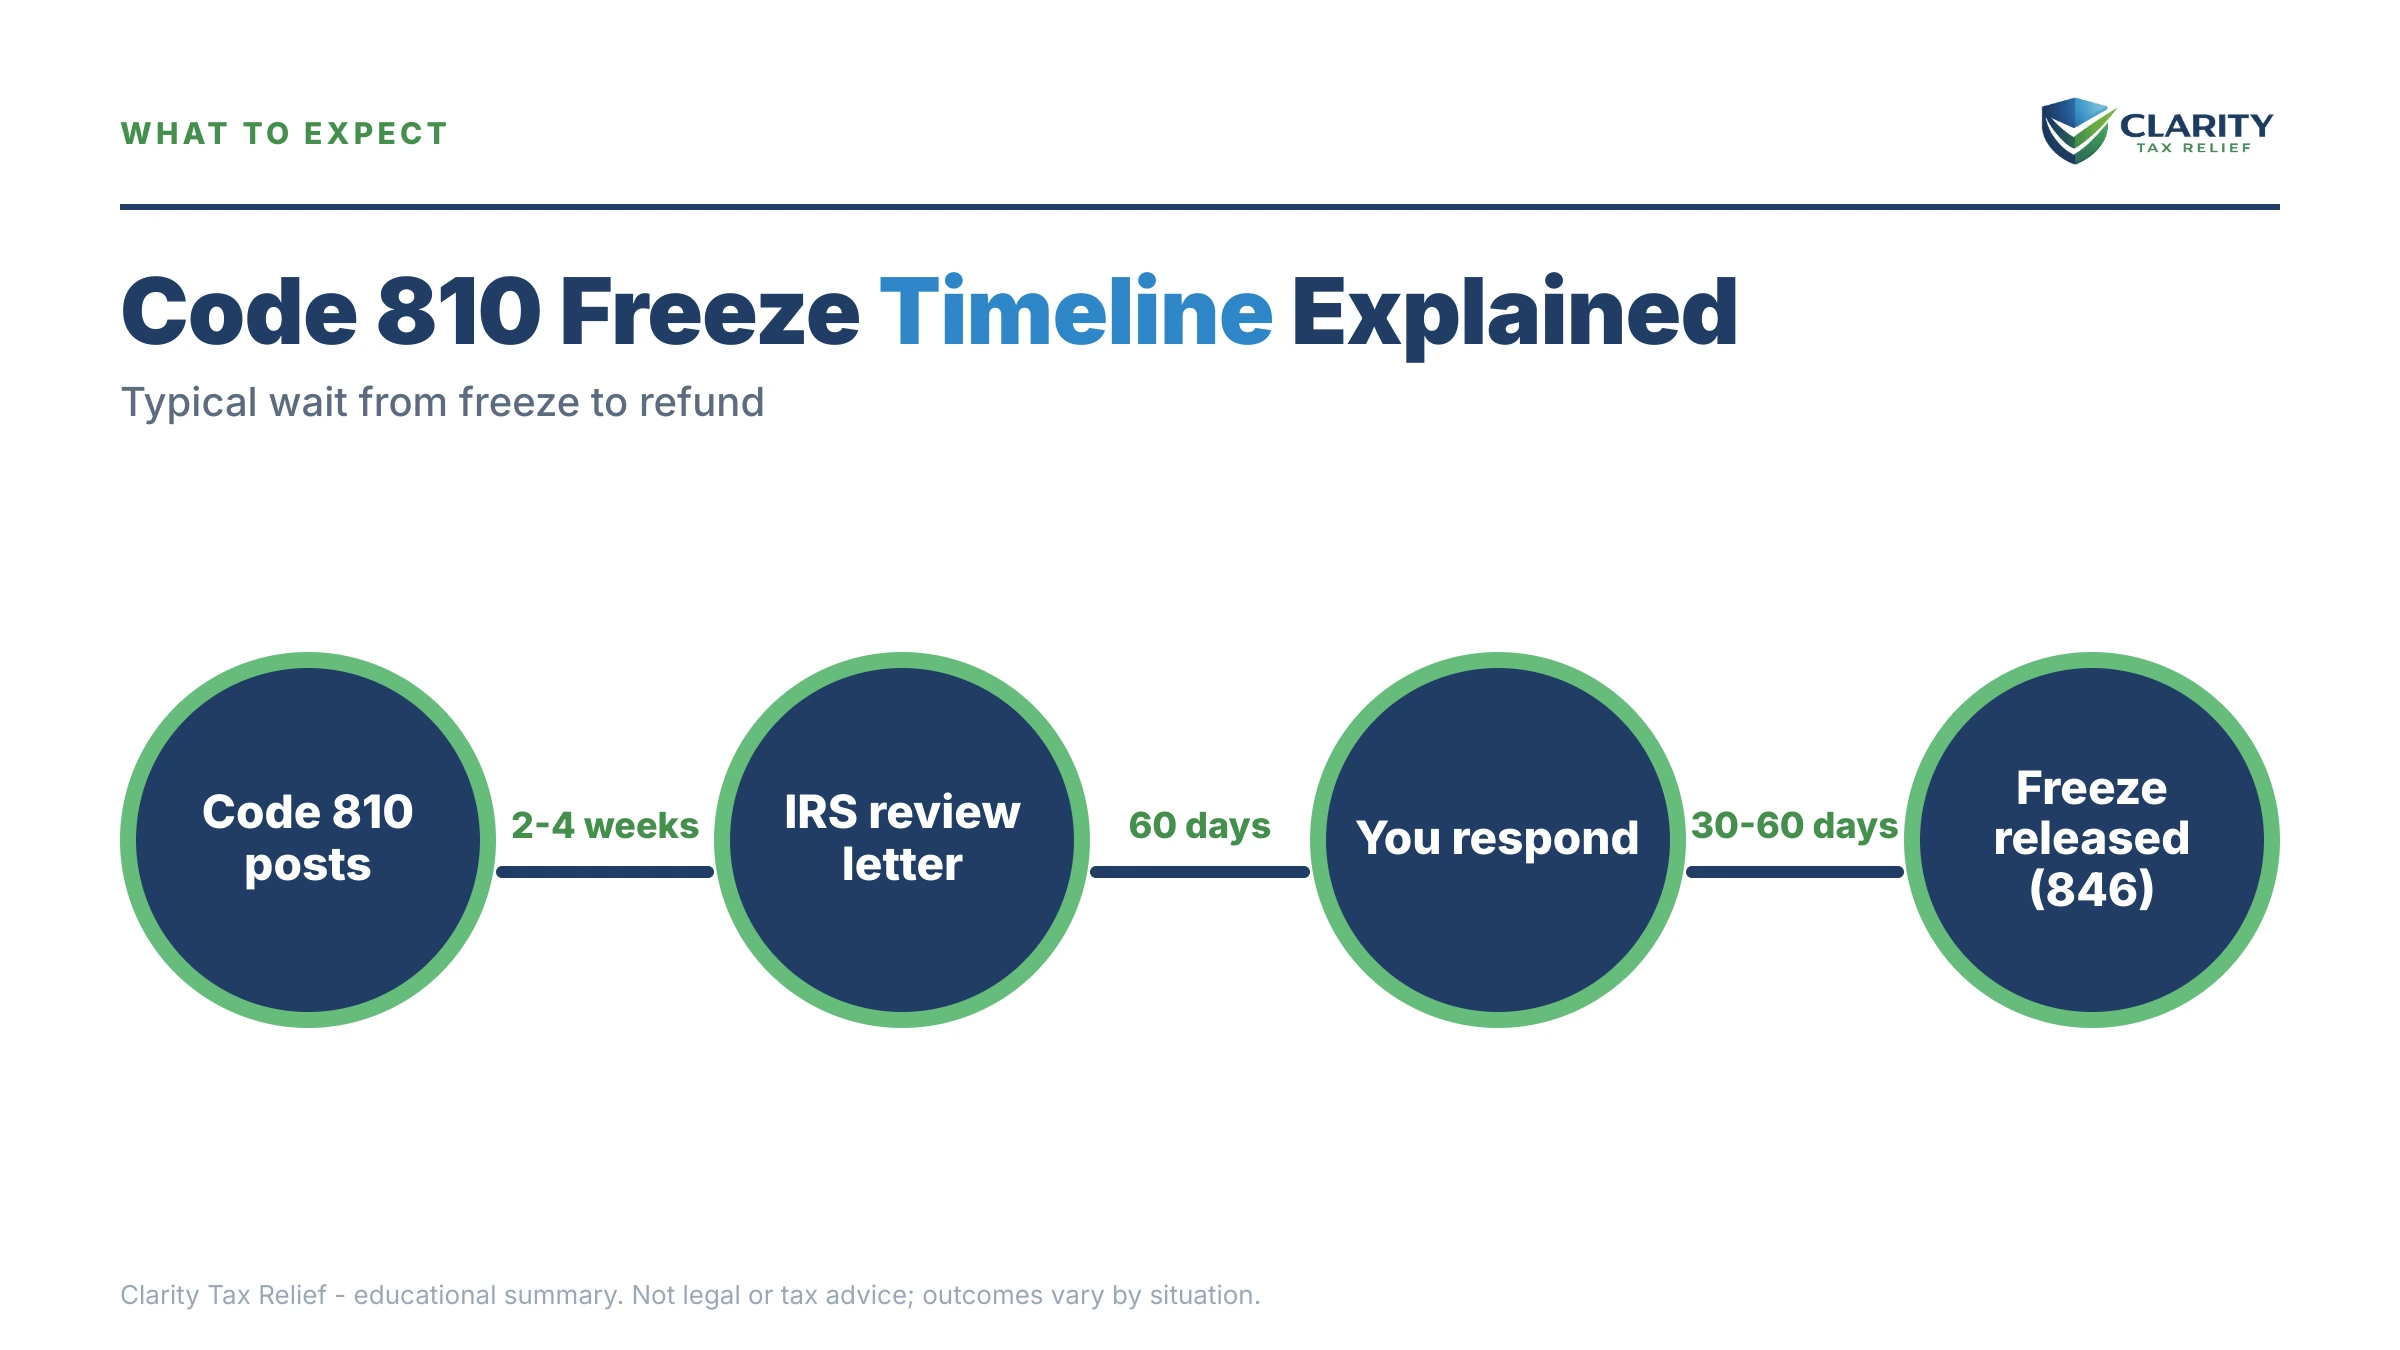
Nobody can promise a date, because the release comes from a person in the unit that set the freeze. What the IRS does publish is how long it asks you to wait at each stage. These are the figures from its own notice pages and manual, and they are the honest answer to "how long":
| Trigger | What the IRS says to expect | Where it says so |
|---|---|---|
| Identity verification (CP5071 series, 4883C, 5747C) | Up to 9 weeks to process the return after you verify; wait 2 to 3 weeks before checking Where's My Refund | IRS identity verification service page; Letter 4883C page |
| Return review, no documents requested (CP05) | Allow up to 60 days before contacting the IRS | IRS CP05 notice page |
| Income and withholding review (CP05A) | Allow 60 days after you send the documents | IRS CP05A notice page |
| Questionable credit review (AQC, Letter 4800C) | You have 30 days from the letter date to respond | IRS Letter 4800C page |
| Frivolous return screen (Letter 3176C) | 30 days to withdraw the position or file a corrected return | IRS Letter 3176C page |
| Freeze with no letter yet (RC 4) | Phone staff are told to advise allowing 180 days from first contact for a letter | IRM 21.5.6, -E freeze |
| Taxpayer Advocate request (Form 911) | You should hear back from your case advocate within 30 days | Taxpayer Advocate Service |
Two things follow from that table. First, the identity path is the fastest to the money, so if your letter is a CP5071 series notice or a 4883C, verify the same day you open it. Second, the "no letter" path is the one where waiting costs you the most, which is why the next section exists.
How to respond to a code 810 refund freeze, step by step
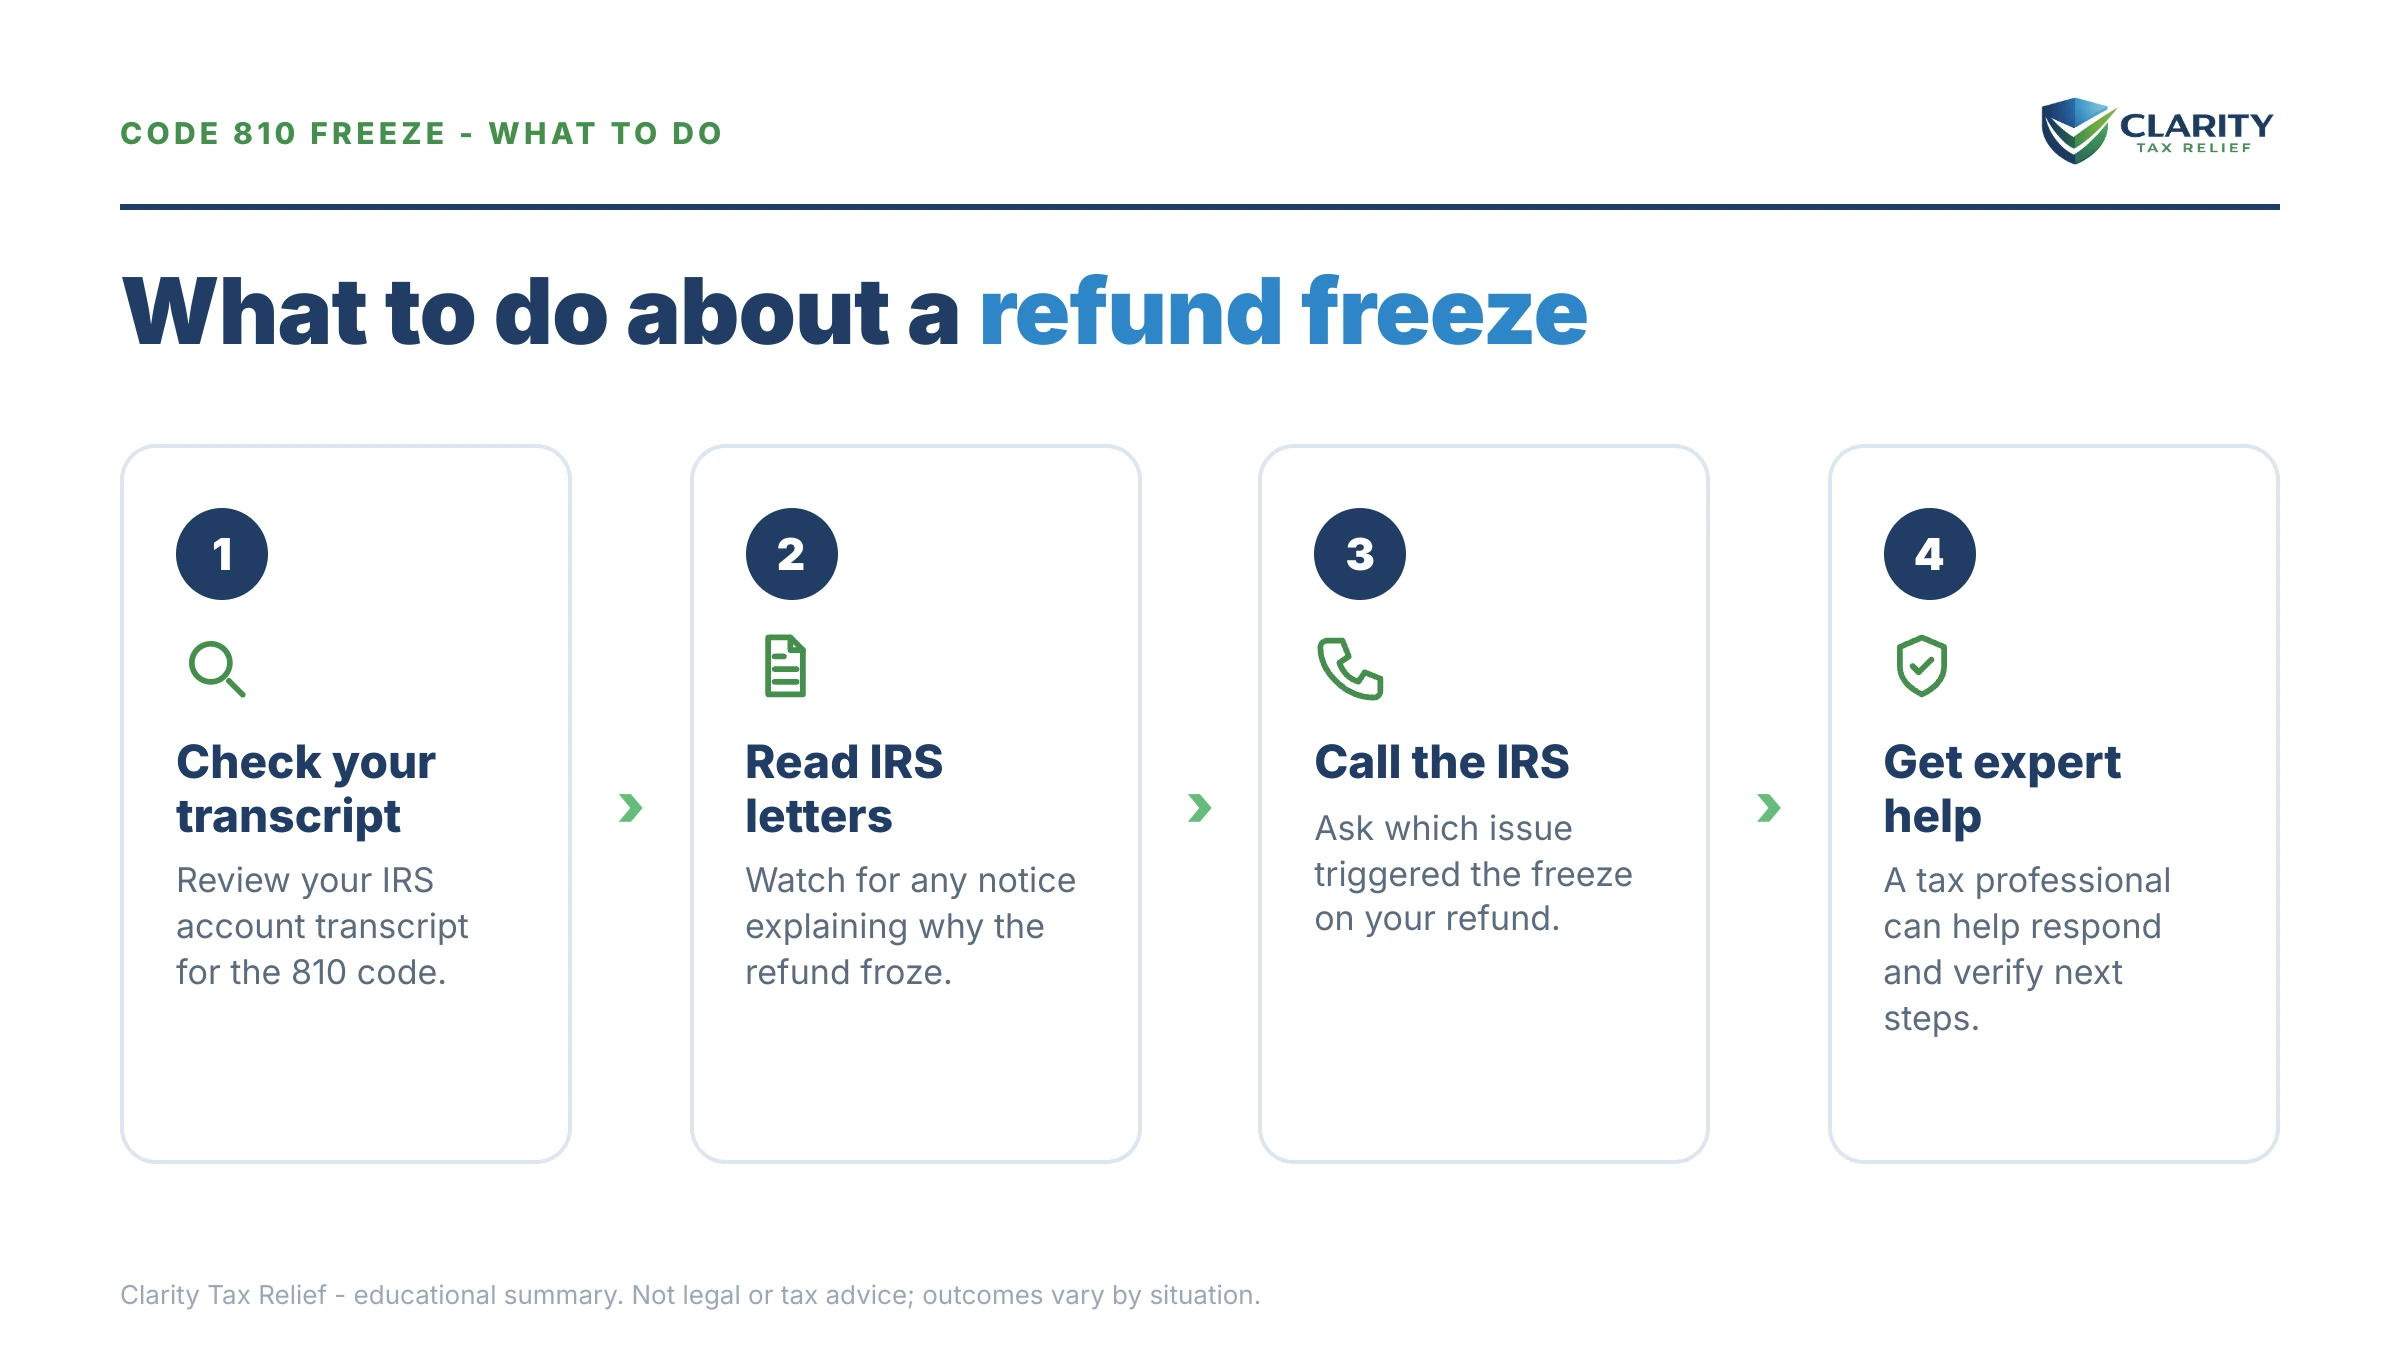
- Pull your free account transcript. Log in at IRS.gov and open the account transcript for the frozen year. Note every code and date near the 810. A 971 means a notice went out, 420 or 424 means Examination, and 811 means the freeze is already released.
- Check your mail and IRS online account for a letter. The letter names the unit that froze your refund and the exact fix: identity verification, documents, or an exam response. The date printed on it is your real deadline.
- Do exactly what the letter asks, before its printed date. Verify identity through the letter's instructions, or send the requested pay stubs, employer letter, or credit documentation. Keep copies of everything you submit.
- Call the IRS if no letter arrives within about 30 days. Call the individual line at 800-829-1040 and ask which function placed the 810 freeze. Knowing whether it is identity, review, or exam tells you the release path.
- Amend if the return claims credits you do not qualify for. If a preparer added a fuel tax credit or another credit you never earned, filing Form 1040-X to correct the return is how you head off a disallowance and a possible $5,000 frivolous-return penalty.
- Escalate to the Taxpayer Advocate if you are stalled or in hardship. File Form 911 when the frozen refund is causing economic harm or the IRS has missed its own timelines with no explanation.
What does an 810 refund freeze with no letter mean?
Clarity Tax Relief tells clients not to read the silence as bad news. An 810 freeze frequently posts weeks before any letter explains it. The code is automated; the mail is not. The IRS manual is candid about the gap: for the preventive frivolous-return screen, its own phone staff are told to "advise the taxpayer to allow 180 days from the date of the first contact on this issue for a letter to be issued." That is the official answer to "why no letter," and it is not a comfortable one.
Do not read the silence as either good news or a dead end. Check your IRS online account for digital copies of notices, confirm your mailing address is current (a moved household is a common reason "no letter" arrived), and if a month passes with nothing, call 800-829-1040 and ask which unit set the freeze and what its responsibility code is. Our 188-call study of IRS hold times shows when the line answers fastest. Acting on the trigger, rather than waiting for paper, is what shortens the hold.
When the freeze belongs to the Automated Questionable Credit unit
The IRS manual says a TC 971 with action code 128 "identifies RICS AQC involvement." AQC handles refundable-credit review. The letter that usually follows is a 4800C, proposing a change to your return. It gives you 30 days from its date to agree or to push back with documentation, through the Documentation Upload Tool, by fax to the number printed on it, or by mail. If you do not answer, the IRS says it will send a notice requesting more documents or explaining the adjustments it made to your tax, withholding and credits, and at that point the refund is being taken away rather than held. Call the number printed on the 4800C, not the general line, with the letter in front of you.
Common code 810 mistakes
- Reading the $0.00 as a refund of zero. The 810 is a flag, not a dollar transaction. The refund it holds is the amount on your other lines.
- Calling to demand the refund before knowing the trigger. The release comes from the unit that set the freeze, and each trigger has a different fix.
- Treating silence as resolution. The freeze posts instantly and the letter can lag by months. It never times out in your favor.
- Missing the printed response date. Code 810 has no deadline of its own, but the letter does, and missing it turns a hold into a disallowance.
- Leaving fabricated credits on the return. If a preparer claimed credits you never earned, Form 1040-X is how you head off a $5,000 frivolous-return penalty.
- Sending a W-2 to answer a CP05A. The notice page says not to. It wants pay statements, an employer letter on letterhead, or a benefits statement.
Can you handle this yourself, or does help change the outcome?
Many 810 freezes are a do-it-yourself fix. If your letter is a straightforward identity verification and the return is accurate, verify and wait. No professional needed. Same if a CP05A wants pay stubs you have in a drawer.
Experienced help earns its cost in four situations: an exam of refundable credits where thousands ride on how eligibility is documented. A return where a preparer claimed credits you now realize were bogus (the frivolous-penalty exposure makes the correction sequence matter). A freeze that has sat for months with no letter and no explanation. And any 810 layered on top of other problems (unfiled years, a balance due on another year, or an identity-theft return filed in your name). The order you fix things in changes what you collect, and Clarity Tax Relief's review of the transcript before you respond costs nothing.
Terms on your transcript, decoded
- Refund freeze: a hard hold that blocks payment of your refund until the unit that placed it manually releases it.
- Responsibility code: the one-digit tag on an 810 naming the reason (1 pre-filing notification, 2 tax shelter, 3 refundable credits, 4 frivolous-return screen, 6 and 7 preventive income and identity reviews).
- TC 811: the release transaction, the mirror image of 810. Document 6209 says it reverses the 810 in whole or in part, and an 811 for zero releases all the credit.
- RICS / RIVO: Return Integrity and Compliance Services and its Return Integrity Verification Operations, the IRS function that screens returns for identity and refund fraud before paying.
- AQC: the Automated Questionable Credit program inside RICS, which reviews refundable credits by mail and signals its involvement with a 971, action code 128.
- Frivolous return: a return taking a position the IRS deems baseless. Fabricated credits are the classic example, and the penalty is $5,000 per return under IRC §6702.
- Cycle code: the eight-digit code showing which weekly processing cycle your account updates in, useful for knowing when to re-check the transcript. See what day transcripts update.
Code 810 refund freeze questions, answered
What does code 810 mean on an IRS transcript?
Code 810 is a refund freeze. The IRS's own code book (Document 6209) defines TC 810 as a transaction input "to freeze the module from refunds, offsets and credit elect." The IRS manual says it is placed by Compliance or by Return Integrity and Compliance Services (RICS), and only that unit can release it with code 811. You do not owe anything because of an 810 and nothing is being seized.
What does 810 refund freeze $0.00 mean?
The $0.00 next to code 810 is normal. The 810 is a flag on the account, not a tax or a credit, so it carries no dollar amount of its own. The refund it is holding is the number shown on your code 846 line once one posts, or the credits on your 806, 766 and 768 lines minus the tax on code 150. A zero on the 810 line does not mean your refund was reduced to zero.
Why is there an 810 refund freeze but no letter?
The code posts the moment a unit flags the return. The letter is generated later, and for the frivolous-return screen (responsibility code 4) the IRS manual tells its own phone staff to advise taxpayers to allow 180 days from first contact for a letter to be issued. Check your IRS online account for digital notices, confirm your mailing address is current, and if about a month passes with no letter and no transcript movement, call 800-829-1040 and ask which function set the freeze.
How long does a code 810 refund freeze last?
There is no fixed clock. It lasts until the unit that set it posts code 811. After a successful identity verification the IRS says it may take up to 9 weeks to process the return. A CP05 review asks you to allow up to 60 days before contacting the IRS. A CP05A asks you to allow 60 days after you send the documents. Freezes that become an examination can run several months.
Does code 810 mean I am being audited?
Not by itself. Many 810 freezes end with an identity verification or a document review and never become an audit. If code 420 or 424 posts after the 810, the IRS manual says Examination is involved. A code 971 with action code 128 means the Automated Questionable Credit unit has the case, which is a correspondence review of refundable credits rather than a field audit.
What does code 811 mean after code 810?
Code 811 reverses the 810 in whole or in part. Document 6209 says an 811 with a zero amount reverses the 810 and allows release of all credit, as long as no other freeze is on the account. It does not pay you by itself. Watch for code 846, which is the refund being issued with a date next to it. If 811 posts and no 846 follows within a few weeks, call and ask whether anything else is holding the refund.
Can I call the IRS to remove code 810?
The general line at 800-829-1040 cannot release an 810 set by another unit. The call is still worth making, because the representative can tell you which function placed it, and that decides your fix. If you have received a Letter 4800C, call the number printed on that letter rather than the general line. Have the transcript and the letter in front of you.
Can the Taxpayer Advocate Service help with an 810 refund freeze?
Yes, in two situations. One is financial hardship, which TAS calls economic harm: losing housing, food, utilities or transportation to work. The other is a delay past normal processing time with no IRS response. You ask with Form 911 or by calling 877-777-4778, and TAS says you should hear back from your assigned case advocate within 30 days.
The bottom line on a code 810 refund freeze
Code 810 is a hard hold placed by a compliance unit, and only that unit's code 811 lifts it. The $0.00 is normal. Find the trigger first, using the codes near the 810 and the letter that follows, then do exactly what that letter asks before its printed date. Identity verification is the fastest path back to the money; a credit exam turns on documentation; a return with credits you never earned needs a Form 1040-X. If no letter comes within a month, call and ask which function set the freeze, and use Form 911 if the delay is causing hardship.
Your next 24 hours
- Pull the transcript for the frozen year at the IRS Get Transcript page and write down every code and date near the 810, especially any 971, 420, or 811.
- Gather your file: the tax return, every IRS letter you have received, your W-2s and 1099s, and, if credits are involved, proof of each child's residency and relationship. If you got an identity notice, the IRS Identity and Tax Return Verification Service is where the verification happens. For hardship escalation, start at the Taxpayer Advocate Service.
- Get a free case review. Send us the transcript and letters through the 2-minute form or call (888) 825-7779. An 810 does not lift on its own. The right response to the right unit is what turns a frozen refund into a paid one.
Sources: TC 810 and 811 definitions are in IRS Document 6209, Section 8A; the -E freeze procedures, responsibility codes and the 180-day instruction are in IRM 21.5.6; response windows come from the IRS pages for CP05A, Letter 4800C and Letter 3176C.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.