IRS Penalties
IRS Most Common Penalties in 2026: Rates, Caps, and How to Remove Them
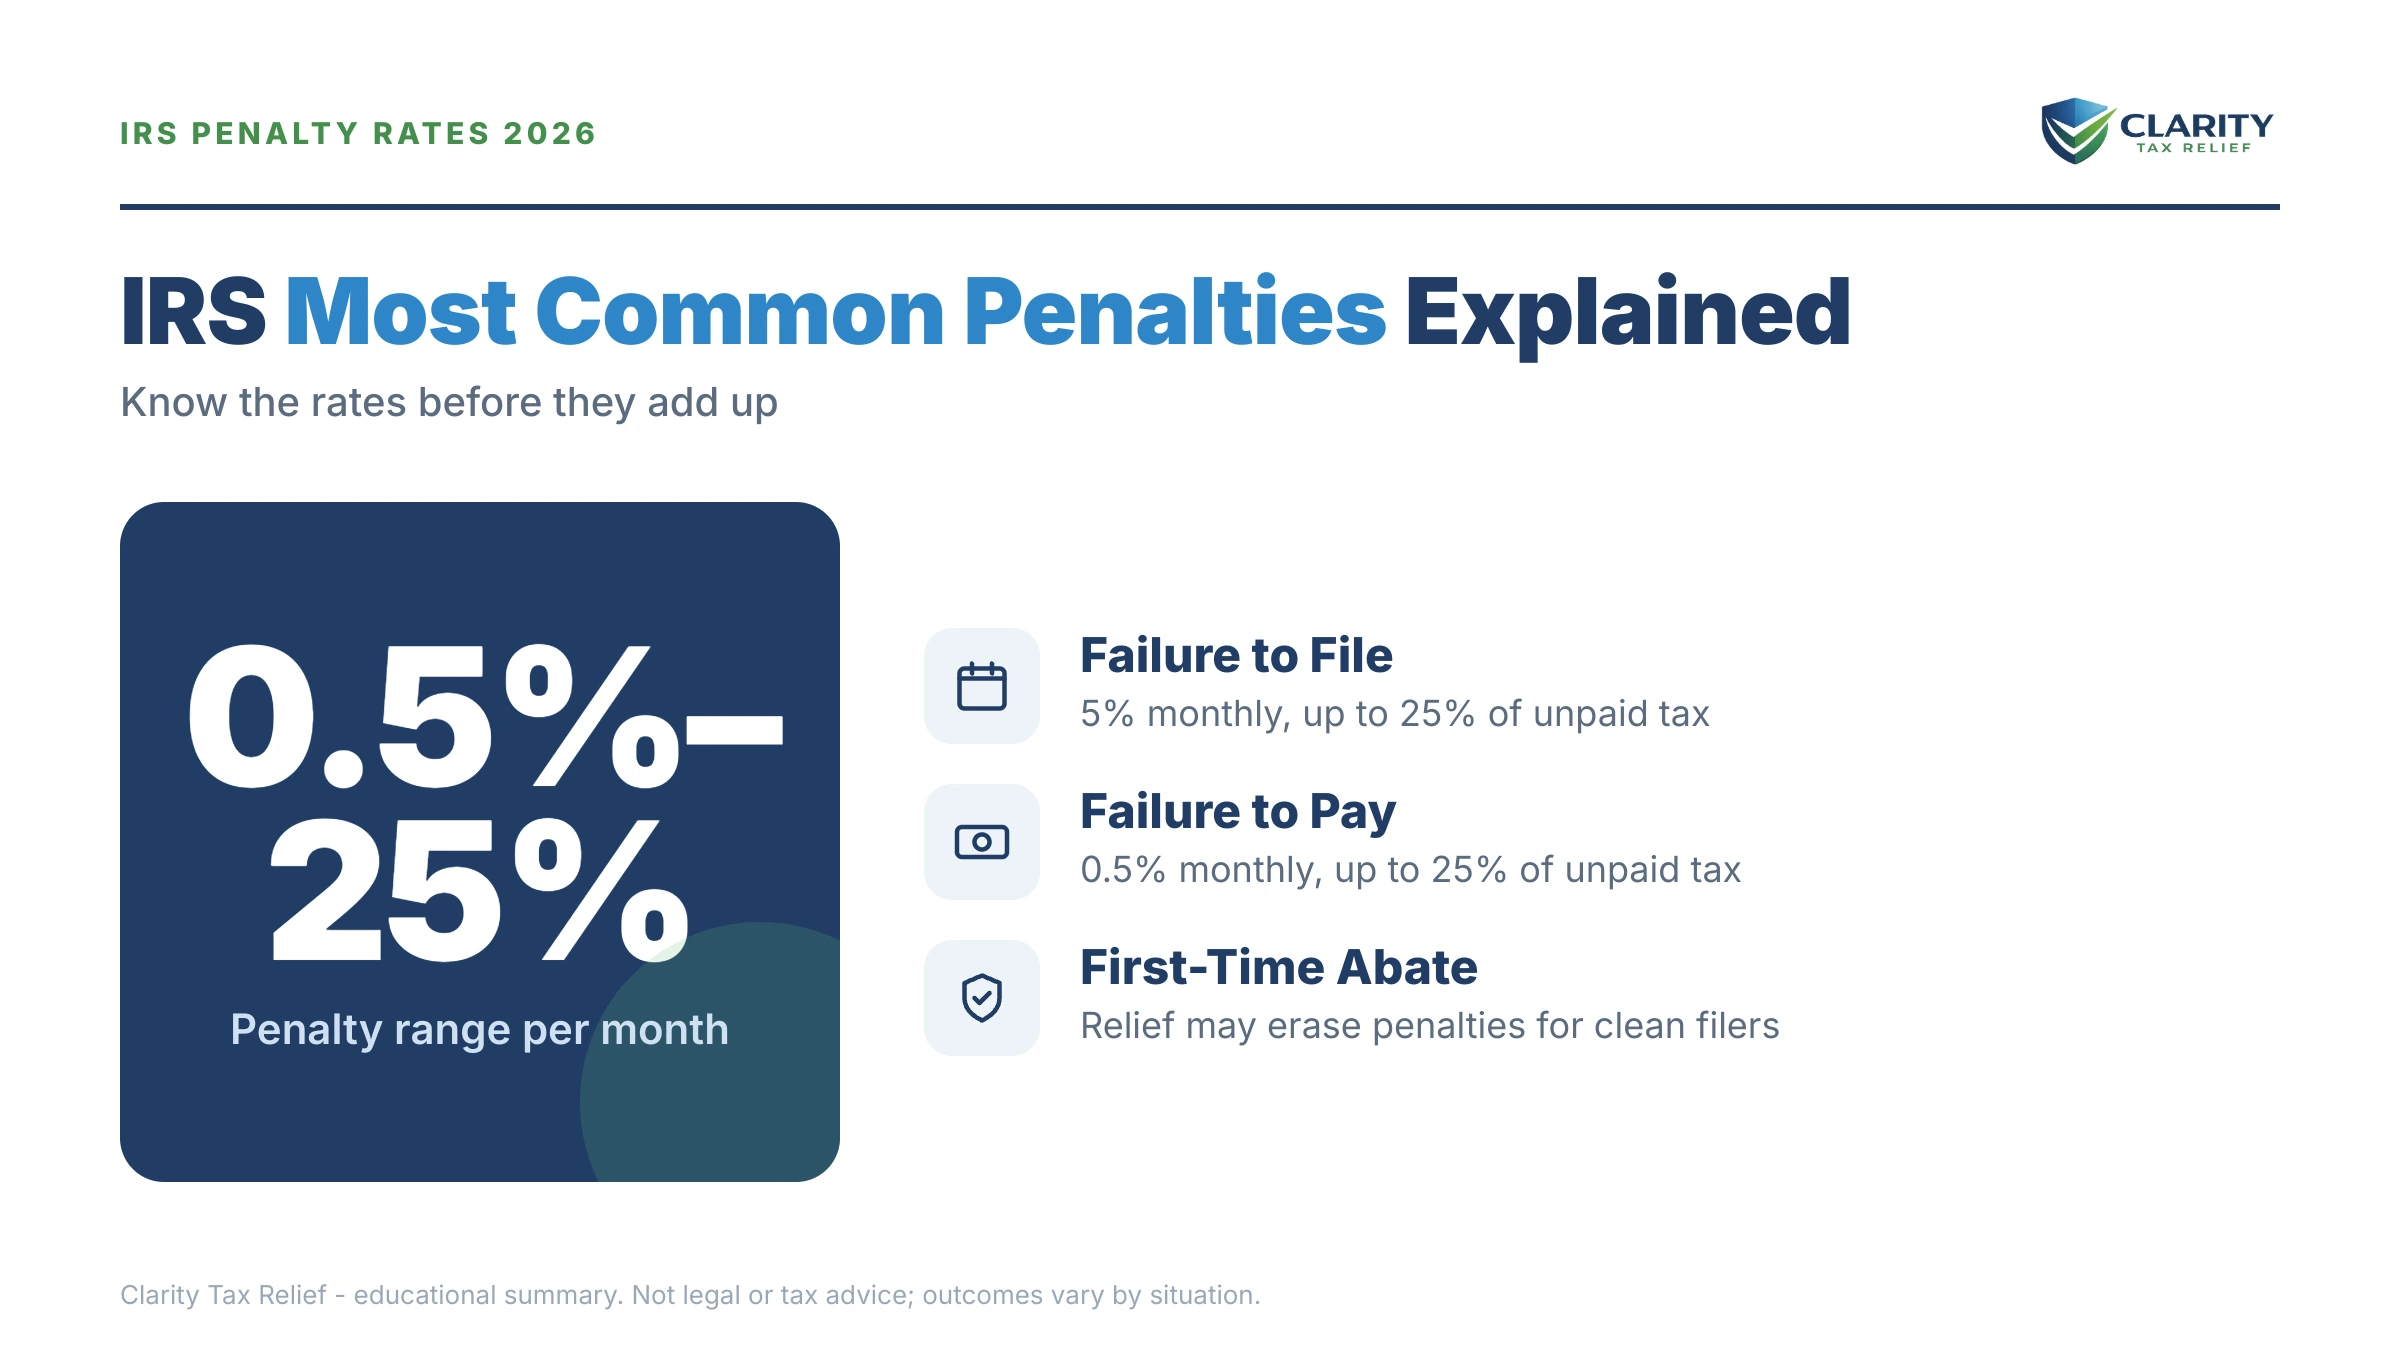
The short answer: the most common IRS penalties are the failure-to-file penalty (5% of unpaid tax per month, capped at 25%), the failure-to-pay penalty (0.5% per month, capped at 25%), and the estimated-tax underpayment penalty. Filing late costs 10 times more per month than paying late, and most first-time penalties can be removed on request.
What this guide covers: the seven IRS penalties people run into most, what each one costs and where it caps out, how they push a balance toward a levy, and the ways to get them removed.
Your notice says $8,900, but the tax you didn't pay was closer to $6,000, and now the IRS is talking about levying your bank account over the whole thing. That gap is penalties and interest, added by computer, month after month. The notice leaves something out. Every penalty below has a fixed rate, a hard cap and, in most cases, a removal path.
⏱ The clock that's running: penalties don't have one deadline. They have a meter. The failure-to-pay penalty adds another 0.5% of your unpaid tax every month, and interest compounds daily on the whole balance, penalties included. If a levy notice is in your stack, the date printed on that notice controls everything else.
Why is your balance bigger than the tax you owed?
IRS penalties are assessed by computer the moment a return posts late or a payment due date passes. No human reviews your file before the charge lands. That's why the amount on your notice rarely matches the number you remember from your return.
Penalties arrive in different ways. Some post automatically when your return is processed (late filing, late payment). Some come with an adjustment, since a CP2000 or audit that adds tax often adds a 20% penalty on top. Others are calculated once a year, like the estimated-tax penalty for people with 1099 or self-employment income.
Most people don't expect this part: penalties themselves accrue interest from the day they're assessed. A penalty added two years ago has been quietly growing ever since. For the full compounding math on an aging balance, see how big IRS penalties get on back taxes.
Which IRS penalties are the most common?
Seven penalties account for the overwhelming majority of dollars the IRS adds to individual and business accounts each year. Two of them, failure-to-file and failure-to-pay, do most of the damage.
| Penalty | Rate | Maximum | Main relief path |
|---|---|---|---|
| Failure-to-file | 5% of unpaid tax per month | 25%, plus a minimum dollar penalty after 60 days | First-Time Abate / reasonable cause |
| Failure-to-pay | 0.5% per month (1% after final levy notice; 0.25% on a payment plan) | 25% | First-Time Abate / reasonable cause |
| Estimated-tax underpayment | Federal interest rate applied to each quarter's shortfall | No flat cap — runs until paid or the filing deadline | Form 2210 exceptions/waiver |
| Accuracy-related | 20% of the underpayment (one-time) | 20% (40% in limited cases) | Reasonable cause; exam appeal |
| Failure-to-deposit (payroll) | 2%–15% of the late deposit, tiered by days late | 15% | First-Time Abate / reasonable cause |
| Civil fraud | 75% of the fraud-related underpayment (one-time) | 75% | Rarely abated — professional defense |
| Trust Fund Recovery Penalty | 100% of unpaid trust-fund taxes, assessed personally | 100% | Responsible-person defense / appeal |
Failure-to-file: the expensive one
The failure-to-file penalty runs 5% of your unpaid tax for each month (or part of a month) your return is late, up to 25%. Even one day into a new month counts as a full month. Once a return is more than 60 days late, a minimum dollar penalty applies, an inflation-adjusted amount that hits even small balances. When it overlaps with the failure-to-pay penalty, failure-to-file drops to 4.5% so the two together equal 5% per month. The full comparison lives in our guide to the failure to file penalty vs failure to pay. The practical takeaway: file even when you can't pay a dollar.
Failure-to-pay: the slow one
The failure-to-pay penalty runs 0.5% of the unpaid tax per month, up to 25%. It's slow, and it has two gear changes. Enter an installment agreement in good standing and it drops to 0.25% per month. Ignore the notices until the IRS issues its final intent-to-levy notice and it doubles to 1% per month. Same debt, four times the monthly cost, depending entirely on how you respond.
Estimated-tax underpayment: the one nobody expects
This penalty hits people who had no withholding (self-employed workers, 1099 contractors, landlords, gig drivers) and didn't pay enough during the year. There's no flat percentage. It's computed like interest, at the federal underpayment rate, on each quarter's shortfall from the day it was due. You avoid it by hitting a safe harbor: paying at least 90% of this year's tax or 100% of last year's (110% if your income was over $150,000). If it's already on your notice, our guide to the underpayment penalty for estimated taxes covers the Form 2210 exceptions that can reduce or erase it.
Accuracy-related: the 20% add-on
When the IRS adjusts your return, usually after a CP2000 or an audit, it often adds 20% of the extra tax for negligence or "substantial understatement" (an understatement bigger than 10% of the correct tax or $5,000, whichever is greater). This one is a single hit, unlike the monthly penalties, and First-Time Abate does not cover it. The defense is reasonable cause and good-faith reliance. Full breakdown in our accuracy related penalty guide.
Business and specialty penalties
If you run payroll, the federal tax deposit penalty tiers up fast: 2% for deposits 1–5 days late, 5% for 6–15 days, 10% beyond that, and 15% if it's still unpaid after the IRS demands it. Worse, when withheld payroll taxes go unpaid, the Trust Fund Recovery Penalty can make owners, officers and even bookkeepers personally liable for 100% of the trust-fund portion. At the severe end, the IRS civil fraud penalty is 75% of any underpayment the IRS can prove was fraudulent. International filers face fixed-dollar information penalties, $10,000-range charges per unfiled Form 5471 or FBAR-related form, even when no tax was due. See undisclosed foreign account penalties for the fix paths.
And interest: the charge that isn't a penalty
Interest is a separate statutory charge, so technically it isn't a penalty. It behaves like one on your notice, though. It compounds daily on tax, penalties and prior interest, at a rate the IRS resets quarterly. The law gives the IRS almost no discretion to waive it. There are two real openings. Interest attached to an abated penalty is removed automatically, and under IRC §6404 interest caused by IRS error or delay can be abated on request. Interest tied to the tax itself stays until the tax is paid.
What happens if you ignore IRS penalty notices?
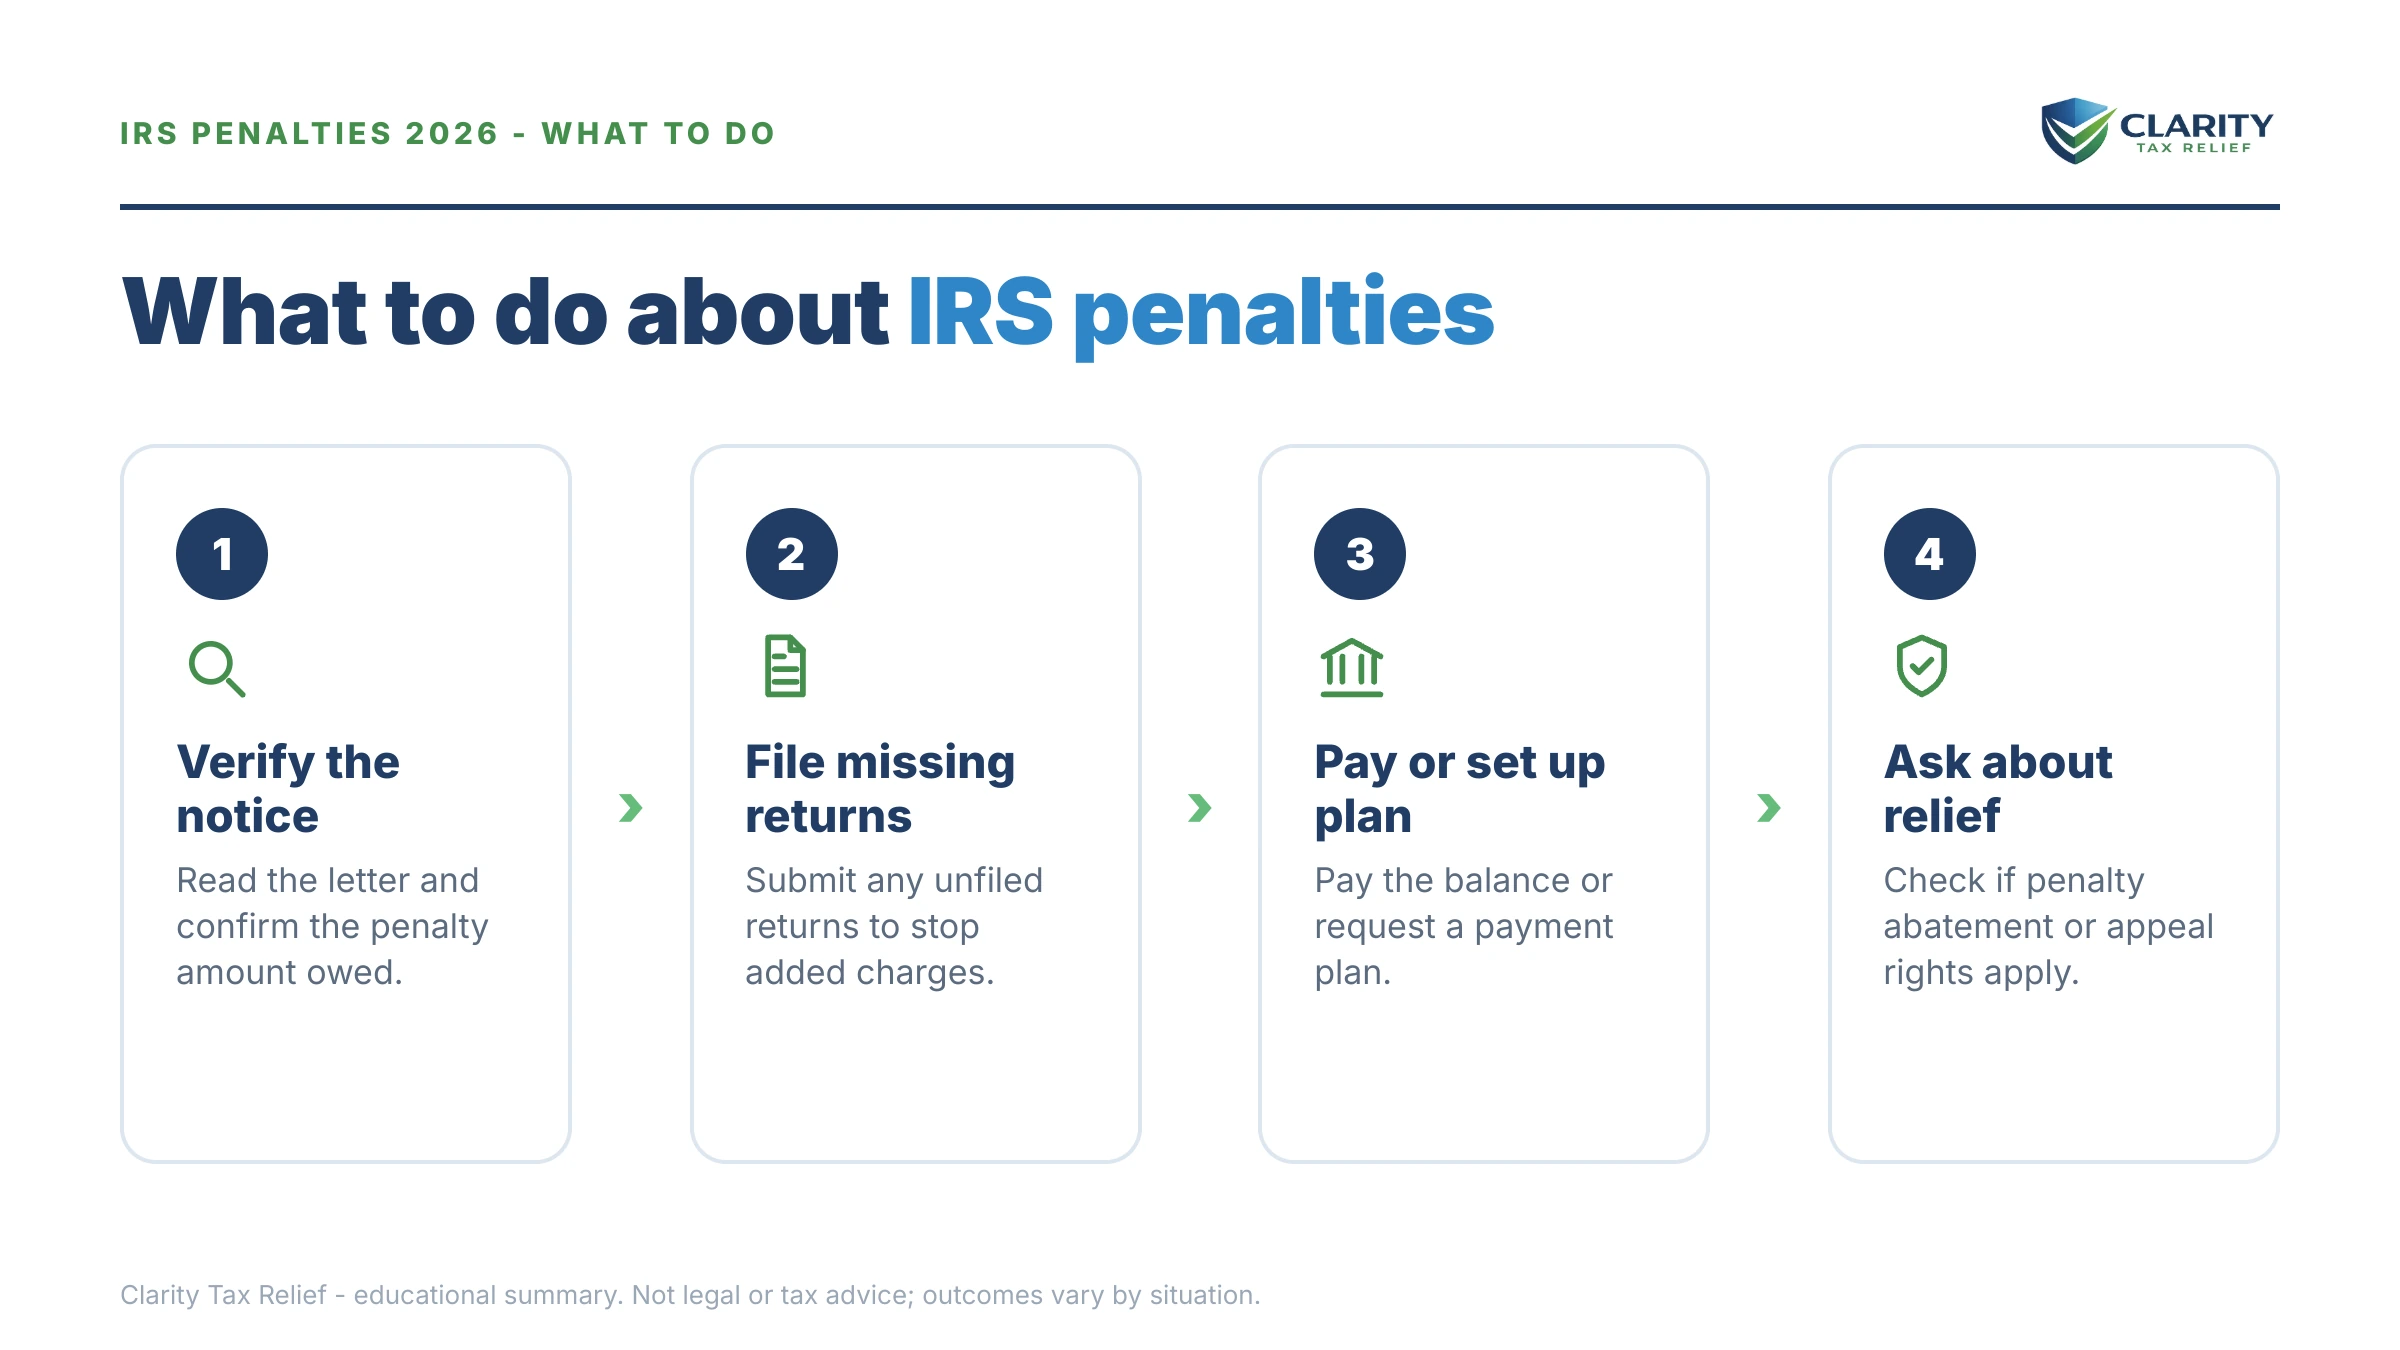
An unpaid penalty rides the same collection track as unpaid tax, and the sequence ends at your bank account or paycheck. The stages run in a fixed order:
- Assessment + CP14: the penalties post to your account and the first bill arrives, typically giving you about 21 days to pay or make arrangements.
- CP501 / CP503: reminder bills. Each passing month adds another 0.5% failure-to-pay penalty plus daily-compounding interest.
- CP504: notice of intent to levy your state tax refund under IRC §6331(d). A federal tax lien becomes a live possibility.
- LT11 / Letter 1058: final notice of intent to levy, starting a 30-day clock to request a Collection Due Process hearing on Form 12153.
- Levy: bank funds are frozen and held 21 days before being sent to the IRS. A wage levy repeats every paycheck until released, and Social Security can be levied at up to 15%.
Two things speed up at the back of this sequence. Once the final levy notice issues, the failure-to-pay rate doubles to 1% per month. And your options narrow from "pick the program that fits" to "stop the levy first, then fix the balance."
If you rent, skip the worry about liens on a house you don't own. Your exposure is your checking account and your paycheck. A bank levy that lands the week rent is due is how this sequence ends for a lot of renters, and the 21-day hold is the only window to reverse it before the money leaves.
One more 2026 reality: IRS staffing fell roughly 27% in 2025, so reaching a human takes longer than ever. Every notice above still comes from automated systems that never stopped. Silence from the IRS is processing lag. Nobody forgave anything.
| Notice | What it means | Your window |
|---|---|---|
| CP14 | First bill: tax + penalties + interest | Typically about 21 days from the notice date |
| CP501 / CP503 | Reminder bills; balance grows monthly | Pay or arrange before the sequence escalates |
| CP504 | Intent to levy your state tax refund | Act now — the next letter carries full levy power |
| LT11 / Letter 1058 | Final notice of intent to levy + appeal rights | 30 days to request a CDP hearing (Form 12153) |
| Levy | Bank funds held 21 days; wage levy continuous | Release possible via agreement, hardship, or appeal |
Penalties stacking on a balance you can't pay?
Whether you're staring at penalty lines on a CP14 or a levy notice already arrived, get it reviewed free. Penalties and interest accrue every month, and levy releases move fastest before the money leaves your account. An experienced tax professional will map which penalties come off and in what order — no pressure, no obligation.
How do you get IRS penalties removed?
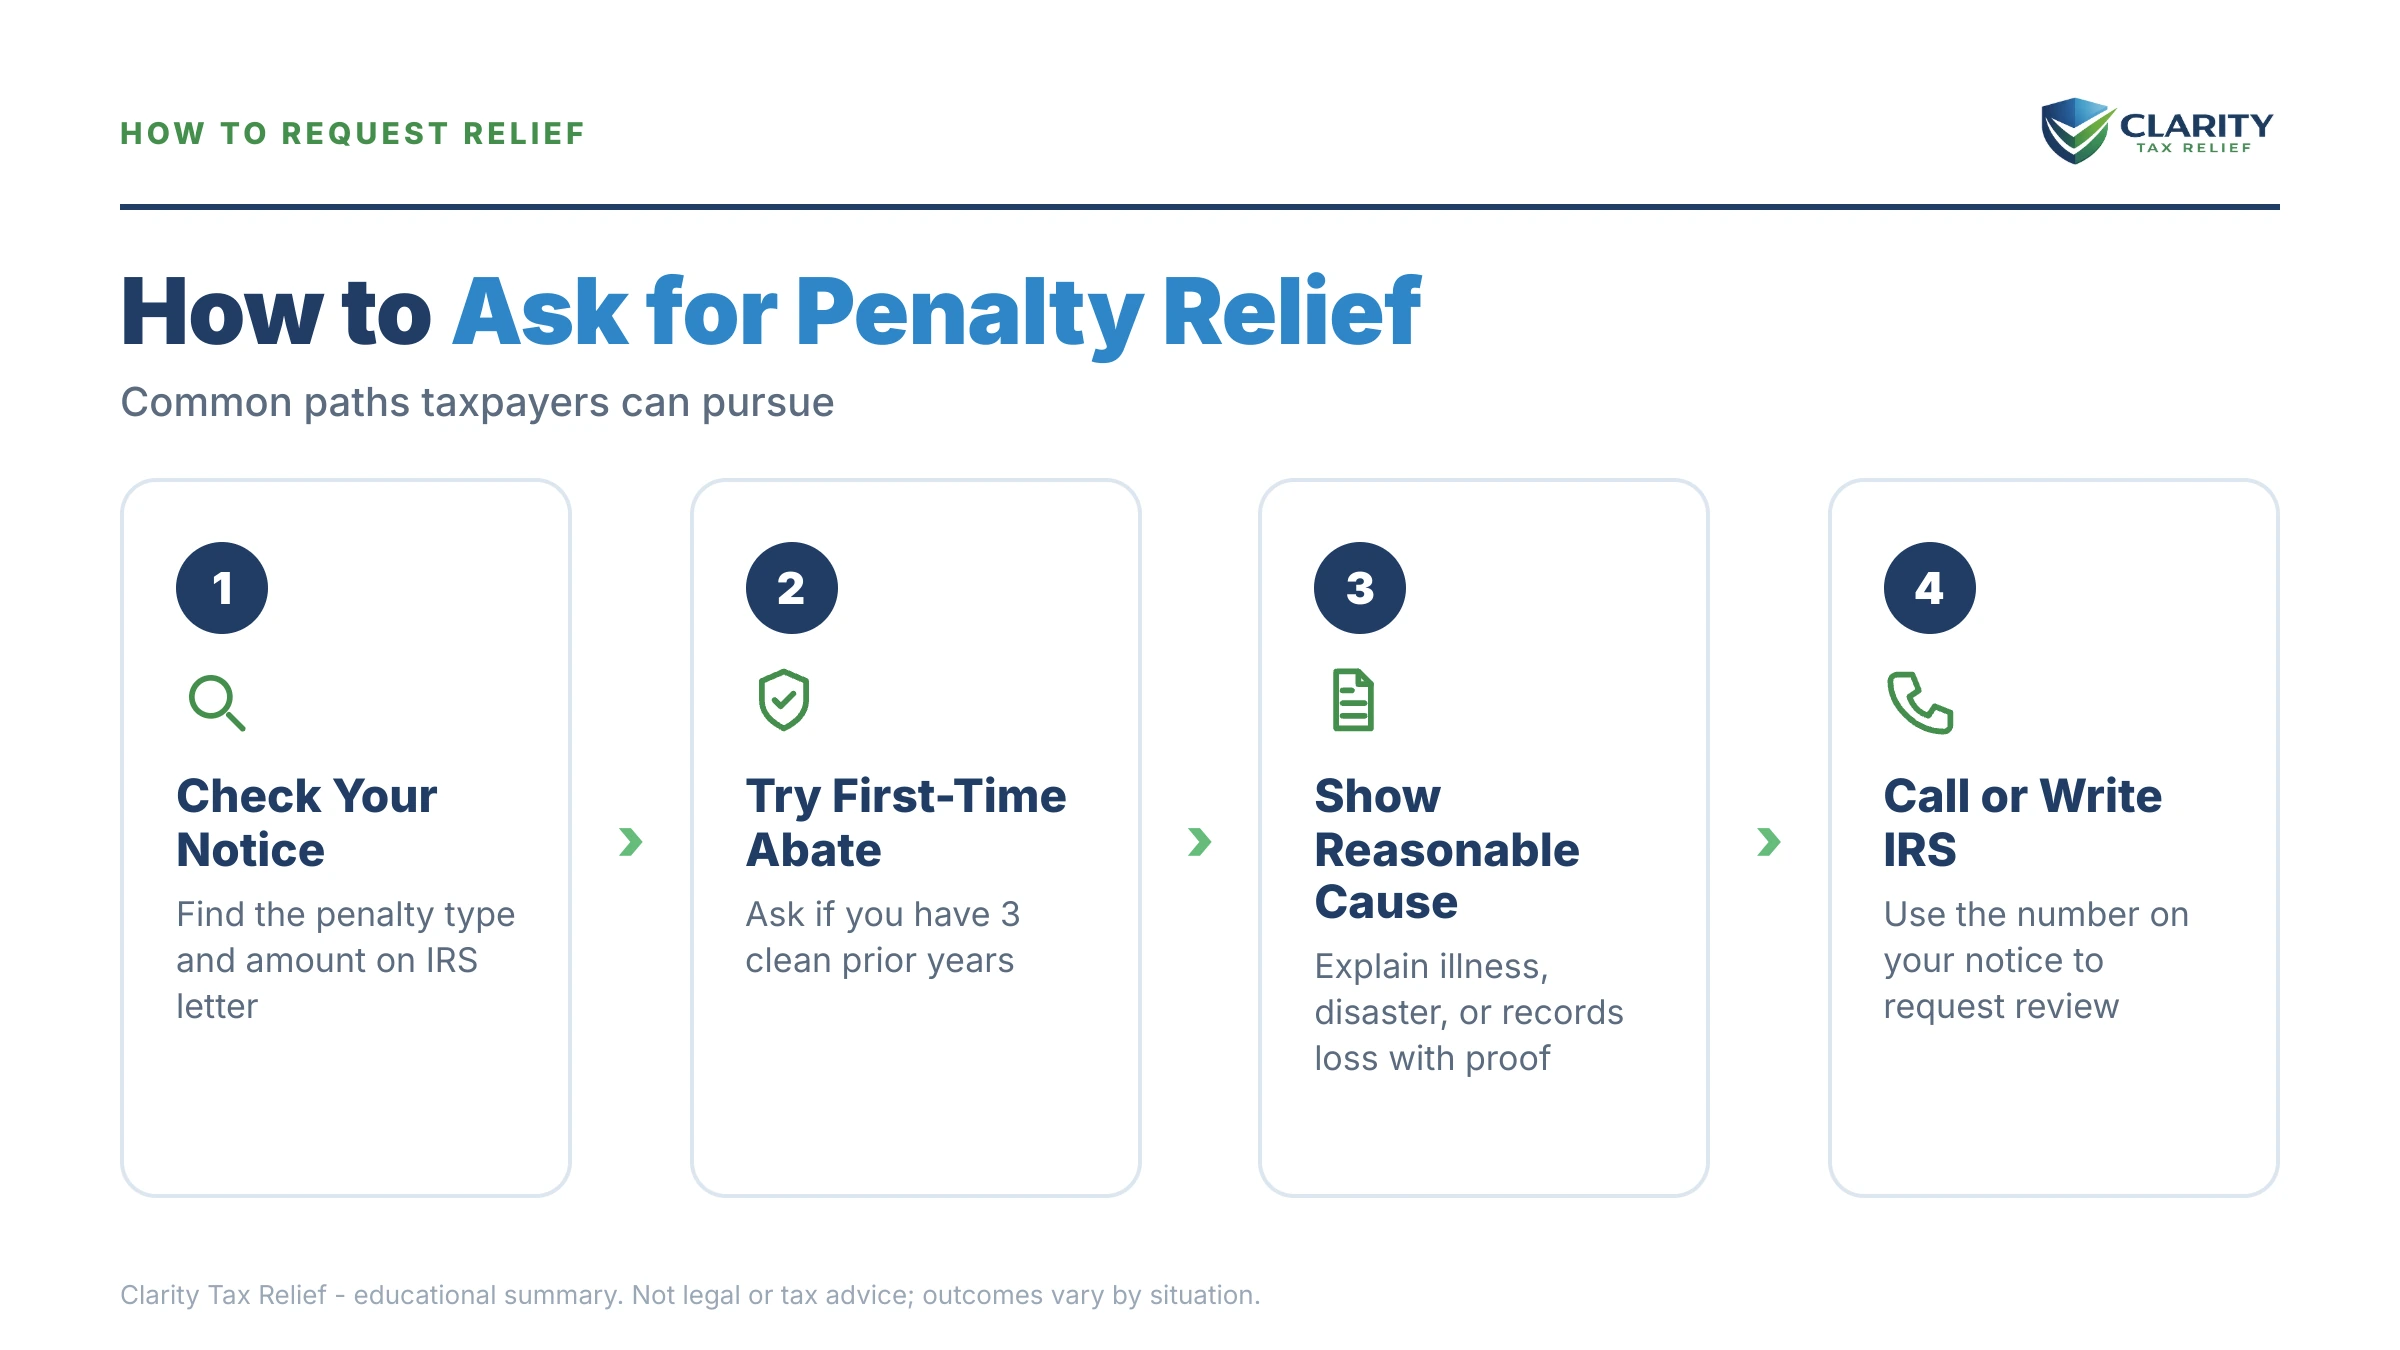
Penalty removal is routine. Most first-time failure-to-file and failure-to-pay penalties can be removed with a single request under First-Time Abate. The relief paths, in the order most people should try them:
- First-time penalty abatement: removes failure-to-file, failure-to-pay and deposit penalties if you had clean compliance for the prior three years and your filings are current. One phone call to the number on your notice is often enough.
- Automatic Exemption from Penalty (AEP): the IRS's replacement for First-Time Abate, rolling out in summer 2026. The IRS applies this relief automatically to qualifying accounts with a clean compliance history, no call or letter needed. Don't assume it covers you. Check your account transcript, and if a penalty is still showing, request relief the traditional way instead of waiting.
- Reasonable cause penalty abatement: for illness, death in the family, disaster, or other events beyond your control, documented in writing (a letter or Form 843). This is the path for accuracy-related penalties and repeat years that FTA can't reach.
- Form 2210 exceptions: the estimated-tax penalty has its own waiver rules for casualty, disaster, and retirement or disability circumstances, plus the annualized-income method for uneven earners.
- A payment arrangement: it leaves the penalties in place, cuts the failure-to-pay rate in half to 0.25% per month, and shuts down the levy track while it's in good standing. Interest keeps accruing on the full balance either way. Balances up to $50,000 can be set up online over as long as 72 months.
- Interest abatement: narrow, but real when IRS error or delay generated the interest.
Before you request anything, know your target. You can estimate how much of your balance is penalties and interest with our IRS penalty and interest calculator, then aim the right relief at the biggest line items.
| Relief option | Cost | Who qualifies | Typical timeline |
|---|---|---|---|
| First-Time Abate | Free | Clean compliance the prior 3 years; current filings done | Often decided on one phone call; written requests take longer |
| Automatic Exemption from Penalty (AEP) | Free — automatic | Clean-history test applied by the IRS, starting summer 2026 | No request needed; confirm on your transcript |
| Reasonable cause | Free (letter or Form 843) | Documented events beyond your control | Typically weeks to a few months |
| Form 2210 waiver/exceptions | Free | Casualty, disaster, retirement/disability; uneven income | Filed with the return or after assessment |
| Payment plan (FTP drops to 0.25%) | $0 for short-term (up to 180 days); setup fee tiers for monthly plans | Up to $50,000 sets up online, up to 72 months | Usually approved immediately online |
| Interest abatement (§6404) | Free | Only interest caused by IRS error or delay | Months; narrow eligibility |
How does $6,000 in tax become an $8,900 problem?
Say you owed $6,000, filed the return five months late, and it's now been about 20 months since the original due date. The case is hypothetical, and very typical. The buildup looks like this:
- Tax: $6,000
- Failure-to-file, 5 months at the net 4.5% rate (the overlap reduction): $6,000 × 22.5% = $1,350
- Failure-to-pay, 20 months × 0.5%: $6,000 × 10% = $600
- Interest compounding daily on all of it at recent rates: roughly $950
- Balance on the notice: ≈ $8,900
Nearly a third of that balance is something other than tax. Now run the fix in the right order. If the prior three years were clean, First-Time Abate can remove the $1,950 in penalties. The interest charged on those penalties comes off with them, dropping the balance to roughly $6,950. Spread over a 72-month plan, that's about $97 a month, versus roughly $124 on the unabated balance, and the failure-to-pay rate falls to 0.25% going forward. Same debt, a materially different result, and the difference comes from sequence: abate first, then arrange payment.
How to respond to IRS penalties, step by step
- Identify every penalty. Pull your IRS account transcript or read the breakdown box on your notice. You can't remove a penalty you haven't named.
- File anything unfiled. Filing stops the 5%-per-month failure-to-file penalty from growing, even if you can't pay a dollar yet.
- Request penalty relief. Ask for First-Time Abate by phone or send a reasonable-cause request in writing. Relief works on unpaid balances too, along with amounts you've already paid.
- Set up a payment arrangement. An installment agreement cuts the failure-to-pay rate to 0.25% per month and generally stops levy action while it's active.
- Confirm the relief posted. Check your next notice or transcript for the reduced balance, and appeal any denial within the window printed on the denial letter.
When can you handle penalties yourself, and when does help change the outcome?
You can request first-time penalty abatement yourself with one phone call, no professional required. Handle it solo when it's one tax year, you agree with the tax itself, the penalties are failure-to-file or failure-to-pay, and your prior three years were clean. The same goes for a simple payment plan. If you can pay within 180 days, or the balance sets up cleanly online, do it yourself at IRS.gov/payments. The IRS's own penalty pages at IRS.gov penalties explain each charge in its own words.
Experienced help earns its cost in other situations:
- A final levy notice has issued or your account is already frozen.
- Several years are unfiled or penalized. FTA covers only one period, so the stacking strategy matters.
- The penalty came out of an exam (accuracy-related or fraud), where the defense is evidence and a phone call won't do it.
- Payroll or trust-fund exposure, where the penalty follows you personally.
- Foreign information penalties, where the wrong submission procedure can lock in five-figure charges.
If money is tight, the Taxpayer Advocate Service and Low Income Taxpayer Clinics offer free help for qualifying taxpayers. The simpler your penalty history, the less you need anyone, including us.
Not sure which side of that line you're on? A free penalty review with an experienced tax professional at (888) 825-7779 takes about two minutes to start and costs nothing to find out.
Terms on your penalty notice, decoded
- Assessment: the moment a tax or penalty is officially recorded on your IRS account, which is what starts collection (and the 10-year collection clock).
- Abatement: the IRS removing a penalty (and its attached interest) from your account, either on request or automatically.
- Reasonable cause: the legal standard for penalty relief. You exercised ordinary care, and circumstances beyond your control caused the failure.
- Accruing vs. one-time penalty: failure-to-file and failure-to-pay grow monthly until capped; accuracy-related and fraud penalties are a single fixed hit.
- Levy vs. lien: a levy takes money or property; a lien is a legal claim against what you own. Renters mostly face levies.
- CSED: the Collection Statute Expiration Date, generally 10 years from assessment, after which the IRS can no longer collect (certain events pause it).
Common questions
What is the most common IRS penalty?
By count, the failure-to-pay penalty and the estimated-tax underpayment penalty are the two the IRS assesses most often, hitting millions of individual taxpayers each year. The failure-to-file penalty is less common and far more expensive, at 5% of the unpaid tax per month versus 0.5%. If your balance ballooned quickly, late filing is usually the reason.
What is the maximum IRS penalty for filing and paying late?
Combined late-filing and late-payment penalties can reach 47.5% of the unpaid tax, made up of 22.5% for filing late (after the overlap reduction) plus 25% for paying late, before interest is added. Returns more than 60 days late also face a minimum failure-to-file penalty, an inflation-adjusted dollar amount that applies even to small balances.
Can the IRS levy my bank account over penalties alone?
Yes. Penalties and interest are assessed to your account just like tax, so the collection sequence, from the CP14 bill through the final notice of intent to levy, runs on the whole balance. A bank levy freezes funds for 21 days before they're sent to the IRS, which is your window to get it released. A wage levy continues until released.
Bottom line
Most of the gap between the tax you owed and the balance on your notice is failure-to-file, failure-to-pay and interest. File first so the 5% meter stops. Then ask for First-Time Abate or reasonable cause relief, and set up a payment plan so the failure-to-pay rate drops and the levy track closes.
Your next 24 hours
- Find the penalty lines on your notice. Every IRS bill has a breakdown box separating tax, penalties and interest. Circle each penalty by name, because each one has a different removal path.
- Gather your records: the notice itself, your last three years of returns (that's the First-Time Abate test), and any proof of the event that knocked you off track, such as hospital records, a disaster declaration or a job loss date.
- Get a free penalty review. Use the 2-minute form or call (888) 825-7779. Penalties and interest accrue monthly until the balance is addressed, and if a levy notice is in your stack, every option is stronger before the money moves.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.